
News & AnalysisCareer

October’s United States (US) Consumer Price Index (CPI), due at 13:30 GMT, is becoming the focus for investors as AUD/USD remains rangebound. During Tuesday’s European session, the Australian Dollar (AUD) is little changed against the US Dollar (USD), trading at around 0.6925.
Wednesday’s US headline CPI reading is forecast at 3.9% year-on-year (YoY), up from 3.7% previously. An increase is also expected in core CPI, which strips out volatile food and energy items, to 2.8% from the previous reading of 2.6%.
Unless the figures diverge sharply from expectations, the US CPI release is unlikely to substantially change the anticipated path of Federal Reserve (Fed) monetary policy. Falling oil prices have caused global inflation expectations to become de-anchored.
The CME FedWatch tool indicates that traders remain confident of a 25 basis point (bps) Fed rate increase at the December meeting, taking the range to 4.00%-4.25%. The probability of that hawkish outcome has risen to 84.2%, compared with 77.4% a week earlier.
Strong October US Nonfarm Payrolls (NFP) figures prompted traders to increase their bets on a hawkish Fed. Released on Friday, the data showed 165K jobs were added, well above the 65K forecast and the previous reading of 60K.
In Australia, attention turns to November’s Consumer Inflation Expectations figures, due on Thursday. With recent comments from policymakers signalling considerable concern over elevated inflation, the release is likely to have a substantial influence on expectations for Reserve Bank of Australia (RBA) monetary policy.
Speaking last week, RBA Deputy Governor Andrew Hauser said: “Inflation is too high, whichever measure you use,”
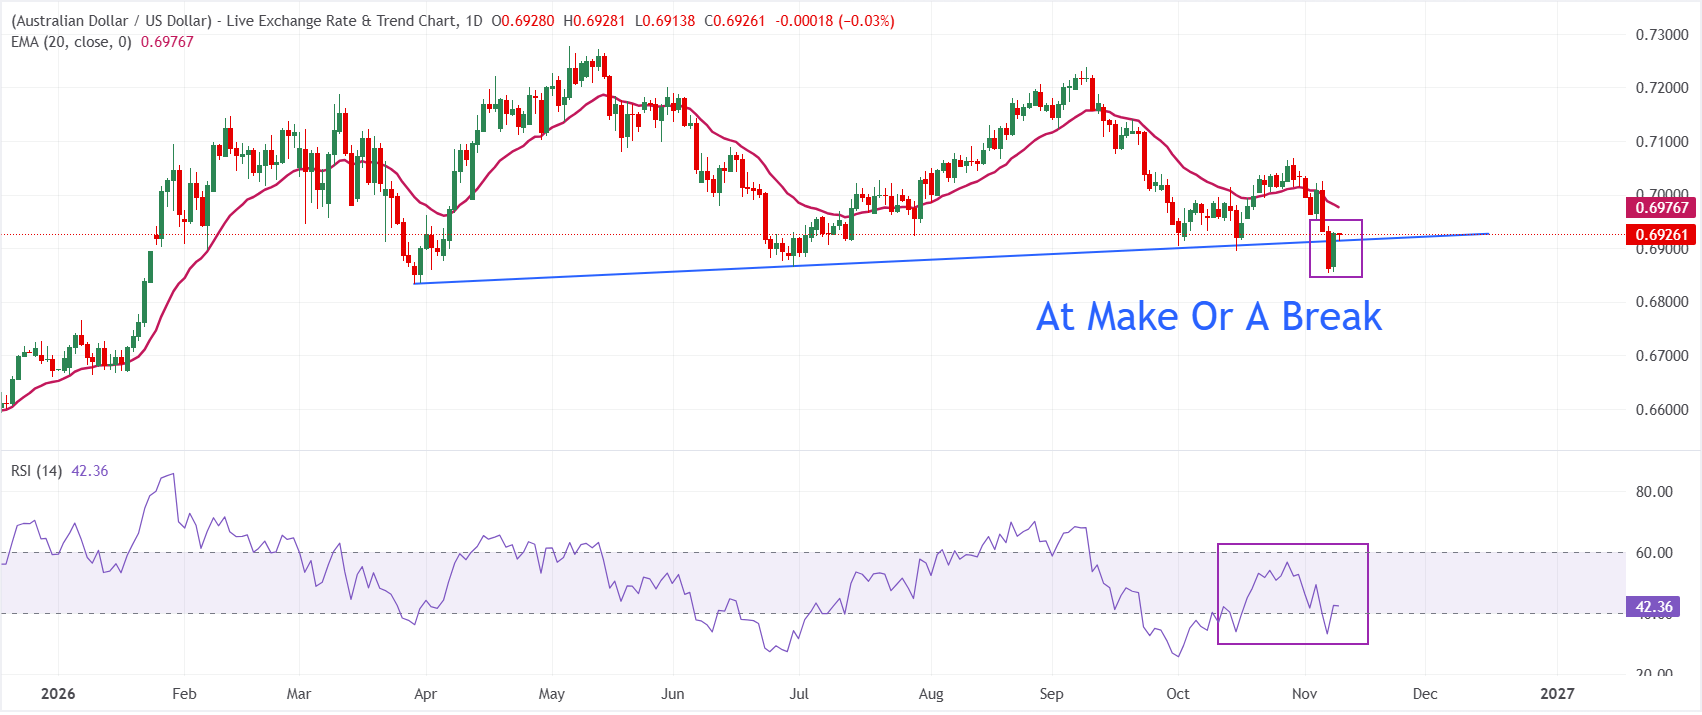
At 0.6926 on the daily chart, AUD/USD sits only marginally above the former rising support line near 0.6914. The 20-day Exponential Moving Average (EMA), around 0.6977, continues to cap the pair. As long as this dynamic barrier remains overhead, the short-term bias favours the downside. Momentum is muted, with the Relative Strength Index (14) in the low-40s, suggesting that attempts to recover may struggle below the moving average.
The 20-day EMA at 0.6977 marks the first resistance level. A daily close above it would be required to relieve immediate bearish pressure. Initial support lies around the nearby trend line at 0.6914; a decisive break beneath this area would open the way to lower levels and strengthen the prevailing weak tone in AUD/USD.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
As the official currency of the United States of America, the US Dollar (USD) also serves as the ‘de facto’ currency in a significant number of other countries, circulating alongside their local banknotes. Data from 2022 show that it accounts for over 88% of global foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion, making it the world’s most actively traded currency. After the Second World War, the USD replaced the British Pound as the world’s reserve currency. Gold backed the US Dollar for much of its history, until the Bretton Woods Agreement in 1971 brought the Gold Standard to an end.
Monetary policy, set by the Federal Reserve (Fed), is the single biggest influence on the US Dollar’s value. Maintaining price stability by controlling inflation and promoting full employment are the Fed’s two mandates. Adjustments to interest rates are its main means of pursuing these objectives. If prices climb too rapidly and inflation exceeds the Fed’s 2% target, it raises rates, supporting the USD. Conversely, inflation below 2% or an excessively high Unemployment Rate may prompt the Fed to cut interest rates, putting pressure on the Greenback.
In exceptional circumstances, the Federal Reserve can create additional Dollars and introduce quantitative easing (QE), substantially expanding the supply of credit to a financial system that has stalled. This unconventional policy is used when credit dries up because banks refuse to lend to one another for fear of counterparty default. It is a measure of last resort when interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, the Fed chose QE to tackle the credit crunch. Under this policy, it prints additional Dollars to purchase US government bonds, primarily from financial institutions. The US Dollar typically weakens as a result of QE.
Reversing that process, quantitative tightening (QT) sees the Federal Reserve cease bond purchases from financial institutions and refrain from reinvesting the principal repaid when its existing bonds mature. This policy is generally supportive of the US Dollar.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


