

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Will the ADP Employment Report show the expected slowdown in October job growth?
- A net addition of 69K jobs in October is expected in the US ADP Employment Change report.
- Confidence in robust US economic momentum is unlikely to weaken unless October’s ADP figures deliver a sharp disappointment.
- With the midterm election outcome dominating attention ahead of Friday’s NFP report, the US Dollar is likely to see only a limited response.
Confidence in the US economy faces its next employment test on Wednesday, when the Automatic Data Processing (ADP) Research Institute releases its October private-sector jobs report. Market expectations point to a modest easing in hiring: the ADP Employment Change is forecast to record 69K new private-sector jobs, compared with 90K in September.
For financial markets, ADP figures help frame expectations for the crucial Nonfarm Payrolls (NFP) report, which the US Bureau of Labor Statistics (BLS) usually publishes a couple of days afterwards. This Wednesday, attention will also turn to the US ISM Services Purchasing Managers Index (PMI). Above all, markets will be weighing the implications of the Democrats' victory in the US midterm elections.
Can the ADP Jobs Report Point to a Solid Labour Market Despite Slower Hiring?
Investor confidence in the US economic outlook has strengthened following a series of upbeat macroeconomic releases, setting the backdrop for October’s ADP employment figures. Last week’s preliminary Gross Domestic Product (GDP) estimate put third-quarter growth at an annualised 3.4%, led by consumer spending, investment and government expenditure.
Adding to that picture, the US ISM Manufacturing PMI released on Monday indicated a faster-than-expected acceleration in factory activity, pointing to a strong start to the fourth quarter.
Taken together, these releases reinforce the case for US economic exceptionalism. Alongside strong inflationary pressures, they create an ideal backdrop for further monetary tightening by the Federal Reserve (Fed). Futures markets assign a 75% probability to another quarter-point interest rate increase in December, according to the CME FedWatch tool. That prospect is helping the US Dollar Index (DXY) hold relatively steady near its year-to-date highs.
In this setting, only a pronounced setback in October’s ADP employment figures would be likely to cause significant disruption. The September Nonfarm Payrolls report recorded a 29K rise in employment, after 133K jobs were added in August. Those figures suggest a stabilising labour market, with no clear evidence of a downturn so far.
Nevertheless, the decisive Democratic victory in the US midterm elections could leave the Greenback under pressure on Wednesday. ING Analyst Francesco Pesole offers this assessment: “a Democratic sweep (...) could be seen as slightly negative for the US Dollar from a few angles, from higher risk of government shutdown and gridlock on debt ceiling negotiations to potential damage to already shaky AI-related sentiment.”
What time is the ADP release, and how much could it move the US Dollar?
A muted reaction in the US Dollar (USD) is likely when the US ADP Employment Change report is released on Wednesday at 13:15 GMT. Expectations are for 69K private-sector job additions in October, and the final figures are unlikely to change market expectations for a December Fed rate increase. Instead, the midterm election results are set to hold investors’ attention ahead of Friday’s crucial NFP report.
Later on Wednesday, a few hours after the ADP release, the US ISM Services PMI is forecast to indicate a slight slowdown in October. Even so, the anticipated reading would remain consistent with expansion and healthy activity in the sector. Here too, only a substantial disappointment would be likely to undermine market confidence in the US economy’s strength.
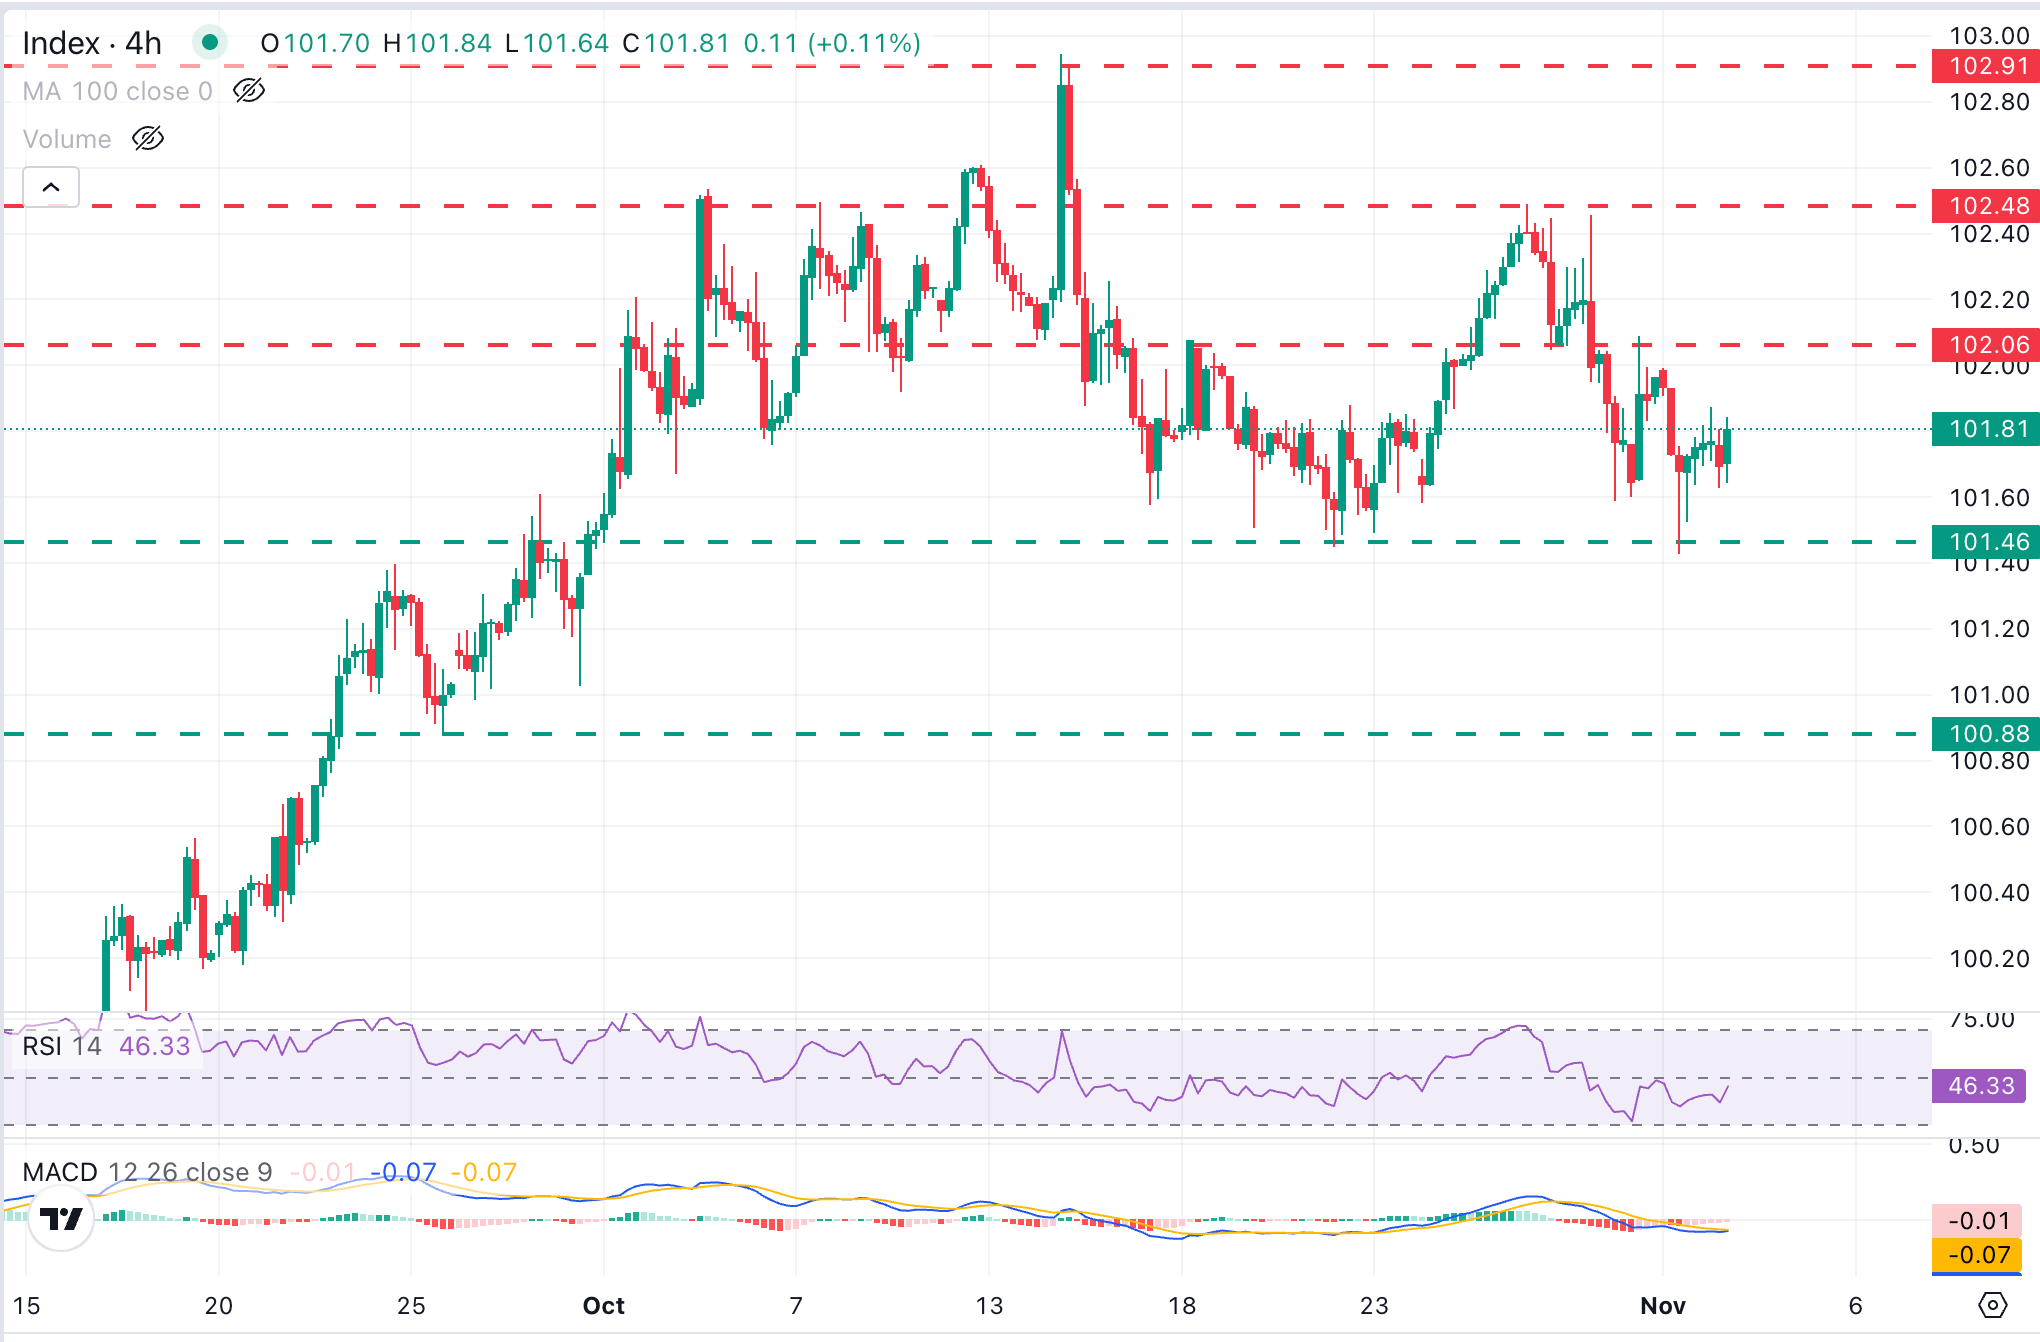
From a technical perspective, the US Dollar Index (DXY) is trading near the bottom of the range established since early October. Its 4-hour chart points to a neutral-to-bearish short-term bias. Directional conviction appears weak, with the Relative Strength Index (14) below the mid-50 area, while the Moving Average Convergence Divergence (MACD) histogram stays in negative territory. Together, these signals indicate modest selling pressure rather than a firmly established downtrend.
FXStreet FX analyst Guillermo Alcalá says a DXY break below support around 101.50, marking the lows of 22 October and 2 November, is needed to confirm a change in trend. Such a move would open the way towards the late-September lows in the 101.00 to 100.90 zone.
For resistance, Alcalá highlights the 30 October high just above 102.00, followed by the highs of 28 and 29 October around 102.50. These are the key upside hurdles before the 18-month peak of 102.95 reached in mid-October.
Employment: frequently asked questions
Currency valuations are strongly influenced by labour market conditions, which provide an important measure of an economy’s health. When employment is high, or unemployment low, consumer spending and economic growth tend to benefit, supporting the domestic currency. A particularly tight labour market, where too few workers are available to fill vacancies, can also affect inflation and monetary policy. In such conditions, strong demand for labour combined with limited supply pushes wages higher.
For policymakers, the rate of salary increases across an economy is a crucial consideration. Rapid wage growth gives households more spending power, typically driving up consumer goods prices. Unlike volatile inflation drivers such as energy prices, salary increases are unlikely to be reversed. Wage growth is therefore regarded as an important source of persistent underlying inflation. This is why central banks worldwide closely monitor wage data when setting monetary policy.
A central bank’s objectives determine how much emphasis it places on labour market conditions. For some, employment-related responsibilities are explicitly part of the mandate, alongside inflation control. For instance, the US Federal Reserve (Fed) has a dual mandate to promote maximum employment and stable prices, whereas the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Regardless of these differences, policymakers regard labour market conditions as important because they indicate the economy’s health and are directly linked to inflation.
Economic data indicator
ADP Employment Change
Published by Automatic Data Processing Inc., the largest US payroll processor, the ADP Employment Change tracks changes in the number of people employed in the country’s private sector. An increase generally supports consumer spending and stimulates economic growth. Accordingly, markets traditionally view a strong reading as bullish for the US Dollar (USD) and a weak one as bearish.
Explore further.Next scheduled release: Wed 04 Nov 2026 13:15
Release frequency: Every month
Consensus estimate: 69K
Prior reading: 90K
Data source: ADP Research Institute
A stronger-than-consensus ADP employment reading tends to support the USD. Traders frequently use the report from ADP, America’s largest payrolls provider, as an early indication of the Bureau of Labor Statistics Nonfarm Payrolls release, usually published two days later, given the correlation between the two series. Although the series track each other closely overall, individual months can show sizeable divergences. FX traders also monitor ADP for the same reason they watch NFP: sustained, robust employment growth adds to inflationary pressures, making a Fed interest rate increase more likely.
POPULAR ARTICLES
1Crypto Today: Why are Bitcoin, Ethereum and XRP extending gains as US Dollar falls on Democrats' US midterm win?2Euro approaches four-week highs as gains continue amid hot Eurozone inflation figures3Pi Network Price Forecast: PI nears record lows as hopes of a bullish breakout weaken4Eurozone October flash HICP growth accelerates by 4% YoY, in line with expectations5Swedish Krona: SEK draws support from Riksbank rate hikes – Societe Generale6Silver Price Forecast: Why Is XAG/USD Rallying to $52.00 as Yields Fall and the US Dollar Weakens?7Swiss Franc: Is the risk of a hawkish SNB lending support to the franc? – ING8Silver price today: FXStreet data show a rise in Silver9Will the ADP Employment Report show the expected slowdown in October job growth?

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved