
News & AnalysisCareer

A fall to $3,965 in Friday’s Asian session takes Gold (XAU/USD) to its weakest level since July, with expectations of further Federal Reserve (Fed) interest rate rises continuing to weigh on the metal. Those expectations remain the dominant influence on prices despite the risk-averse mood across markets, putting Gold on course for a monthly decline. XAU/USD stands at around $3,979 at the time of writing, a loss of nearly 1% on the day.
Disappointing technology earnings have revived doubts about substantial AI expenditure and the adequacy of the returns it will deliver, prompting traders to reduce their appetite for risk. Government bonds attract investors, lowering US Treasury yields and pulling the US Dollar lower.
At around 101.65, the US Dollar Index (DXY) is heading for a third successive day of losses. The index measures the Greenback against a basket of six major currencies.
Positioning could matter more than fundamentals for the Dollar in the near term, according to analysts at ING. They warn that “the main risk for the dollar today is some precautionary unwinding of net-long positions ahead of Tuesday’s US midterm elections.” The analysts point out that “a Democratic sweep is trading around 68% in prediction markets,” describing that outcome as “slightly negative for the US dollar from a few angles, from higher risk of government shutdown and gridlock on debt ceiling negotiations to potential damage to already shaky AI-related sentiment.”
ING nevertheless sees limits to the potential decline. While cautioning that “resurgent AI-related jitters and the upcoming US midterms are increasing downside risks for the dollar,” it notes that “a still-hawkish Fed argues against major corrections.”
Reports that cryptocurrency exchange Binance has suffered a major security breach add to investor unease and put pressure on digital assets. Yet the shift away from risk has offered Gold no support so far. Traders remain focused instead on the implications for inflation and interest rates of rising oil prices linked to Middle East tensions.
Fears that the US may restart military strikes against Iran after next week’s US midterm elections have driven oil prices to their highest since May. With West Texas Intermediate (WTI) above $103 a barrel, the inflationary risks stemming from energy remain in focus.
Thursday’s figures showed September headline Personal Consumption Expenditures (PCE) inflation rising by 0.5% MoM and 3.6% YoY, alongside core increases of 0.3% MoM and 3.1% YoY. More expensive energy threatens to prolong the period in which inflation remains above the Fed’s 2% target.
Following the Fed’s decision to hold rates steady in October, traders now assign roughly a 75% probability to a December rate rise, according to the CME FedWatch Tool. As Gold pays no interest, higher borrowing costs generally act as a drag on the metal.
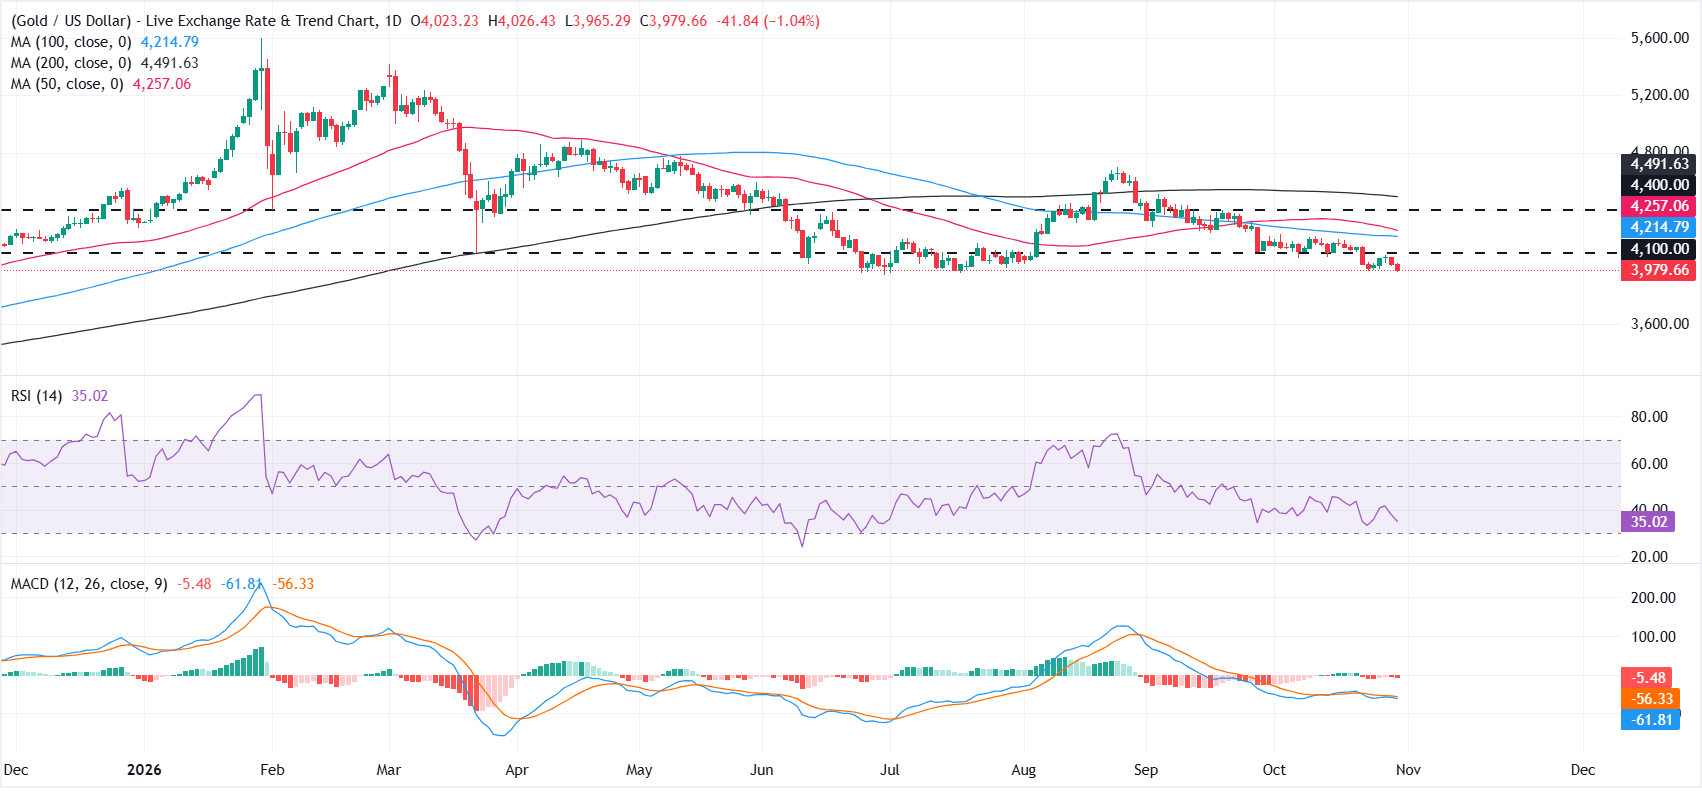
Since reaching a peak near $4,700 in late August, XAU/USD has traced a succession of lower highs and lower lows on the daily chart. Sellers retain the advantage, with prices beneath the 50-day, 100-day and 200-day Simple Moving Averages (SMAs). Buying appetite appears muted, as indicated by a Relative Strength Index (RSI) reading near 34. Meanwhile, the Moving Average Convergence Divergence (MACD) stays below zero, pointing to continued downward pressure.
Any recovery would first encounter resistance at $4,000 and then $4,100. Beyond those levels lie the 100-day SMA near $4,218 and the nearby 50-day SMA at $4,257. A more sustained rebound could put horizontal resistance at $4,400 in view, ahead of the 200-day SMA around $4,491.
Below the $4,000 level at which Gold is already trading, the nearest support is $3,950, with the July low near $3,941 next in line. A clear break beneath this zone would leave scope for additional declines.
(The technical analysis of this story was written with the help of an AI tool. Learn more.)
Widely used both to preserve wealth and as a means of exchange, Gold has held an important place throughout human history. Beyond its lustre and role in jewellery, the precious metal is now commonly regarded as a safe-haven asset, or a worthwhile investment in periods of turmoil. Its independence from any particular issuer or government also underpins its widespread use as a hedge against inflation and currency depreciation.
The largest holders of Gold are central banks. To bolster their currencies during unsettled periods, they typically diversify their reserves and purchase Gold, strengthening perceptions of their economies and currencies. Substantial Gold holdings can reinforce confidence in a country’s solvency. World Gold Council figures show that central banks increased their reserves by 1,136 tonnes of Gold, valued at around $70 billion, in 2022. No higher annual purchase has been recorded since records began. Emerging-market central banks, including those of China, India and Turkey, are rapidly building their Gold reserves.
Both the US Dollar and US Treasuries are major reserve and safe-haven assets, and Gold is inversely correlated with them. A decline in the Dollar usually coincides with a rise in Gold, allowing investors and central banks to diversify their holdings during turbulent periods. The metal also has an inverse relationship with risk assets: rising equity markets tend to put pressure on Gold prices, whereas selling in riskier markets generally supports the precious metal.
Numerous influences can shift Gold prices. Its safe-haven appeal means geopolitical turmoil or concern over a severe recession can trigger a rapid price rise. Lower interest rates generally support Gold because it provides no yield; conversely, higher borrowing costs tend to weigh on the metal. Nevertheless, movements in the US Dollar (USD) account for most price changes, given that Gold is quoted in dollars (XAU/USD). Dollar strength typically restrains Gold prices, while a weaker currency is likely to lift them.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


