
News & AnalysisCareer

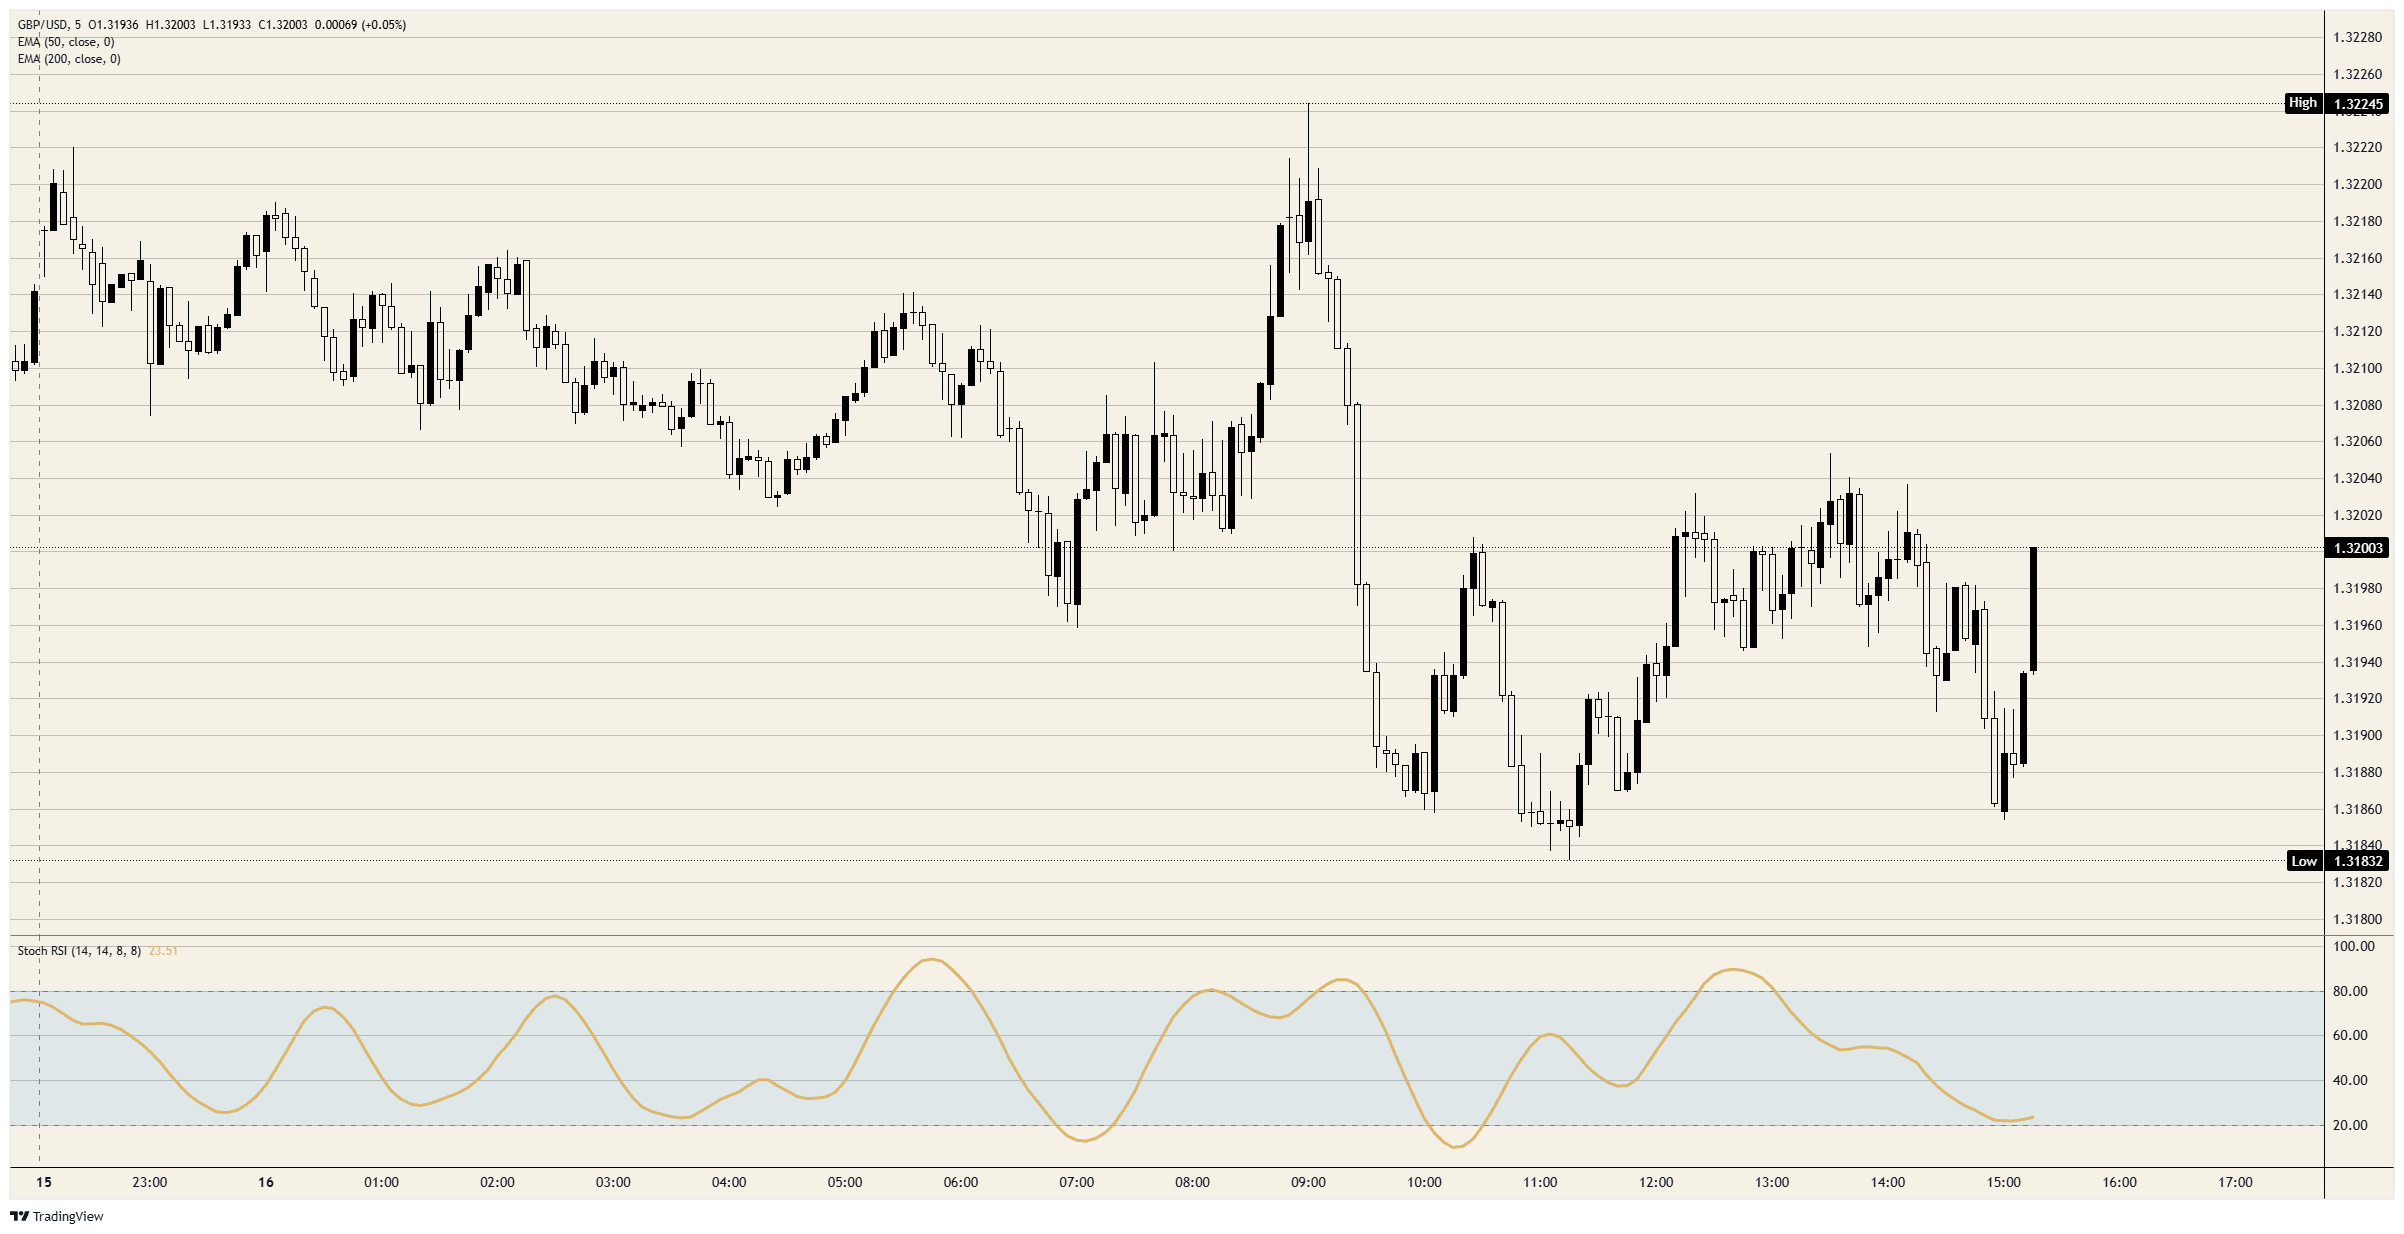
With a Fed rate rise regarded by traders as certain, the Dollar has continued to advance, leaving GBP/USD heading for its fifth consecutive daily decline. No UK data are scheduled for Monday. From a session peak between 1.3200 and 1.3250, the pair slipped below 1.3200 over ten five-minute bars before reaching a one-month low. It has since returned to around 1.3200.
October’s Consumer Price Index (CPI) increased by 0.4% month on month, exceeding the 0.3% forecast and setting the decline in motion on 10 November. According to CME FedWatch, markets have fully priced in a quarter-point Fed rate rise on 9 December. That would take US interest rates back above those in the UK, where the Bank of England (BoE) lifted Bank Rate to 4.00% on 5 November, matching the upper end of the Fed’s 3.75%-4.00% range.
A sell-off in chip stocks ahead of Tuesday’s quarterly results from Nvidia (NVDA) accompanied a decline in global equities. Credit Agricole attributed the Dollar’s gains to interest rates and risk aversion, while Reuters reported that the currency had reached its highest level against a basket of currencies since April 2025. November’s New York Fed Empire State index dropped from 25.5 to 7.8, below the forecast of 18. GBP/USD is trading at its pre-release level.
An unchanged unemployment rate of 4.7% is forecast in Tuesday’s UK labour market figures, due at 07:00 GMT. Wednesday brings October CPI at 07:00 GMT, with annual inflation expected to rise to 3.7% from 3.5%; BoE Governor Bailey then speaks at 07:30 GMT and again at 15:00 GMT. Friday’s retail sales figures, also scheduled for 07:00 GMT, complete the three releases that will inform the BoE’s 17 December decision.
Opening remarks from Fed Chair Warsh at a San Francisco Fed conference are scheduled for 17:00 GMT on Monday. On Tuesday, US retail sales are expected to show growth of 0.2%, following 0.8%, when released at 13:30 GMT. Minutes from the Fed’s 27-28 October meeting arrive on Wednesday at 19:00 GMT. These will inform the 9 December decision and, in turn, the US side of the interest-rate differential.
More than four-fifths of the advance from the 14 October low just below 1.3150 to the 4 November peak near 1.3500 has now been erased. The decline has returned GBP/USD to its late-September to mid-October trading range, beneath both the 50-day Exponential Moving Average (EMA) around 1.3350 and the 200-day EMA just below 1.3400. Having left overbought territory when the decline began, daily momentum continues to weaken.
Dating back to 886 AD, the Pound Sterling (GBP) is the world’s oldest currency and serves as the United Kingdom’s official currency. Figures for 2022 place it fourth among the world’s most traded foreign exchange (FX) currencies, with a 12% share of all transactions and average daily turnover of $630 billion. Among its principal pairs, GBP/USD, also called ‘Cable’, represents 11% of FX trading. GBP/JPY, known to traders as the ‘Dragon’, accounts for 3%, while EUR/GBP accounts for 2%. Responsibility for issuing the Pound Sterling lies with the Bank of England (BoE).
Monetary policy set by the Bank of England has the greatest influence on the Pound Sterling’s value. In making its decisions, the BoE assesses whether its central objective of “price stability” has been met, meaning inflation holding steady at around 2%. Interest-rate changes are its main means of pursuing that objective. To curb excessive inflation, the BoE will seek to raise borrowing costs through higher interest rates, making credit more expensive for households and businesses. GBP generally benefits because higher rates increase the appeal of the UK as a destination for international investment. By contrast, inflation that falls too low signals slowing economic growth. The BoE will then consider cutting rates to make credit cheaper, encouraging businesses to borrow more and invest in projects that support growth.
By revealing the state of the economy, data releases can affect the Pound Sterling’s value. GDP, Manufacturing and Services PMIs, and employment figures are among the indicators capable of moving GBP. Economic strength supports Sterling by drawing in foreign investment and potentially prompting the BoE to raise interest rates, which directly strengthens GBP. Weak economic figures, on the other hand, are likely to weigh on the Pound Sterling.
The trade balance is another important release for the Pound Sterling, recording the gap between a country’s export earnings and its spending on imports during a specified period. Strong overseas demand for a country’s exports creates additional demand for its currency as foreign buyers seek to purchase those goods. A positive net trade balance therefore supports the currency, whereas a negative balance has the opposite effect.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved

