

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
104.00: United States Dollar Index sets new 19-month high amid hawkish Fed tone
- 104.00 comes into view as the US Dollar Index surges on hawkish Fed comments.
- Successive Fed interest rate increases in December and March remain firmly expected by traders.
- Among the couple of policymakers who warned of a larger December rate increase, Fed’s Waller is expected to be one.
October’s Federal Open Market Committee (FOMC) meeting minutes indicated that almost all members consider additional interest rate increases “justified”. They also warned that “inflation may be more persistent than anticipated”. The hawkish message leaves the US Dollar (USD) ahead of its major currency peers on Thursday.
US Dollar: Today’s Currency Moves
The US Dollar’s largest gain today was against the Australian Dollar. Its percentage changes against the listed major currencies appear in the table below.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.14% | 0.17% | 0.19% | 0.17% | 0.52% | -0.02% | 0.12% | |
| EUR | -0.14% | 0.02% | 0.03% | 0.02% | 0.39% | -0.17% | -0.04% | |
| GBP | -0.17% | -0.02% | 0.02% | -0.00% | 0.36% | -0.19% | -0.06% | |
| JPY | -0.19% | -0.03% | -0.02% | -0.03% | 0.34% | -0.24% | -0.09% | |
| CAD | -0.17% | -0.02% | 0.00% | 0.03% | 0.36% | -0.20% | -0.06% | |
| AUD | -0.52% | -0.39% | -0.36% | -0.34% | -0.36% | -0.54% | -0.45% | |
| NZD | 0.02% | 0.17% | 0.19% | 0.24% | 0.20% | 0.54% | 0.16% | |
| CHF | -0.12% | 0.04% | 0.06% | 0.09% | 0.06% | 0.45% | -0.16% |
Percentage movements between the major currencies are displayed in the heat map. Select the base currency in the left-hand column and the quote currency in the top row. Selecting the US Dollar on the left and following that row across to the Japanese Yen, for instance, gives the percentage change for USD (base)/JPY (quote) in the corresponding cell.
At around 104.00, the US Dollar Index (DXY) is up 0.2% at the time of writing, reaching its highest level in over 19 months. The index measures the Greenback against six major currencies.
Rate increases of 25 basis points (bps) at both the December and January policy meetings are almost certain, according to the CME FedWatch tool. It also puts the probability of a further increase in March at almost 50%.
Released on Wednesday, the FOMC minutes also revealed that a couple of policymakers had warned of a larger December interest rate increase, “if incoming inflation figures were negative”.
Fed Governor Christopher Waller appears to be among them. Ahead of the October inflation release, he said a larger rate increase at the December meeting would become appropriate if core Consumer Price Index (CPI) growth stayed at 0.3% or above.
103.95: US Dollar Index Technical Outlook
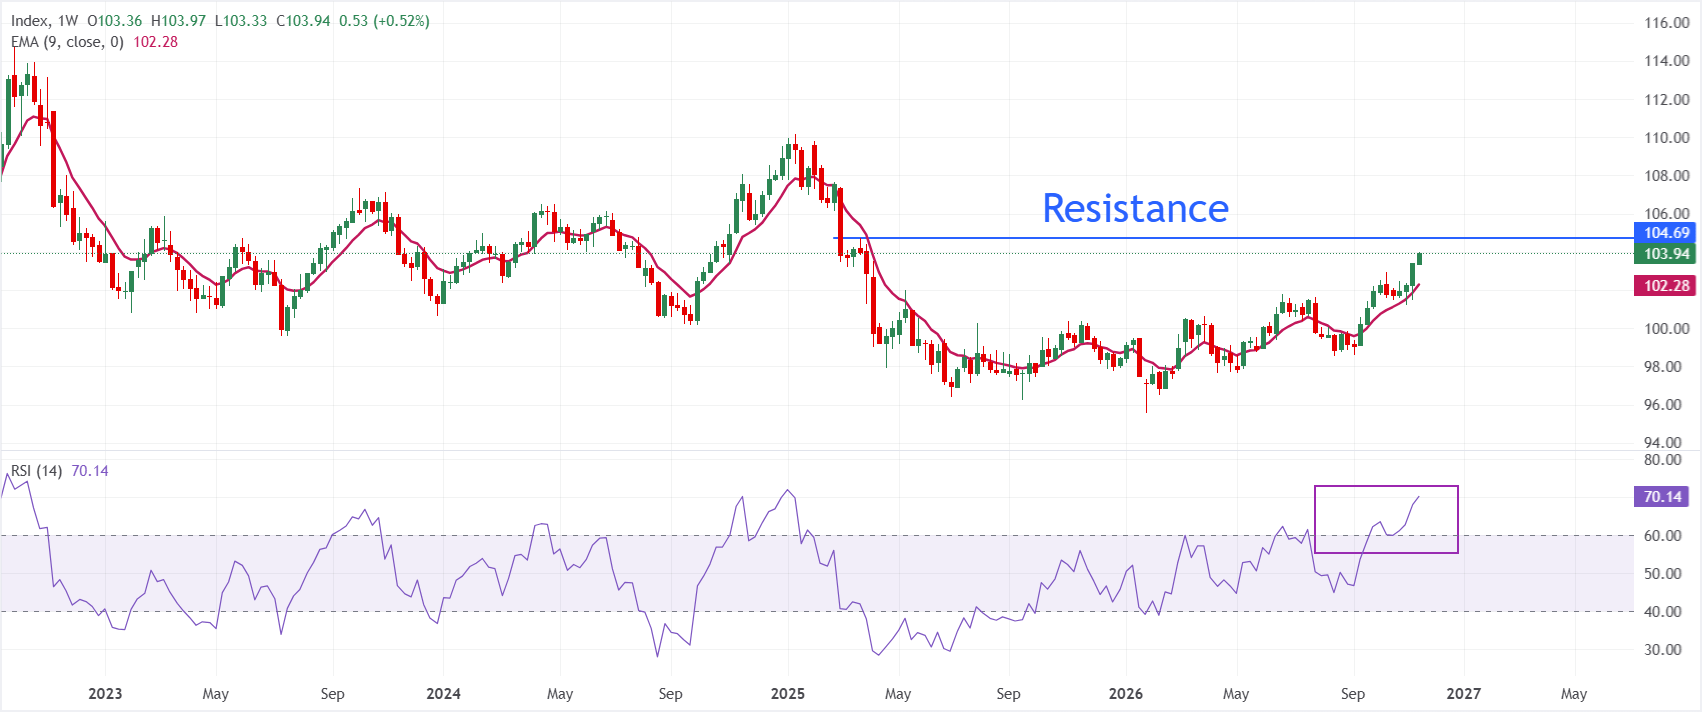
Dollar Index Spot stands at 103.95 on the weekly chart. Holding above the nine-week exponential moving average (EMA) of 102.28 preserves the near-term bullish bias and supports the medium-term uptrend. At 70.15, the Relative Strength Index (14) is now in overbought territory. This points to stretched upside conditions, although trend support continues to underpin price action.
Further gains could take the index towards 104.70. On a pullback, the 20-week EMA near 101.33 is expected to provide key dynamic support.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Fed: Key Questions Answered
The Federal Reserve (Fed) sets US monetary policy, with two mandates: price stability and full employment. Adjusting interest rates is its main means of pursuing those objectives. If prices increase too rapidly and inflation exceeds the Fed’s 2% target, the central bank raises rates. Higher borrowing costs across the economy make the US more attractive to international investors, strengthening the US Dollar (USD). Conversely, inflation below 2% or an excessively high Unemployment Rate may prompt the Fed to cut rates. The aim is to stimulate borrowing, but the move weighs on the Greenback.
At the Federal Reserve’s (Fed) eight policy meetings each year, the Federal Open Market Committee (FOMC) reviews economic conditions and decides monetary policy. Twelve Fed officials attend the FOMC: all seven members of the Board of Governors, the Federal Reserve Bank of New York president and four of the other eleven regional Reserve Bank presidents. Those four positions rotate, with each president serving a one-year term.
When conditions become extreme, the Federal Reserve may turn to Quantitative Easing (QE) to substantially expand credit flows through a stalled financial system. This unconventional measure is used in crises or periods of exceptionally low inflation. During the Great Financial Crisis in 2008, it was the Fed’s preferred policy response. Under QE, the Fed prints additional Dollars to purchase high-grade bonds from financial institutions. The US Dollar typically weakens as a result.
By reversing QE, quantitative tightening (QT) generally supports the US Dollar’s value. The Federal Reserve ceases bond purchases from financial institutions and, as bonds in its portfolio mature, does not use the repaid principal to buy new bonds.
POPULAR ARTICLES
1South African Rand: Outlook clouded despite SARB pause – Societe Generale2Below $3,700: Gold price forecast stays fragile as XAU/USD recovers3Dow Jones futures advance as Anthropic IPO market debut approaches41.2180: Aussie rebounds but bearish bias persists in AUD/NZD Price Forecast5Japanese Yen: UOB sees continued range trading against US Dollar6Oil price surge offsets US Dollar strength, leaving Canadian Dollar little changed7Euro: Strong dollar challenges macro resilience – ING8Swiss Franc remains steady after key economic releases9British Pound: Sterling draws support from inflation pressures – Commerzbank


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved