

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Indian Rupee gains as oil prices fall and AI trades unwind
- Multiple supportive factors drive a sharp Indian Rupee advance against the US Dollar.
- Cheaper oil and the unwinding of AI positions provide support for the Indian currency.
- Three consecutive interest rate increases are expected from the Fed.
93.62 is back in view as USD/INR revisits its six-month low. The Indian Rupee (INR) opens sharply stronger against the US Dollar (USD) on Tuesday. Cheaper oil and steady foreign fund inflows linked to the global unwinding of the Artificial Intelligence (AI) trade are supporting the Indian currency and weighing on the pair.
Oil prices fall as supply surplus hopes grow
Despite attacks on tankers in the Middle East, the region’s energy exports are increasing, fuelling expectations of excess supply. Reuters reported that the International Energy Agency (IEA) said last week that the global oil market would move back into surplus in the fourth quarter of this year. Middle East exports are recovering faster than global oil demand despite attacks on shipping.
A 1.53% decline takes the MCX Crude Oil contract expiring on November 19 to around Rs. 7,955 in opening trade. Prices remain near their almost 11-week low of Rs. 7,861. For economies such as India, which depend heavily on imported oil for their energy needs, lower crude prices support their currencies.
Indian equities draw further FII inflows
Foreign Institutional Investors (FIIs) continue to allocate funds to Indian equities as the AI trade unwinds rapidly worldwide. The reversal follows the victory of United States (US) Democrats in the midterm elections and the resignation of Nvidia CEO Jensen Huang.
In an interview with the Indian Express newspaper published on Monday, India’s Chief Economic Advisor (CEA) V Anantha Nageswaran said, “India’s status as a non-AI play is definitely weighing positively on the Indian market sentiment and also drawing in foreign institutional investors in the near term.”
Net share purchases by FIIs total Rs. 84,167.40 crore so far in November. They have been net buyers in every trading session apart from the Diwali Muhurat session.
Hawkish Fed signals underpin US Dollar outperformance
103.70 marked a fresh 19-month high for the US Dollar Index (DXY) in early Tuesday trading before it pulled back. Market experts’ expectations of successive Federal Reserve (Fed) interest rate increases, however, suggest the index is likely to recover its strength.
According to analysts at MUFG/BTMU, the steep hawkish reassessment of Fed policy has fed directly into the US rates market. The market is now "assigning a higher probability to three consecutive hikes in December, January and March, which would lift the effective Fed funds rate towards 4.6%."
93.65: USD/INR technical outlook remains bearish
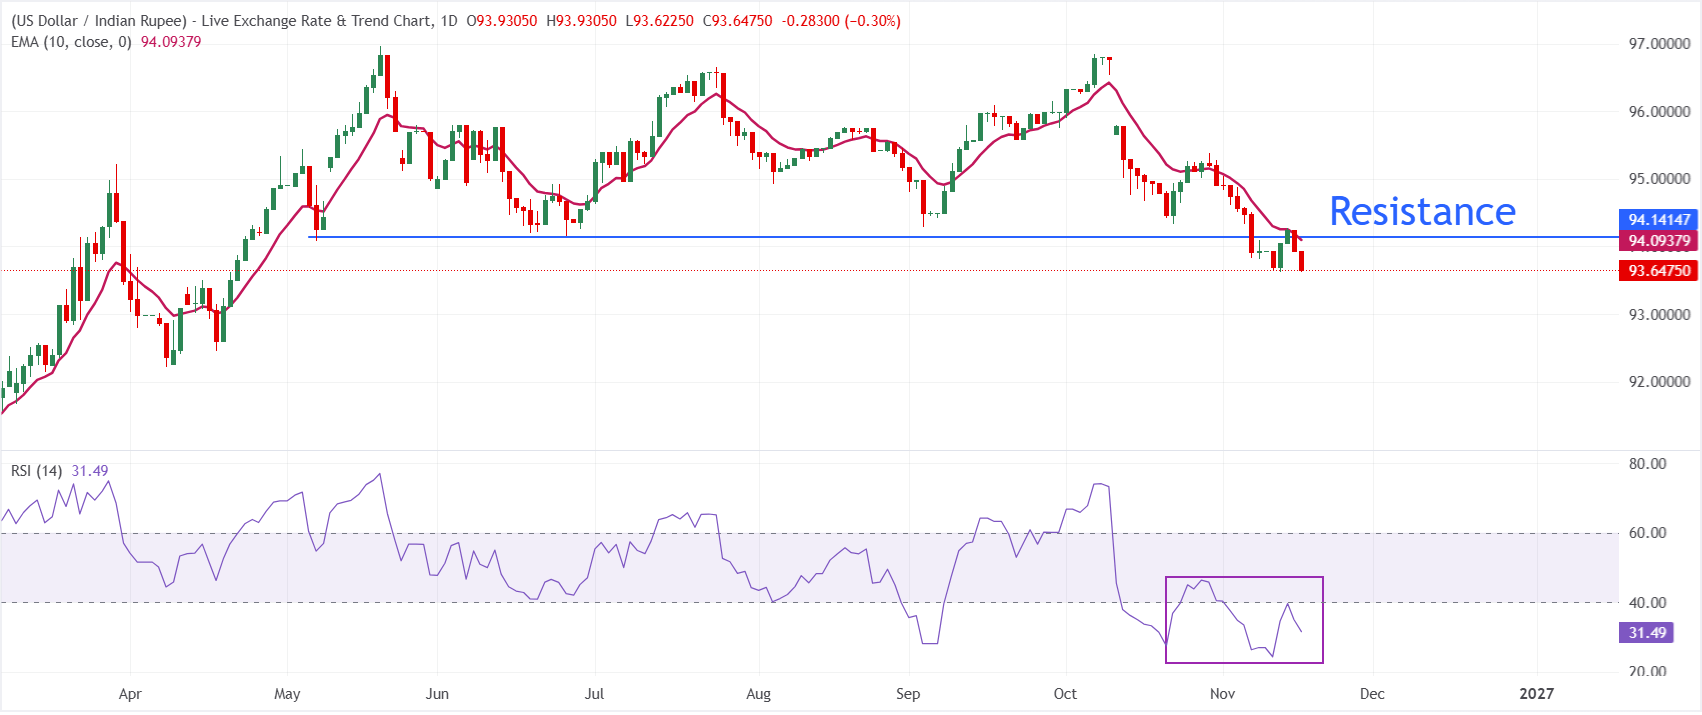
At 93.65 on the daily chart, USD/INR retains a bearish near-term outlook. Spot remains below the 10-day exponential moving average (EMA) at 94.09. The break beneath this short-term average indicates that immediate overhead supply is limiting rebounds. Meanwhile, the Relative Strength Index (RSI) reads 31.58, just above oversold territory, suggesting that selling pressure persists but is not yet exhausted.
The 10-day EMA near 94.10 provides the first resistance on the upside. Only a sustained recovery above that barrier would ease the bearish tone and create room for a broader corrective rebound. On the downside, 93.00 would serve as key support.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: frequently asked questions
External developments have a particularly strong influence on the Indian Rupee (INR). Key drivers include Crude Oil prices, given India’s heavy reliance on imported oil; the US Dollar’s value, as most trade is settled in USD; and foreign investment flows. The Reserve Bank of India (RBI) also plays a major role through its interest rate settings and direct FX market intervention aimed at stabilising the exchange rate.
To facilitate trade, the Reserve Bank of India (RBI) actively intervenes in foreign exchange markets to keep the exchange rate stable. It also adjusts interest rates with the aim of keeping inflation at its 4% target. Higher rates typically support the Rupee through the ‘carry trade’. This involves investors borrowing in lower-interest-rate countries and investing in countries offering relatively higher rates to earn the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and increase demand for the currency. A narrowing trade deficit will eventually strengthen the Rupee. Higher interest rates are supportive too, particularly higher real rates, which are interest rates minus inflation. When risk appetite improves, larger inflows of Foreign Direct and Indirect Investment (FDI and FII) can also support the currency.
The Rupee generally suffers when inflation rises, especially when it exceeds that of India’s peers, because it signals a loss of currency value through oversupply. Higher inflation also raises export costs and results in more Rupees being sold to buy foreign imports, adding pressure on the currency. However, rising inflation usually prompts the Reserve Bank of India (RBI) to increase interest rates. The resulting increase in demand from international investors can support the Rupee. Lower inflation has the reverse effects.
POPULAR ARTICLES
1UK data in focus as British Pound slips further against Japanese Yen2Indonesian Rupiah advances amid Treasury sell-off and US Dollar weakness3Indian Rupee gains as oil prices fall and AI trades unwind41.1000: EUR/USD sustains gains above this level, but price forecast remains bearish below 100-day SMA5One-month low: British Pound rebounds against weaker USD as traders await UK jobs data6US tech curbs dent sentiment as Asian stocks fall ahead of Nvidia earnings7$0.0551 record low: Pi Network Price Forecast as bears drive PI lower8India Gold price today: FXStreet data shows prices rising9Mid-$83.00s: WTI Price Forecast Suggests Vulnerability Below 200-EMA and 50% Fibo.


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved