
News & AnalysisCareer

A recovery in oil prices and caution before the Federal Reserve’s (Fed) monetary policy decision are among the headwinds weighing on the Indian Rupee (INR) on Wednesday. Having surrendered its early gains, the Rupee slips slightly against the US Dollar (USD), with USD/INR edging towards 95.16 as the Indian currency underperforms.
At the start of trading, the MCX Crude Oil contract expiring on 19 November stands near Rs. 9,671, up 1.82% and approaching its recent highs of Rs. 9,828.
For economies such as India, where imported oil meets a substantial share of energy requirements, rising crude prices are unfavourable for their currencies.
According to a military spokesperson for Yemen's Iran-aligned Houthis on Tuesday, the group fired a ballistic missile towards the Ras Tanura oil refinery in eastern Saudi Arabia, the kingdom’s largest refinery, Reuters reported.
Oil prices have risen as the attack heightens concerns over a further escalation in risks to energy supplies.
United States (US) Treasury yields have also received support from higher oil prices, reducing the attraction of riskier currencies such as the Indian Rupee. At the time of writing, the yield on 10-year US bonds stands near 5.02%, up 0.46%.
An unchanged interest rate range of 3.75%-4.00% is expected from the Fed, according to the CME FedWatch tool. The monetary policy announcement later in the day will provide the main catalyst for global markets.
At its September meeting, the Fed raised interest rates by a quarter of a percentage point, while its dot plot indicated at least one further increase this year.
Following that September announcement, financial markets were confident of another Fed increase in October. Those hawkish expectations subsequently eased, however, after several policymakers indicated that a further rate rise was not urgent.
An FXS Speechtracker score of 8/10, compared with a historical average of 7.2/10, highlights the distinctly hawkish tone of Fed official Waller’s remarks and a preference for additional tightening. His assertion that “more hikes [are] needed”, alongside the qualification that they “do not need to come at consecutive meetings”, points to a higher terminal rate reached through a more flexible sequence of increases. For the Dollar, support comes from expectations that restrictive policy will last longer, rather than from a rapid succession of near-term rate rises. Waller’s focus on persistent sources of inflation, including AI-related investment, continuing energy shocks and a labour market that remains “solid and stable”, underlines the risk of inflation expectations becoming unanchored after nearly 5½ years of above-target inflation. The policy bias therefore remains clearly hawkish.
With a 0.42-point increase to 138.34, the FXS Fed Sentiment Index confirmed that the speech shifted the policy tone further into hawkish territory, well beyond the neutral reading of 100. Together with the above-baseline FXS Speechtracker score, that elevated reading should support the Dollar as markets factor in a longer spell of restrictive interest rates, even if successive meetings do not consistently bring further increases.
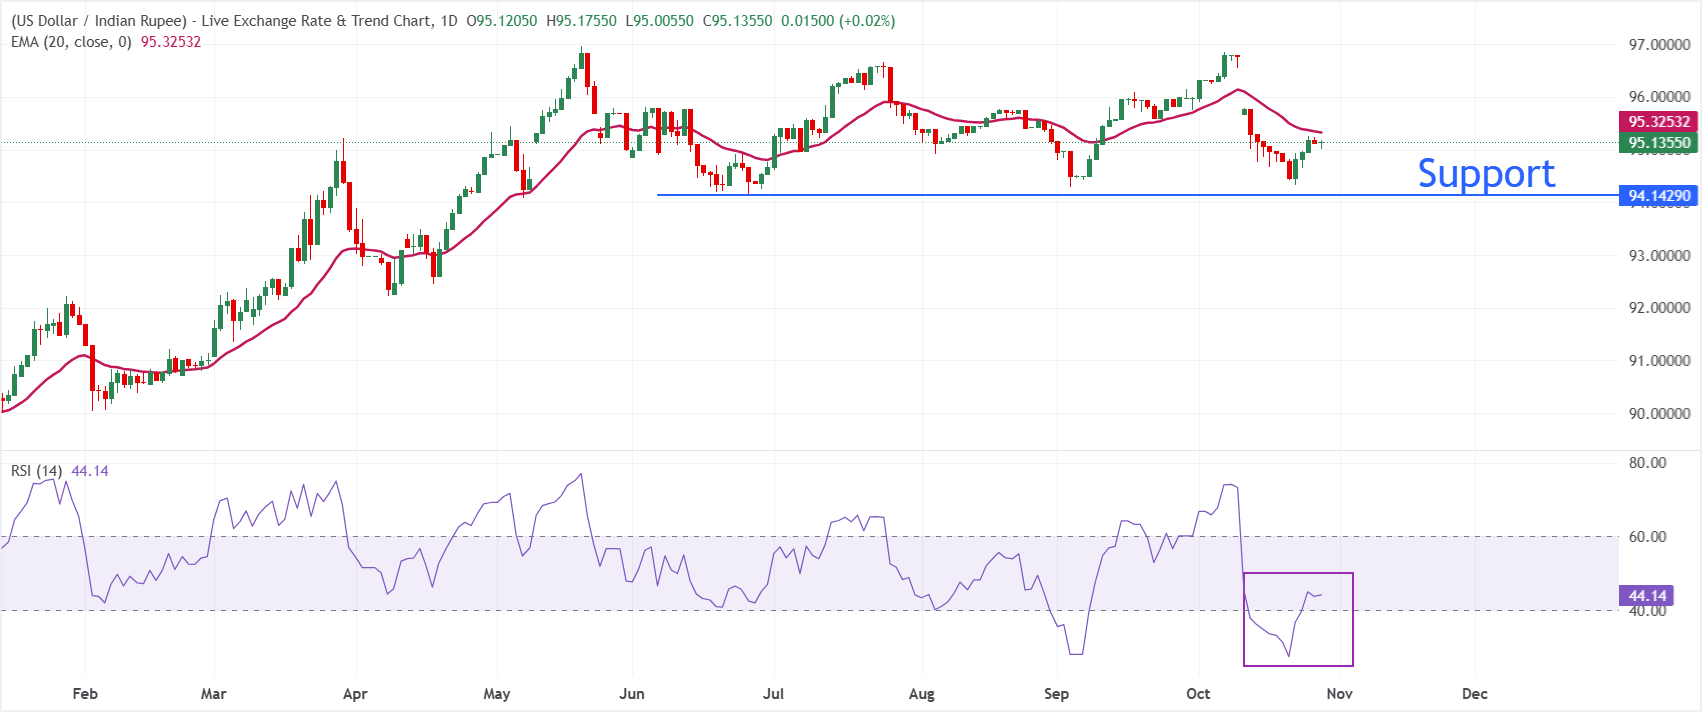
Trading at 95.1355 on the daily chart, USD/INR remains below its 20-period exponential moving average (EMA) of 95.3253, leaving the near-term outlook bearish. Failure to regain this short-term average indicates that rallies are attracting selling. Meanwhile, a Relative Strength Index (RSI) reading of around 44 lies in neutral-to-soft territory, pointing to limited upward momentum rather than outright oversold conditions.
The 20-day EMA at 95.3253 provides the first resistance level. A sustained move above it would be required to relieve immediate downward pressure and allow a more substantial recovery. With the available indicators offering no clearly defined support levels nearby, price behaviour around this EMA remains the main focus. Continued trading below it is likely to maintain the short-term bearish bias.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
External developments have a particularly strong influence on the Indian Rupee (INR). Important drivers include Crude Oil prices, given India’s heavy reliance on imported oil; the US Dollar’s value, as most trade is denominated in USD; and the scale of foreign investment. The Reserve Bank of India (RBI) also plays a major role through direct intervention in foreign exchange markets to stabilise the exchange rate and through the interest rates it sets.
To facilitate trade, the Reserve Bank of India (RBI) intervenes actively in foreign exchange markets to keep the exchange rate stable. It also adjusts interest rates in an effort to maintain inflation at its 4% target. Rate increases typically support the Rupee through the ‘carry trade’: investors borrow in countries where rates are lower and invest in those offering relatively higher rates, seeking to profit from the difference.
Inflation, interest rates, economic growth (GDP), the trade balance and foreign investment inflows all help determine the Rupee’s value. Faster growth can attract additional overseas investment and increase demand for the currency, while a smaller trade deficit will eventually strengthen it. Higher interest rates are another supportive factor, particularly when measured in real terms, after subtracting inflation. Greater appetite for risk can encourage inflows of Foreign Direct and Indirect Investment (FDI and FII), benefiting the Rupee as well.
When inflation is high, especially relative to India’s peers, it generally weighs on the Rupee because it reflects a loss of currency value through oversupply. Higher inflation also raises export costs and leads to more Rupees being sold to buy foreign imports, adding to the pressure on the currency. However, it usually prompts the Reserve Bank of India (RBI) to increase interest rates, which can support the Rupee by attracting stronger demand from international investors. Lower inflation has the reverse effects.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved

