
News & AnalysisCareer

With the Federal Reserve expected to leave the Fed funds rate unchanged at 3.75–4.00% at Wednesday’s policy meeting, the US Dollar (USD) remains well supported across global FX markets. Futures markets assign only 10% odds to an October rate increase, and investors have swiftly turned their attention to resilient US economic growth and stubborn price pressures. Forecasts for robust Q3 real GDP growth of around 3.2% annualised, alongside accelerating core PCE inflation, underpin the assessment of institutional strategists at Brown Brothers Harriman (BBH) and TD Securities. They regard the anticipated pause as a tactical step ahead of further monetary tightening in December, rather than a dovish shift, preserving the Greenback’s yield advantage.
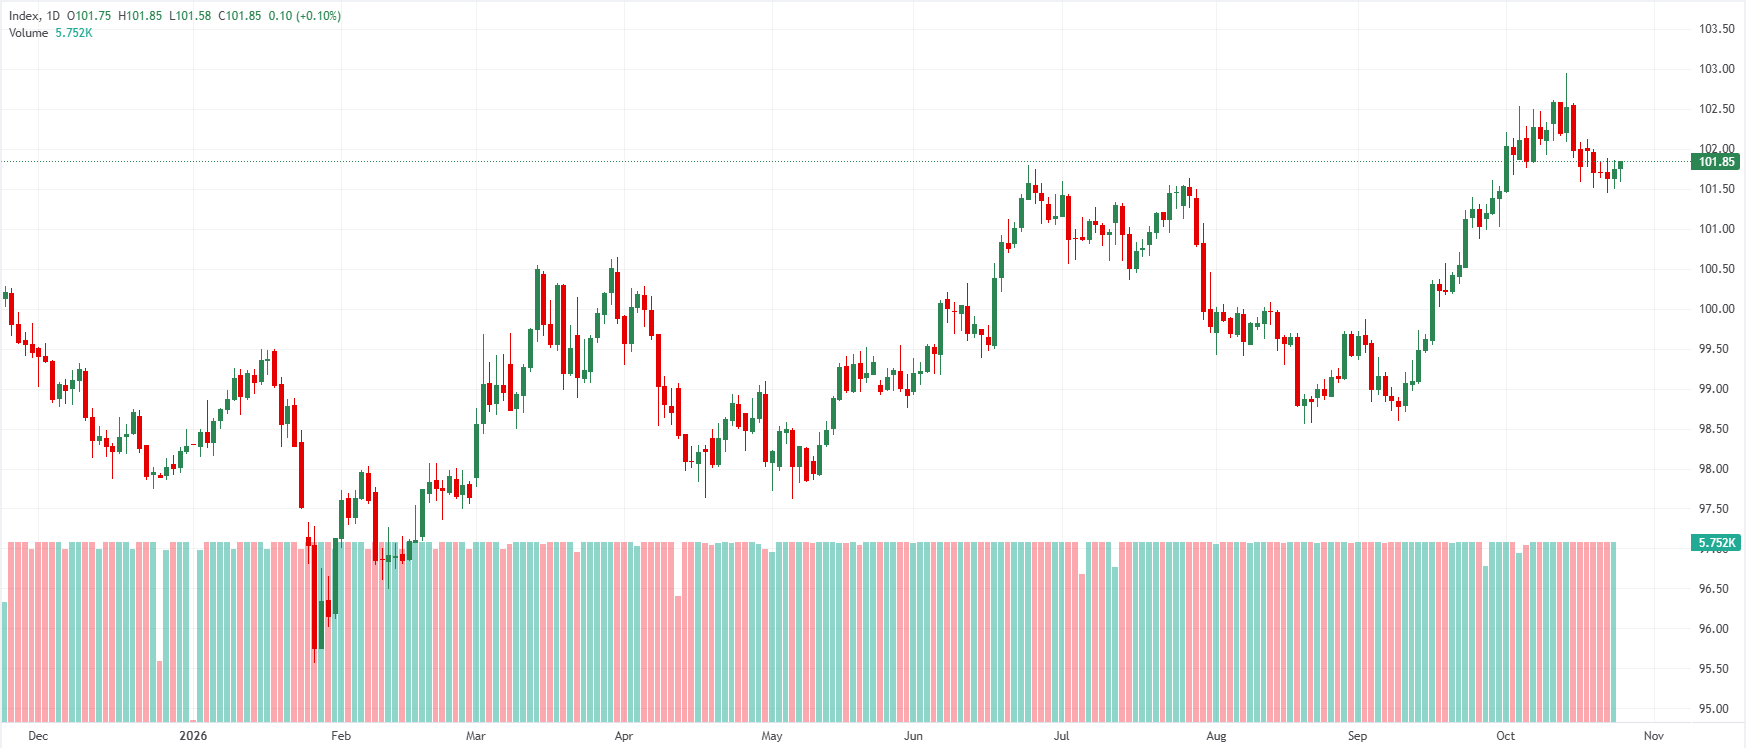
An unchanged Federal Reserve interest rate of 3.75–4.00% is the forecast for this week from Elias Haddad at Brown Brothers Harriman (BBH). He notes that key Fed officials’ calls for patience are consistent with markets assigning just 10% odds to an October increase. Nevertheless, forecasts put Q3 GDP growth at a 3.2% annualised pace and September core PCE inflation at an accelerating 3.1% year-on-year. Against that backdrop, Haddad believes buoyant private-sector activity and persistent inflation risks will continue to underpin the US Dollar, while a December rate increase is almost fully priced in.
"The FOMC is expected to keep the Fed funds target range steady at 3.75-4.00% after raising rates 25bps in September. Calls for patience from several key Fed officials support a pause. Futures market imply only 10% odds of a hike this week, with a December 9 rate increase virtually fully price in... Overall, robust US economic activity and rising price pressures argue for additional Fed funds rate hikes, offering ongoing USD support... Headline PCE is seen rising 0.5% m/m... and quicken to 3.6% y/y... Real GDP growth is anticipated to rise 3.2% annualized... driven by consumer spending and AI-related business investment."
An October policy rate of 3.75-4.00% is the expectation of Oscar Munoz and Eli Nir at TD Securities. In their view, the Fed will meet current market expectations without offering aggressive new forward guidance. They argue that holding rates steady in October would make a December increase more likely, potentially by a larger 50 basis points (bps) if inflation data remain firm. With sticky price pressures still to be addressed, TD Securities retains a hawkish outlook for the cycle and anticipates two further rate increases, in December and March.
"We expect the FOMC to keep rates on hold this week despite rising inflation risks. The chance of a surprise hike is higher than normal, but we believe they will prioritize patience and wait until December. A hold in October will make a December hike all the more likely. After the upside surprise in September CPI, inflation risks are still pertinent... We expect the Fed to hike two more times (December and March). Inflation remains above target while risks are growing."
A decision by the FOMC to keep rates at 3.75–4.00%, as widely anticipated, would signal tactical patience rather than a dovish shift and leave the US Dollar with strong support. For BBH, the main factors sustaining demand for the Greenback are accelerating PCE inflation at 3.6% year-on-year and robust Q3 GDP growth of 3.2% annualised, driven by AI investment. Meanwhile, TD Securities argues that an October pause increases the likelihood of further tightening in December and March, keeping the US Dollar’s interest rate advantage firmly in place into the coming year.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


