
News & AnalysisCareer

Due at 21:45 GMT on Wednesday, Stats NZ's third-quarter Consumer Price Index (CPI) precedes the Reserve Bank of New Zealand's (RBNZ) 28 October decision, with NZD/USD sitting just below its 50-day average. Five consecutive daily advances have lifted the pair to slightly above 0.5700, its strongest level since 23 September. Swap markets imply roughly an 80% probability of an increase in the Official Cash Rate (OCR) from 2.75% to 3.00%. The inflation figures could therefore cement expectations of a rise or bring them back into question.
New Zealand's annual growth in card spending accelerated to 6.9% in September from 3.5% in August, providing the kind of evidence of stronger domestic spending that keeps a rate rise in contention. On Wednesday, the New Zealand Dollar ranked among the better-performing major currencies as the US Dollar weakened against most of its peers. Following RBNZ increases in July and on 2 September, a third rise to 3.00% would bring the OCR to within a percentage point of the midpoint of the Fed's 3.75%-4.00% range.
Although RBNZ Chief Economist Conway described the October decision as wide open, he said interest rates were most likely heading higher. The record of the 2 September increase to 2.75% showed that he and one other committee member considered inflation risks balanced; the remaining four judged them to be skewed to the upside. Thus, one of the committee's two members who previously saw balanced risks now regards higher rates as the most likely outcome.
Crude Oil prices and the exchange rate were also cited by Chief Economist Conway as upside inflation risks, linking the policy decision directly to NZD/USD. Since a weaker Kiwi makes everything New Zealand imports more expensive, the rally over five sessions has reduced one of the risks he identified.
Forecasts put the quarterly increase in third-quarter CPI at 0.8%, down from 1.5%, while annual inflation is expected to slow from 4.1% to 3.8%. Against these figures, the RBNZ projects 0.8% and 3.9%, respectively. With a target range of 1%-3%, even an outcome in line with the market forecast would leave annual inflation 0.8 percentage points above the upper limit. The central bank anticipates a return to that range by mid-2027, followed by the 2% midpoint later that year.
Unless inflation comes in well below expectations, analysts anticipate a rate increase on 28 October. A third-quarter reading below the RBNZ's projection is possible, although second-quarter inflation reached 4.1%, exceeding its 3.9% forecast. An annual reading of 3.9% or higher would leave an increase almost fully priced into NZD/USD, with the nearby 50-day average overhead providing the first test. In the view of some analysts, the Kiwi is already undervalued relative to its short-term fair value.
US jobless claims are forecast at 200K, compared with the previous 199K, ahead of Thursday's release at 12:30 GMT. Friday brings S&P Global's preliminary US Purchasing Managers Index (PMI) figures at 13:45 GMT. Expectations are for manufacturing to ease from 55.9 to 55.6 and services from 58.8 to 57.9.
Fed futures indicate unchanged rates on 28 October and roughly a 90% probability of an increase by December. For the Kiwi, the significance lies in the two central banks adjusting the same interest-rate gap from opposite sides. An October RBNZ rise of a quarter-point would narrow the differential by a quarter-point, only for a December Fed increase of a quarter-point to restore the original gap. Consequently, US figures that strengthen the case for a December increase diminish the benefit to NZD/USD of an October RBNZ move.
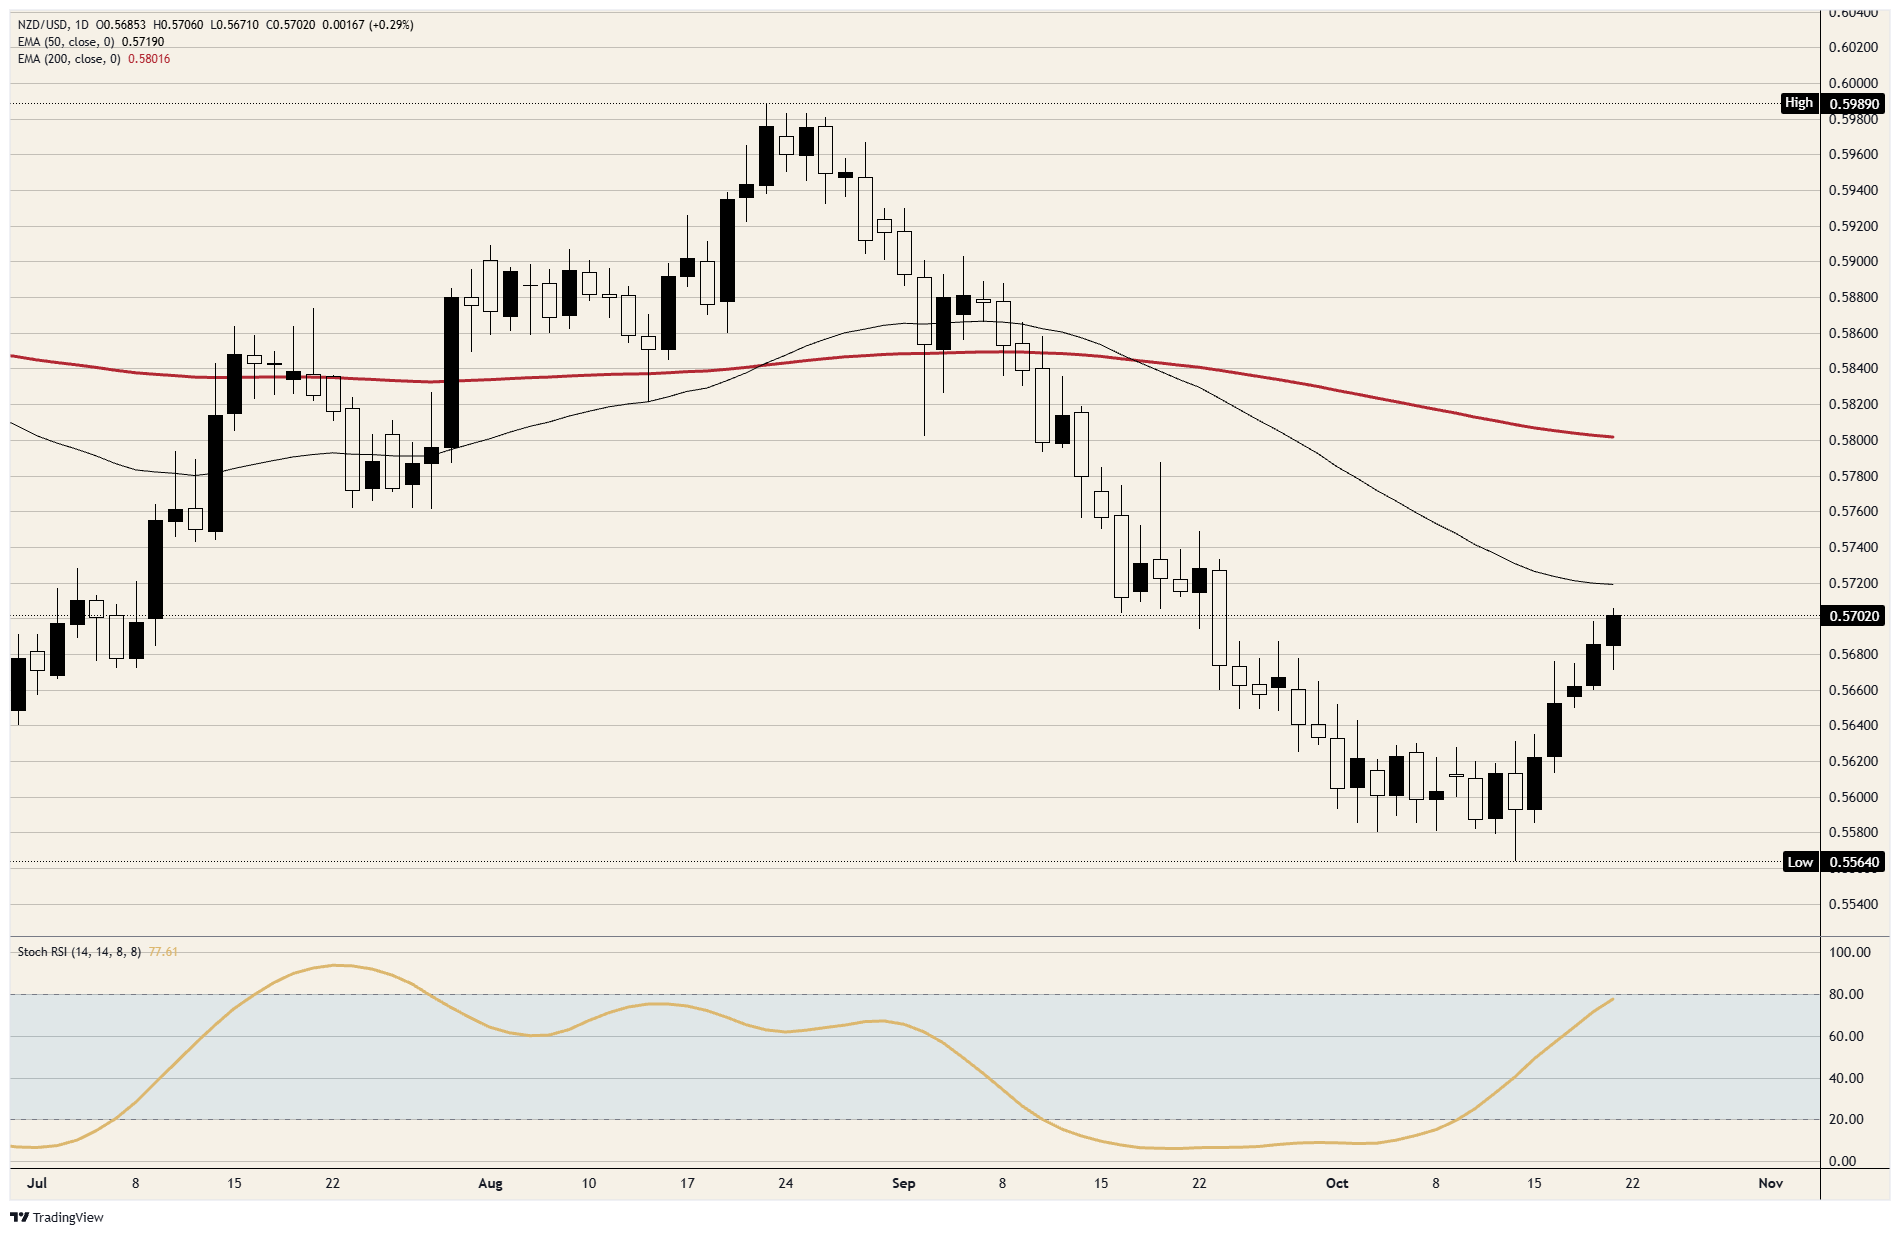
Resistance: Since early September, NZD/USD has traded below its 50-day Exponential Moving Average (EMA). Wednesday's high, slightly above 0.5700, fell just short of that average. The rebound on 22 September peaked at 0.5750, while the 18 September high lies just below 0.5800.
Support: At slightly above 0.5650, Wednesday's low remained higher than Tuesday's. The advance over five sessions began at 0.5600 on 15 October.
Bias: A long bias remains in place provided closing prices hold above 0.5650, with 0.5750 the first objective and 0.5800 the next. Having climbed to around 78, the daily Stochastic Relative Strength Index (Stoch RSI) is approaching overbought territory, leaving an extended rally exposed to a weaker-than-expected CPI reading. A daily close below 0.5600 invalidates the long position.
Known as the Kiwi, the New Zealand Dollar (NZD) is a familiar currency to investors in the foreign exchange market. New Zealand's economic health and central bank policy are its principal drivers, although several distinctive influences also affect its value. As China is New Zealand's largest trading partner, developments in the Chinese economy tend to influence the Kiwi. Negative Chinese economic news is likely to imply fewer New Zealand exports to that market, weighing on both the economy and its currency. Dairy prices are another important influence, given the industry's position as New Zealand's main export sector. Higher prices for dairy products lift export earnings, supporting the economy and, in turn, the NZD.
Keeping inflation between 1% and 3% over the medium term, with an emphasis on the 2% midpoint, is the Reserve Bank of New Zealand's (RBNZ) objective. It sets interest rates at a level intended to achieve that goal. Excessive inflation prompts the RBNZ to raise rates to restrain economic activity. Higher rates also lift bond yields, making investment in New Zealand more attractive and thereby supporting the NZD. Rate reductions, by contrast, generally weigh on the currency. NZD/USD can also be strongly influenced by the interest-rate differential: the comparison between actual or expected New Zealand rates and those set by the US Federal Reserve.
New Zealand's macroeconomic releases provide essential evidence of the economy's condition and can affect the valuation of the New Zealand Dollar (NZD). Strong growth, low unemployment and high confidence signal a healthy economy, which supports the currency. Rapid economic growth draws foreign investment and, when accompanied by elevated inflation, may encourage the Reserve Bank of New Zealand to raise interest rates. Weak economic figures, on the other hand, are likely to lead to NZD depreciation.
During risk-on periods, the New Zealand Dollar (NZD) generally appreciates as investors see limited risks across markets and take an optimistic view of growth. Such conditions usually improve the outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Market turbulence or economic uncertainty tends to have the opposite effect: investors typically sell riskier assets in favour of more stable safe havens, leaving the NZD weaker.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


