
News & AnalysisCareer

May’s Job Openings and Labor Turnover Survey (JOLTS), covering US employers’ estimates of vacancies, hiring and staff departures nationwide, is due from the US Bureau of Labor Statistics on Tuesday at 14:00 GMT. Markets pay close attention to the release, which usually precedes a series of employment indicators during the week, ending with the closely followed Nonfarm Payrolls report.

With inflation continuing to rise well above the central bank’s target, markets are reassessing the likelihood of interest rate increases from the US Federal Reserve (Fed). That makes Tuesday’s May JOLTS release particularly significant.
Despite the recent fall in crude oil prices, inflationary pressures have not subsided, while considerable uncertainty persists over the Middle East conflict. Investors’ expectations of at least one rate increase this year have been reinforced by the Fed’s renewed commitment to tackling inflation. Against this backdrop, this week’s labour market releases could prove crucial in judging when the next monetary policy adjustment might come, potentially adding fresh impetus to US Dollar (USD) volatility.
The market consensus puts May job openings at 7.28 million, a modest fall from April’s 7.61 million, the highest reading since July 2024. Nevertheless, the forecast would represent a solid result, comfortably exceeding the 2025 average of 7.08 million vacancies. Confirmation of these figures would probably support the view that the US labour market is stabilising and reinforce the narrative of US economic exceptionalism.
Against March’s 6.88 million vacancies, April’s JOLTS release showed a stronger-than-expected 4.6% monthly rise in openings, equivalent to 731,000 new vacancies. Quits, layoffs and discharges, meanwhile, were largely unchanged.
Adding to that picture, May’s US Nonfarm Payrolls report showed 172K new jobs, rounding off a strong three-month performance. Confidence in the US economy’s resilience to the Middle East war strengthened as a result. The figures also enabled Fed policymakers to set aside labour market concerns and concentrate exclusively on above-target inflation when shaping near-term monetary policy. In response to this changed backdrop, investors have increased their bets on some policy tightening over the coming months.
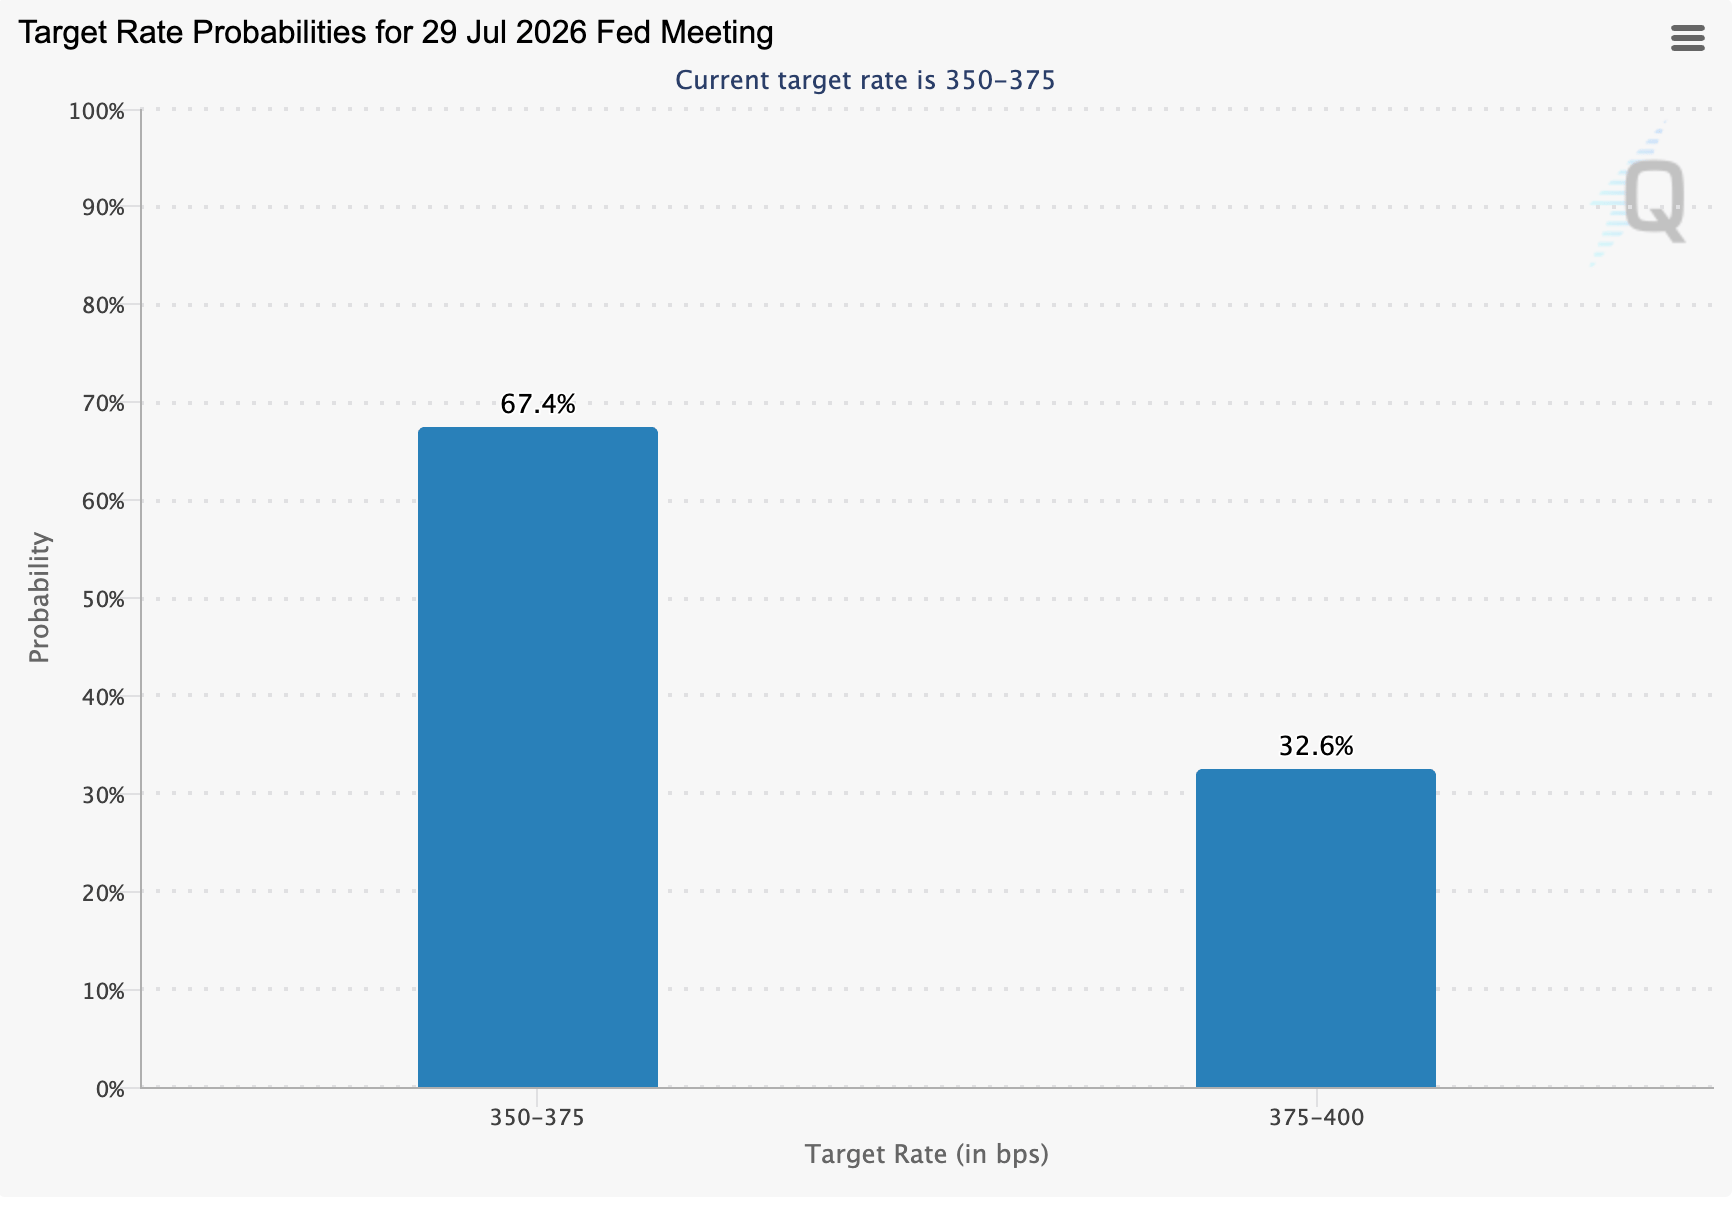
Futures markets assign a 30% probability to an interest rate rise at next month’s Federal Open Market Committee (FOMC) meeting and a more than 60% probability to monetary tightening in September, according to the CME Group’s Fedwatch Tool. Those odds have risen from 6% and 20% respectively a month earlier. Investors will scrutinise this week’s employment data to test those expectations.
Tuesday’s job openings release is scheduled for 15:00 GMT. With EUR/USD still relatively close to its 13-month lows, the pair is heading for a 2.17% fall in June and a decline of nearly 3% over the past two months.
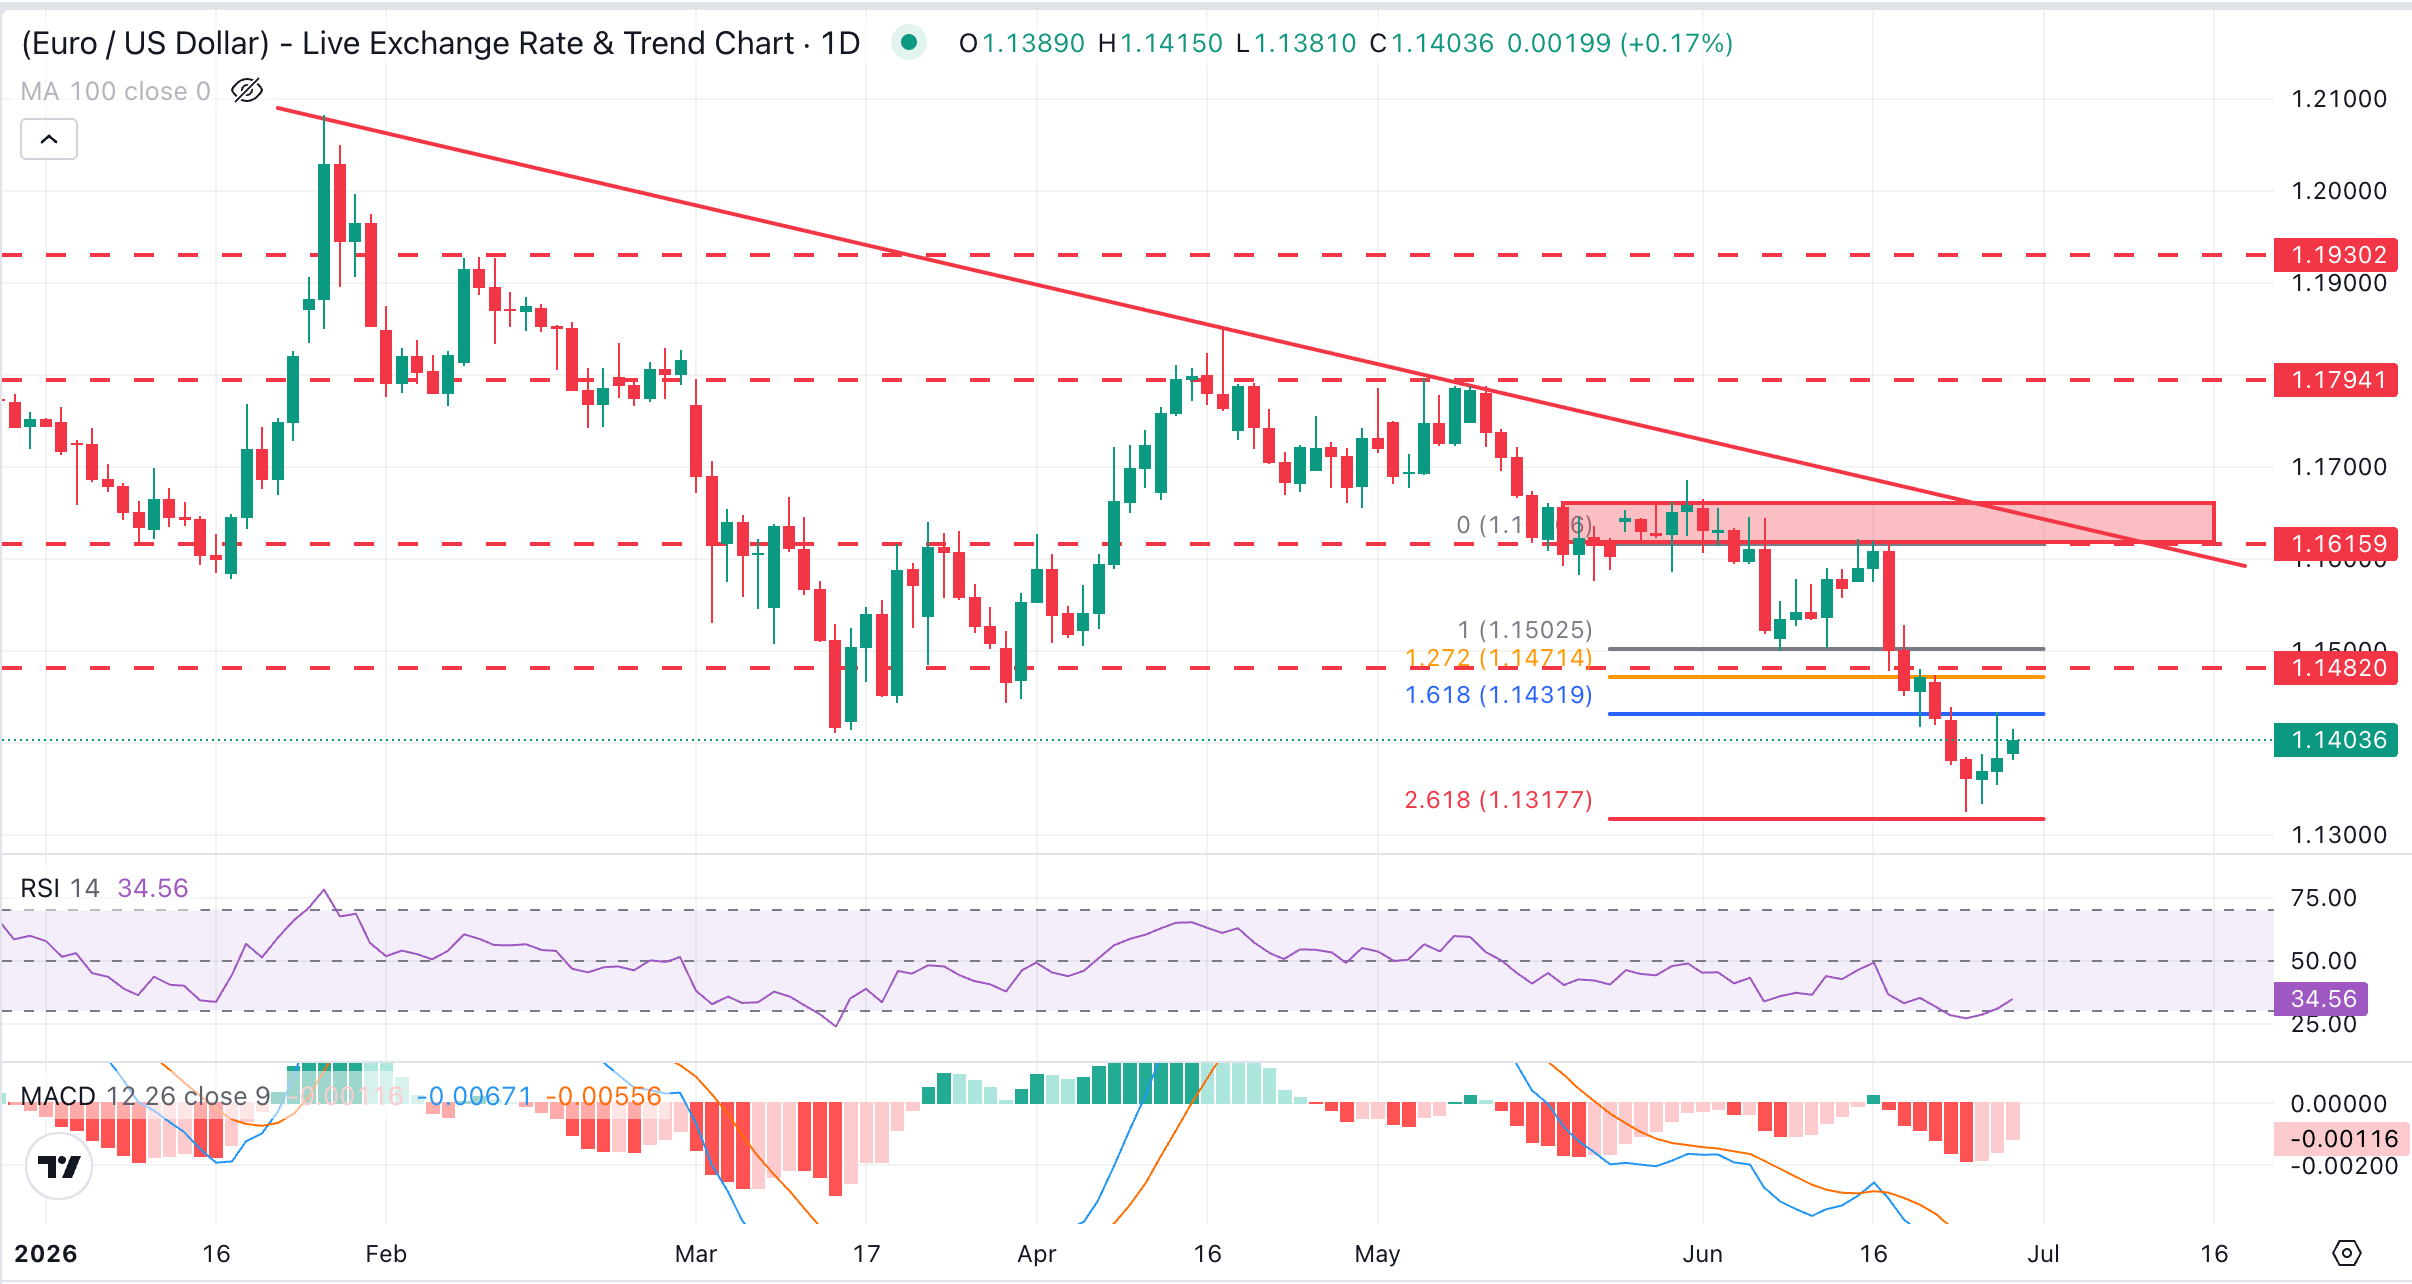
Continued US economic outperformance relative to the Eurozone, alongside the drag on risk appetite from Iran’s war, leaves the pair biased lower in the view of FXStreet analyst Guillermo Alcalá: “The Euro has remained vulnerable over the last two months amid geopolitical woes and a sluggish economic growth in the Eurozone. Unless the scenario changes significantly, Euro rallies are likely to offer good entry opportunities for sellers. The 13-month low at 1.1325 remains the key support level. Further down, bears might be tempted to revisit the late May 2025 low at 1.1210.”
For any recovery, Alcala identifies resistance at 1.1500 and 1.1620-1.1640 as the principal obstacles facing buyers: “The pair is struggling to consolidate above 1.1400 at the time of writing in a rebound from the mentioned 13-month lows, which, so far, seems corrective. Bulls should break the 1.1500 area (June 8,11 lows) and preferably also the area between 1.1620 and 1.1640, where late May and early June highs meet the descending trendline from the year-to-date (YTD) highs, to break the negative structure.”
Maintaining stable prices within a country or region is a central bank’s core responsibility. As the prices of individual goods and services fluctuate, economies continually face inflationary or deflationary pressures. A sustained increase in the price of the same goods constitutes inflation; a sustained decline constitutes deflation. By adjusting its policy rate, the central bank seeks to keep demand in check. Major central banks, including the US Federal Reserve (Fed), the European Central Bank (ECB) and the Bank of England (BoE), have a mandate to keep inflation close to 2%.
To move inflation up or down, a central bank can adjust its benchmark policy rate, generally referred to as the interest rate. At previously announced times, it publishes a statement setting out the rate and explaining its decision to leave it unchanged, reduce it or raise it. Domestic banks then alter their savings and lending rates accordingly. These changes affect how easily savers can earn a return and businesses can borrow to invest in their operations. Substantial increases in central bank interest rates are known as monetary tightening, whereas reductions in the benchmark rate are described as monetary easing.
Political independence is common among central banks. Before taking a seat on a policy board, prospective members undergo a series of panel assessments and hearings. Individual board members typically hold particular views on controlling inflation and the monetary policy needed to achieve that aim. Those favouring very accommodative policy, with low interest rates and inexpensive borrowing to provide a substantial economic boost, while accepting inflation slightly above 2%, are described as ‘doves’. By contrast, ‘hawks’ prefer higher rates that reward saving and seek to keep inflation firmly contained, persisting until it is at or just below 2%.
Meetings are usually led by a chair or president, whose role includes building agreement between hawks and doves. If votes are evenly divided on whether policy should change, the head has the final say to prevent a 50-50 tie. Speeches by the chair, often available to follow live, set out the current policy stance and outlook. Central banks aim to advance their monetary policy without causing sharp swings in interest rates, equities or their currencies. Ahead of a policy meeting, all members communicate their positions to markets. Public comment is then prohibited from a few days before the meeting until the new policy has been announced, an interval known as the blackout period.
Conducted by the US Bureau of Labor Statistics, the JOLTS Job Openings survey helps gauge the number of unfilled positions. Each month, it gathers information from employers across retail, manufacturing and various office settings.
Find out more.Next scheduled release: Tue 30 Jun 2026 14:00
Release frequency: Every month
Consensus forecast: 7.28M
Previous reading: 7.618M
Data source: US Bureau of Labor Statistics







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


