
News & AnalysisCareer

A 2.5% rise has taken West Texas Intermediate (WTI) futures on NYMEX to around $100.50, their highest in over a month. Oil is now within reach of its almost five-month peak of $102.11.
With almost 20% of global energy supply passing through the Strait of Hormuz, Iran’s continued attacks on tankers seeking to navigate the chokepoint are heightening supply risks. The resulting threat to energy flows is driving a sharp increase in oil’s risk premium.
Two tankers were set ablaze by mines and stopped south of the Strait of Hormuz, Reuters reported, citing Iran’s revolutionary guards’ navy. The navy did not specify a date for the incident.
Over the weekend, Iran said it was ready to retaliate against US-Israel attacks and warned that it could extend the blockade to the Bab al-Mandeb Strait and the Suez Canal.
Hopes of increased energy supplies from Moscow have also been dented by Ukraine’s continuing attacks on Russian oil refineries. According to NBC News, Ukraine renewed those strikes after President Volodymyr Zelenskyy angrily accused the United States of betraying Kyiv through a “dangerous” withdrawal of support vital to its defence against Russia.
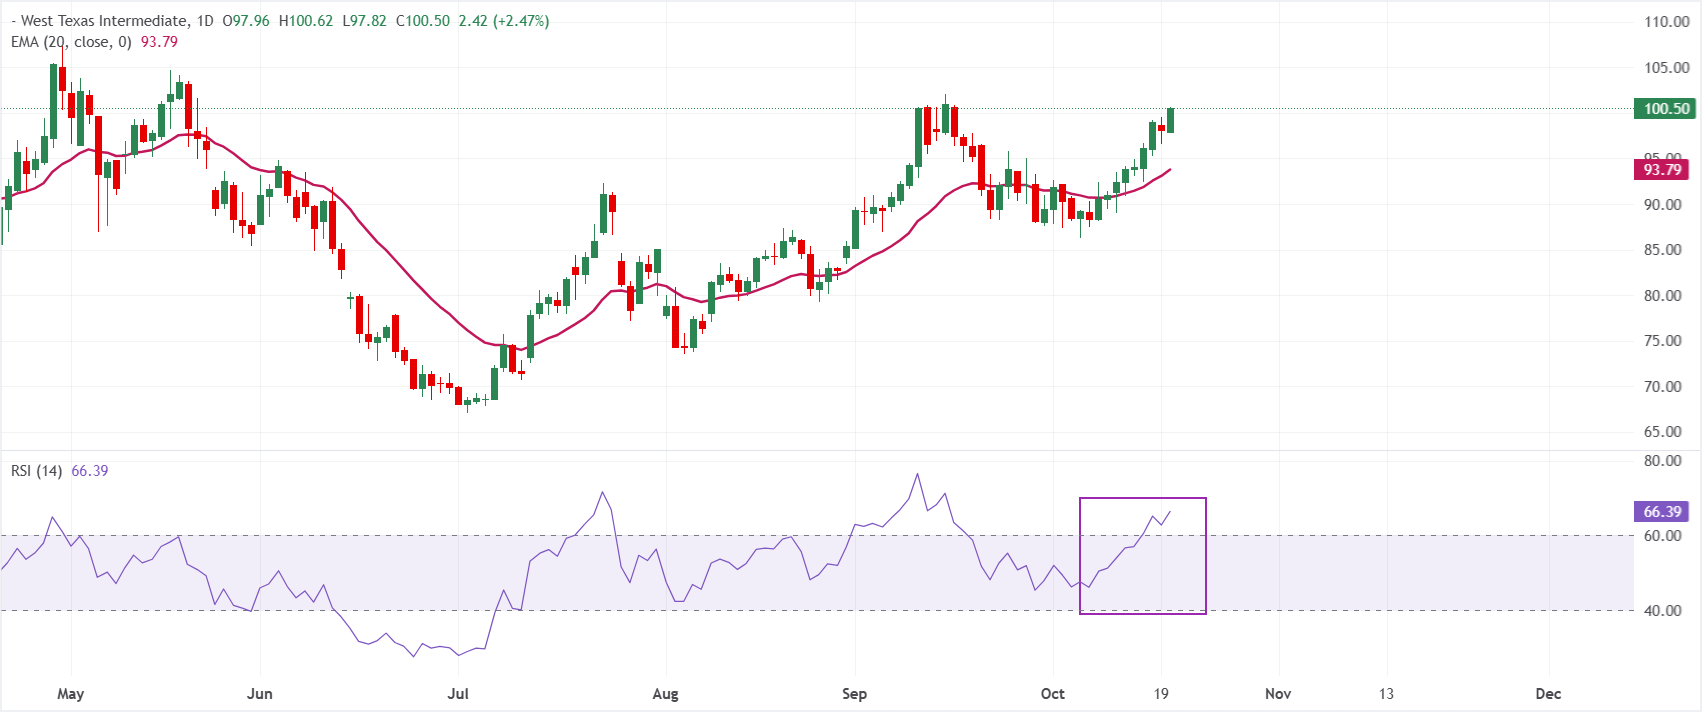
At $100.49 on the daily chart, WTI US Oil remains above its 20-day exponential moving average (EMA) of $93.79. That position supports a bullish near-term outlook and leaves the wider uptrend intact despite recent volatility. Meanwhile, the Relative Strength Index (14) stands at 66.38, in positive territory but below overbought levels. This indicates that upward momentum remains constructive, albeit increasingly stretched.
Should a corrective pullback develop, the first support lies at the 20-day EMA of $93.79, where buyers are likely to defend the existing trend. Holding above this underlying demand zone would favour buying on dips rather than aggressive selling. Any consolidation would then likely be viewed as a pause in the broader rise, rather than a reversal of the trend.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Among the crude oils traded internationally, WTI, short for West Texas Intermediate, is one of three major varieties alongside Brent and Dubai Crude. Its relatively low gravity earns it the description “light”, while its low sulphur content accounts for the term “sweet”. Regarded as a high-quality oil, it is straightforward to refine. WTI originates in the United States and is distributed through the Cushing hub, known as “The Pipeline Crossroads of the World”. As an oil-market benchmark, its price is regularly cited in the media.
Supply and demand underpin WTI Oil prices, as they do those of other assets. Stronger global growth can lift demand, whereas weaker growth can have the reverse effect. On the supply side, political instability, wars and sanctions can cause disruption and influence prices. Decisions taken by OPEC, a grouping of major oil-producing countries, are another important price driver. The US dollar also plays a role because oil is traded predominantly in that currency: a weaker dollar can make WTI crude oil more affordable, while a stronger dollar can have the opposite effect.
WTI Oil prices respond to the weekly oil inventory releases from the American Petroleum Institute (API) and the Energy Information Agency (EIA). Shifts in stockpiles reflect changes in supply and demand. A decline can signal stronger demand and lift oil prices, while a build can point to greater supply and weigh on prices. The API publishes its report each Tuesday, followed by the EIA the next day. The two sets of figures tend to be similar, coming within 1% of one another 75% of the time. As the EIA is a government agency, its data is regarded as more reliable.
At meetings held twice a year, the 12 oil-producing nations that make up OPEC (Organization of the Petroleum Exporting Countries) jointly set production quotas for member countries. These decisions frequently affect WTI Oil prices. Lower quotas can restrict supply and push prices higher; an increase in OPEC production has the reverse effect. The broader OPEC+ grouping brings in ten additional non-OPEC members, with Russia the most notable among them.







Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


