

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
160.00 in focus as yen weakens ahead of Fed speakers and US PPI
- Seven-week range ends as USD/JPY reaches its strongest level since 2 September.
- December rate rises expected from both the Fed and BoJ would preserve the interest-rate differential.
- October producer price data from Japan precede Friday's US release.
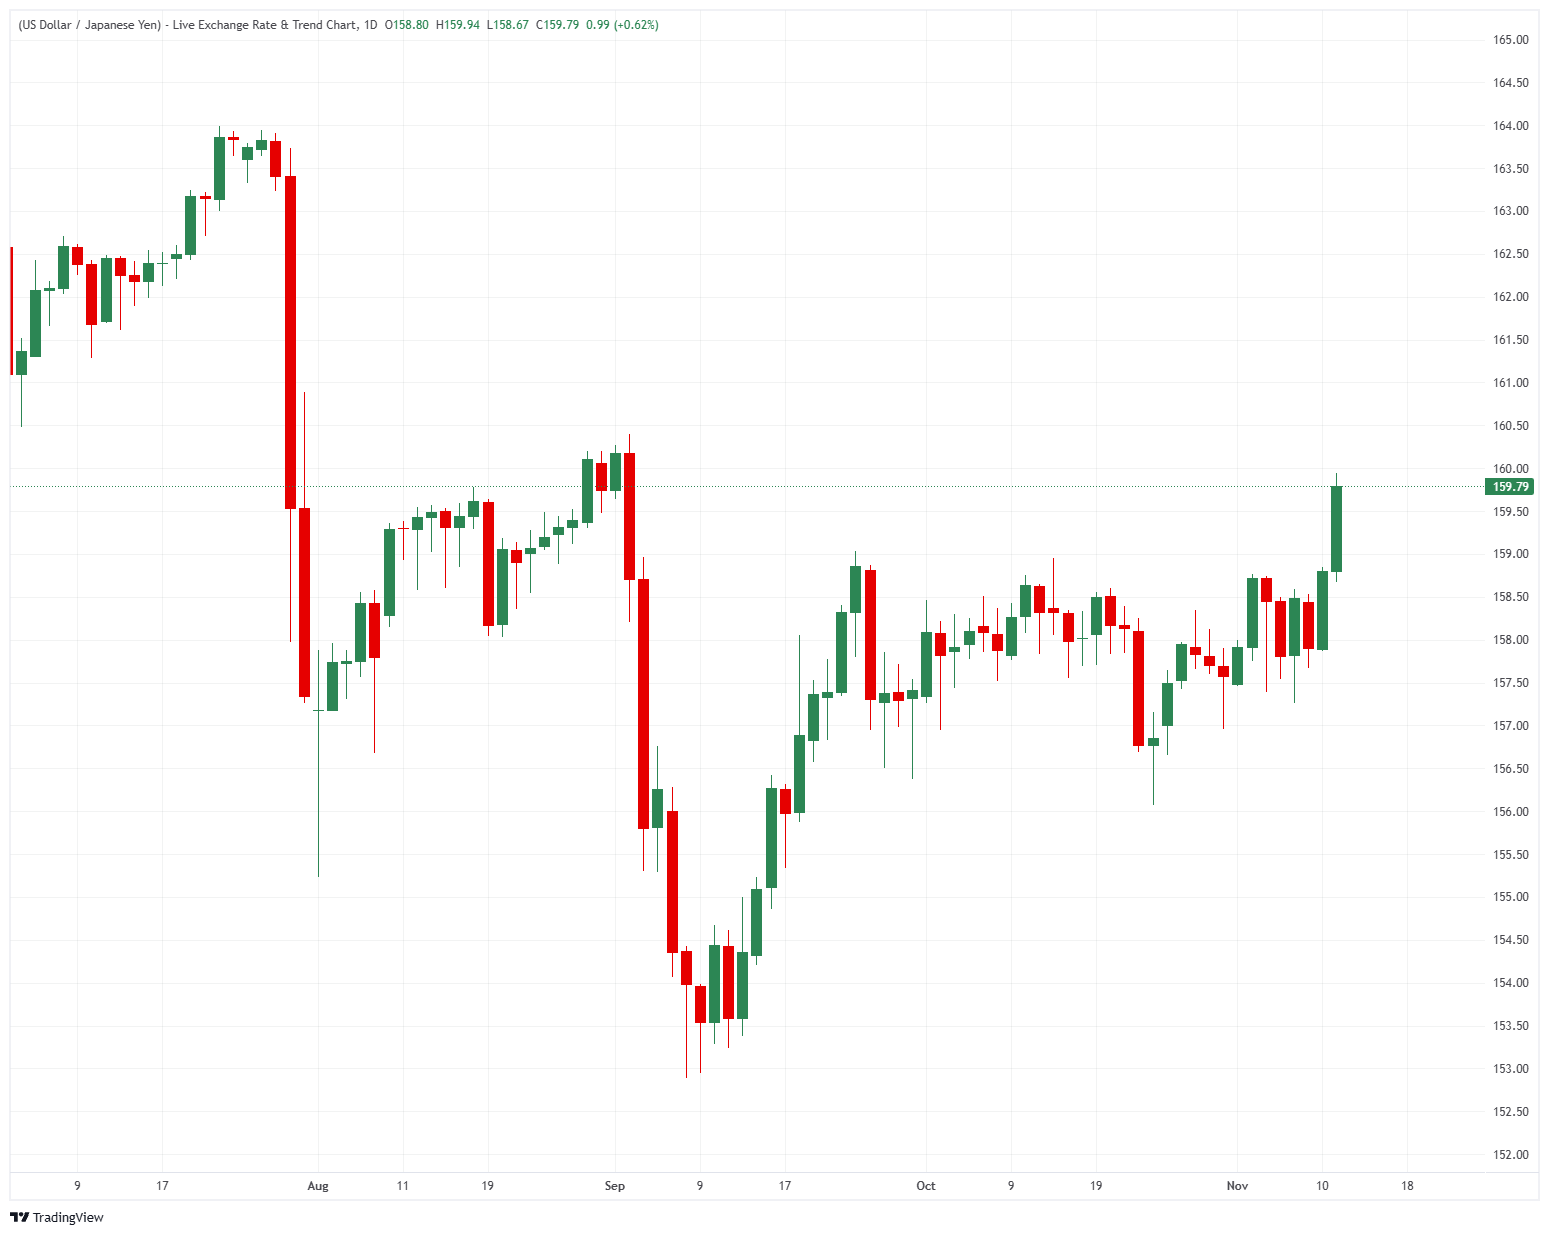
160.00 is back within reach for USD/JPY for the first time since early September. Having broken out of its seven-week range, the pair has climbed to just below that level, its highest since 2 September. It now trades slightly below the peak, towards the upper end of Wednesday's range. Fed speeches and US producer price data remain on the agenda before the weekend.
A stronger-than-forecast 0.4% increase in October's Consumer Price Index (CPI) was followed by Fed Governor Waller describing a rate rise at the 8-9 December meeting as likely. Futures put the probability of a quarter-point increase at close to 90%. At 3.75%-4.00%, the Fed's rate compares with 1.25% at the Bank of Japan (BoJ). That differential of at least two and a half points rewards investors holding Dollars rather than Yen.
Expectations also point to a BoJ rate rise. In October's 8-1 vote, BoJ board member Takata backed 1.50%; most economists expect the other members to follow at the 17-18 December meeting. If both central banks raise rates by a quarter-point nine days apart, neither the differential nor the incentive to hold Dollars instead of Yen would change.
Key data and Fed speeches
At 23:50 GMT on Wednesday, Japan releases October corporate goods prices. Third-quarter Gross Domestic Product (GDP) is then due at 23:50 GMT on Sunday. Both releases will inform the BoJ's December decision and, in turn, the Japanese component of the rate differential.
Thursday brings US jobless claims at 13:30 GMT, with a forecast of 195K compared with 189K. At 14:00 GMT, Cleveland Fed President Hammack begins a series of six Fed speeches that day. Friday's October US Producer Price Index (PPI) is due at the same hour; forecasts call for a 0.4% increase after September's 1.3%. With a quarter-point Fed increase already priced in, the claims and PPI figures will help determine whether a half-point move is possible.
160.00 in focus after range breakout
USD/JPY's breakout clears the 156.00-159.00 band in place since late September. The pair has now retraced almost the entire decline from the 2 September high near 160.50 to September's low around 153.00. On the two previous occasions it exceeded 160.00, in late July and early September, a fall of more than five Yen followed within a week.
Daily price chart: USD/JPY
Japanese Yen: frequently asked questions
Among the world's most actively traded currencies, the Japanese Yen (JPY) broadly reflects Japan's economic performance. More specific influences include Bank of Japan policy, the yield differential between Japanese and US bonds, and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions an important influence on the Yen. Direct intervention in foreign exchange markets has occurred occasionally, usually with the aim of weakening the currency. Political concerns among Japan's main trading partners, however, discourage frequent intervention. Between 2013 and 2024, the BoJ's ultra-loose monetary policy weakened the Yen against its major peers as the policy gap with other leading central banks widened. The more recent gradual withdrawal of that policy has provided some support for the currency.
By maintaining ultra-loose monetary policy over the past decade, the BoJ moved increasingly out of step with other central banks, particularly the US Federal Reserve. The resulting widening in the yield differential between 10-year US and Japanese bonds favoured the US Dollar over the Japanese Yen. That differential is now narrowing following the BoJ's 2024 decision to gradually withdraw its ultra-loose policy, alongside interest-rate cuts by other major central banks.
Investors often regard the Japanese Yen as a safe-haven asset. During periods of market stress, its perceived reliability and stability make them more likely to place funds in the currency. As a result, market turbulence is likely to lift the Yen against currencies viewed as riskier investments.
POPULAR ARTICLES
10.68 test for Australian Dollar as Fed hawks propel USD to 19-month high2160.00: Yen stalls as Tokyo issues warning before Japan’s growth data318-month low: Euro awaits Eurozone growth and US price data4Three-day slide: Pound awaits upcoming UK jobs and inflation data5$2,000 breached: Ethereum price forecast as ETH drops on Jensen Huang's resignation from Nvidia6Banxico rate cut sends wrong signal on inflation, Heath warns7Bitcoin and crypto market losses deepen after Jensen Huang's resignation8$3,850 area: gold tumbles to one-year low as Fed hawks take control9Fed’s Daly sees further rate hikes ahead, warning AI is fuelling inflation


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved