

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Bitcoin rally prospects if the Federal Reserve maintains higher-for-longer rates
The US Federal Reserve (Fed) raised interest rates in September after a three-year gap. The move to contain alarming inflation figures has revived concerns that tighter liquidity could weigh on Bitcoin (BTC), echoing the 2022 bear market.
Behind those inflation concerns is a rise in Brent Oil prices following the US-Iran war, which began on February 28. The conflict continues to disrupt shipments through the Strait of Hormuz, directly influencing global markets and investor sentiment.
Rising inflation forces the Fed to increase interest rates, draining market liquidity and dampening demand among consumers and producers alike. Investors consequently become less willing to take risks, putting pressure on equities, crypto and other high-risk assets.
Markets have largely priced in the war. However, the prospect of further Fed rate increases resembling the 2022 cycle leaves an open question: could Bitcoin enter another bear cycle?
March 2022 Revisited: Geopolitical Risks Raise Concerns
A repeat of Bitcoin’s 2022 bear market is troubling the broader market. During that period, Brent Crude Oil climbed above $130 per barrel, leading the Fed to increase the fed funds rate over several months.
On September 16, the US Fed was forced to deliver its first interest-rate increase in three years, lifting rates by a quarter point and fuelling market unease. That took the fed funds target range to 3.75% to 4.00%. September’s US Consumer Price Index (CPI) reached 3.7% YoY, compared with 3.4% in August, as monthly inflation quickened to 0.6%.
The Fed subsequently left its benchmark rate on hold on October 28. However, the 10-2 decision implied that additional increases were ahead. If price pressures persist, financial conditions could remain restrictive, leaving less capital available for speculative assets.
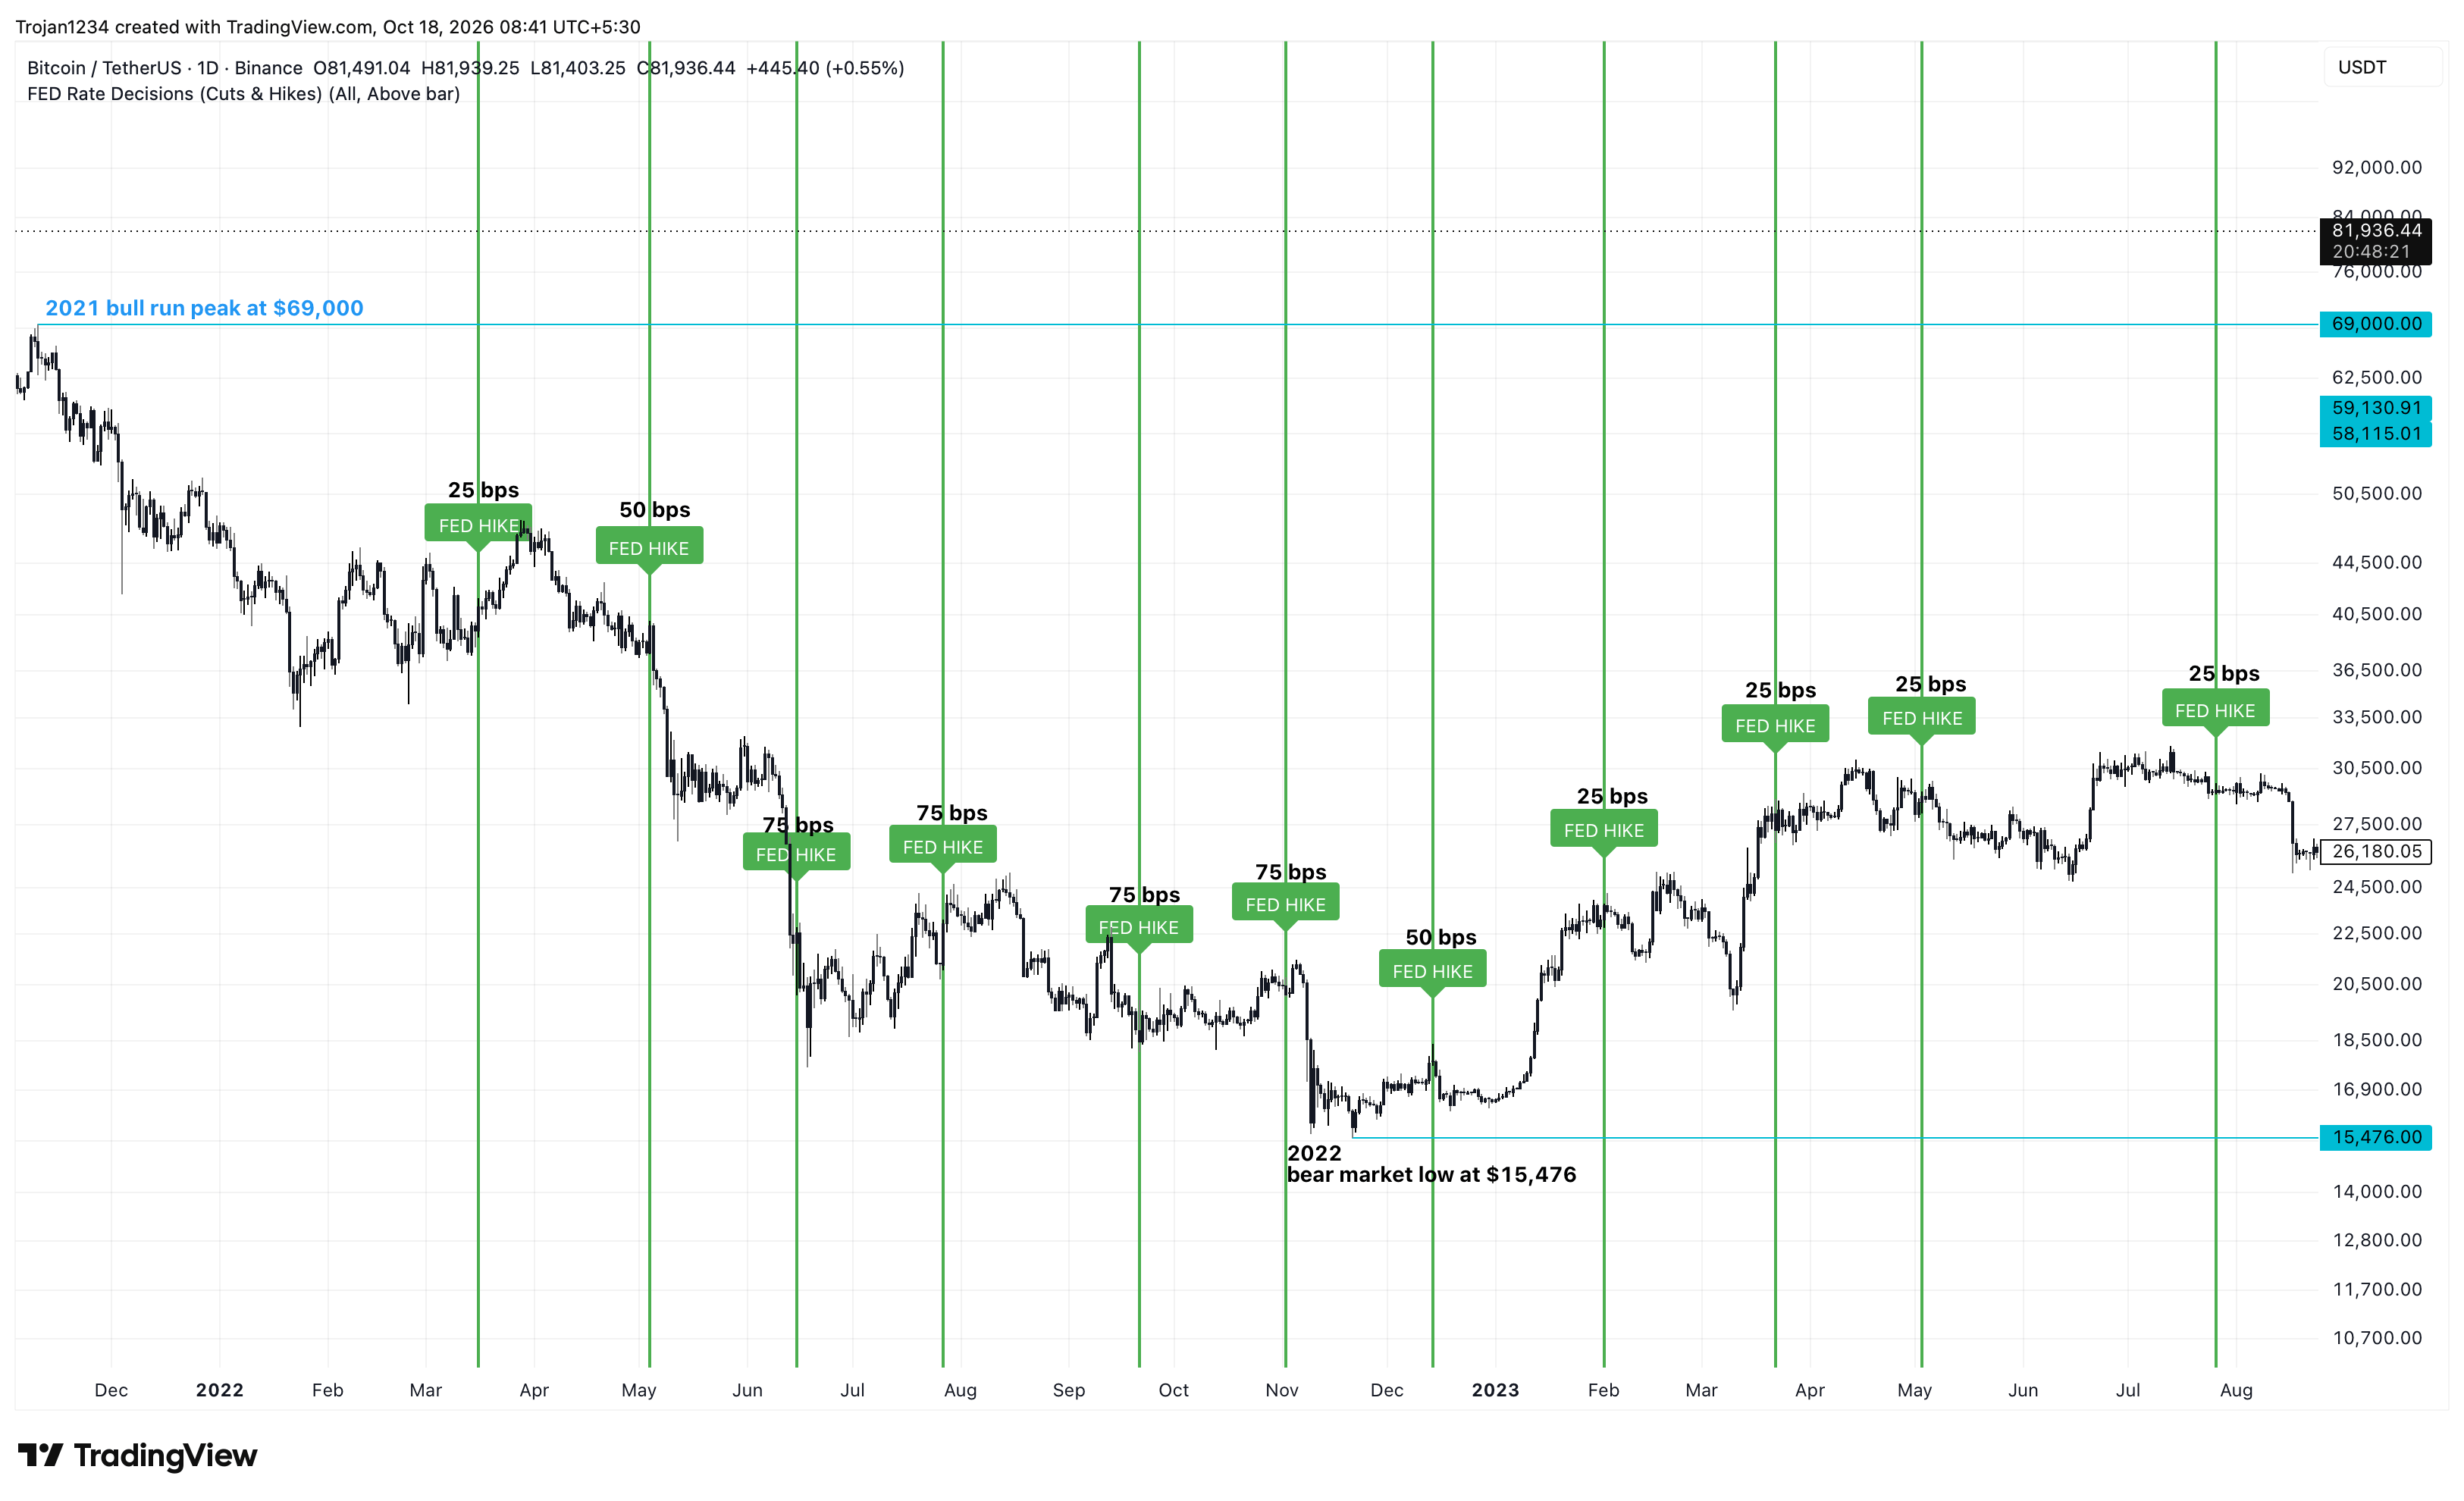
Bitcoin’s relationship with rate increases was far from straightforward during the 2022-23 cycle. As the Fed lifted rates from near zero to 4.25%–4.50%, BTC slid nearly 78%, from about $69,000 in November 2021 to approximately $15,476 in November 2022.
Monetary tightening gathered pace in 2022 through four consecutive 75-basis-point increases, bookended by three smaller hikes. Selling pressure intensified as those increases coincided with the collapse of the Terra ecosystem, failures among crypto lenders and the FTX bankruptcy case.
During 2023, however, Bitcoin rebounded despite further, slower-paced Fed rate increases that ultimately took rates to 5.25%–5.50% in July. That rebound illustrates how expectations, market positioning and demand can carry more weight than the immediate effects of higher rates.
Institutional Buying Offers a Potential Inflation Counterweight
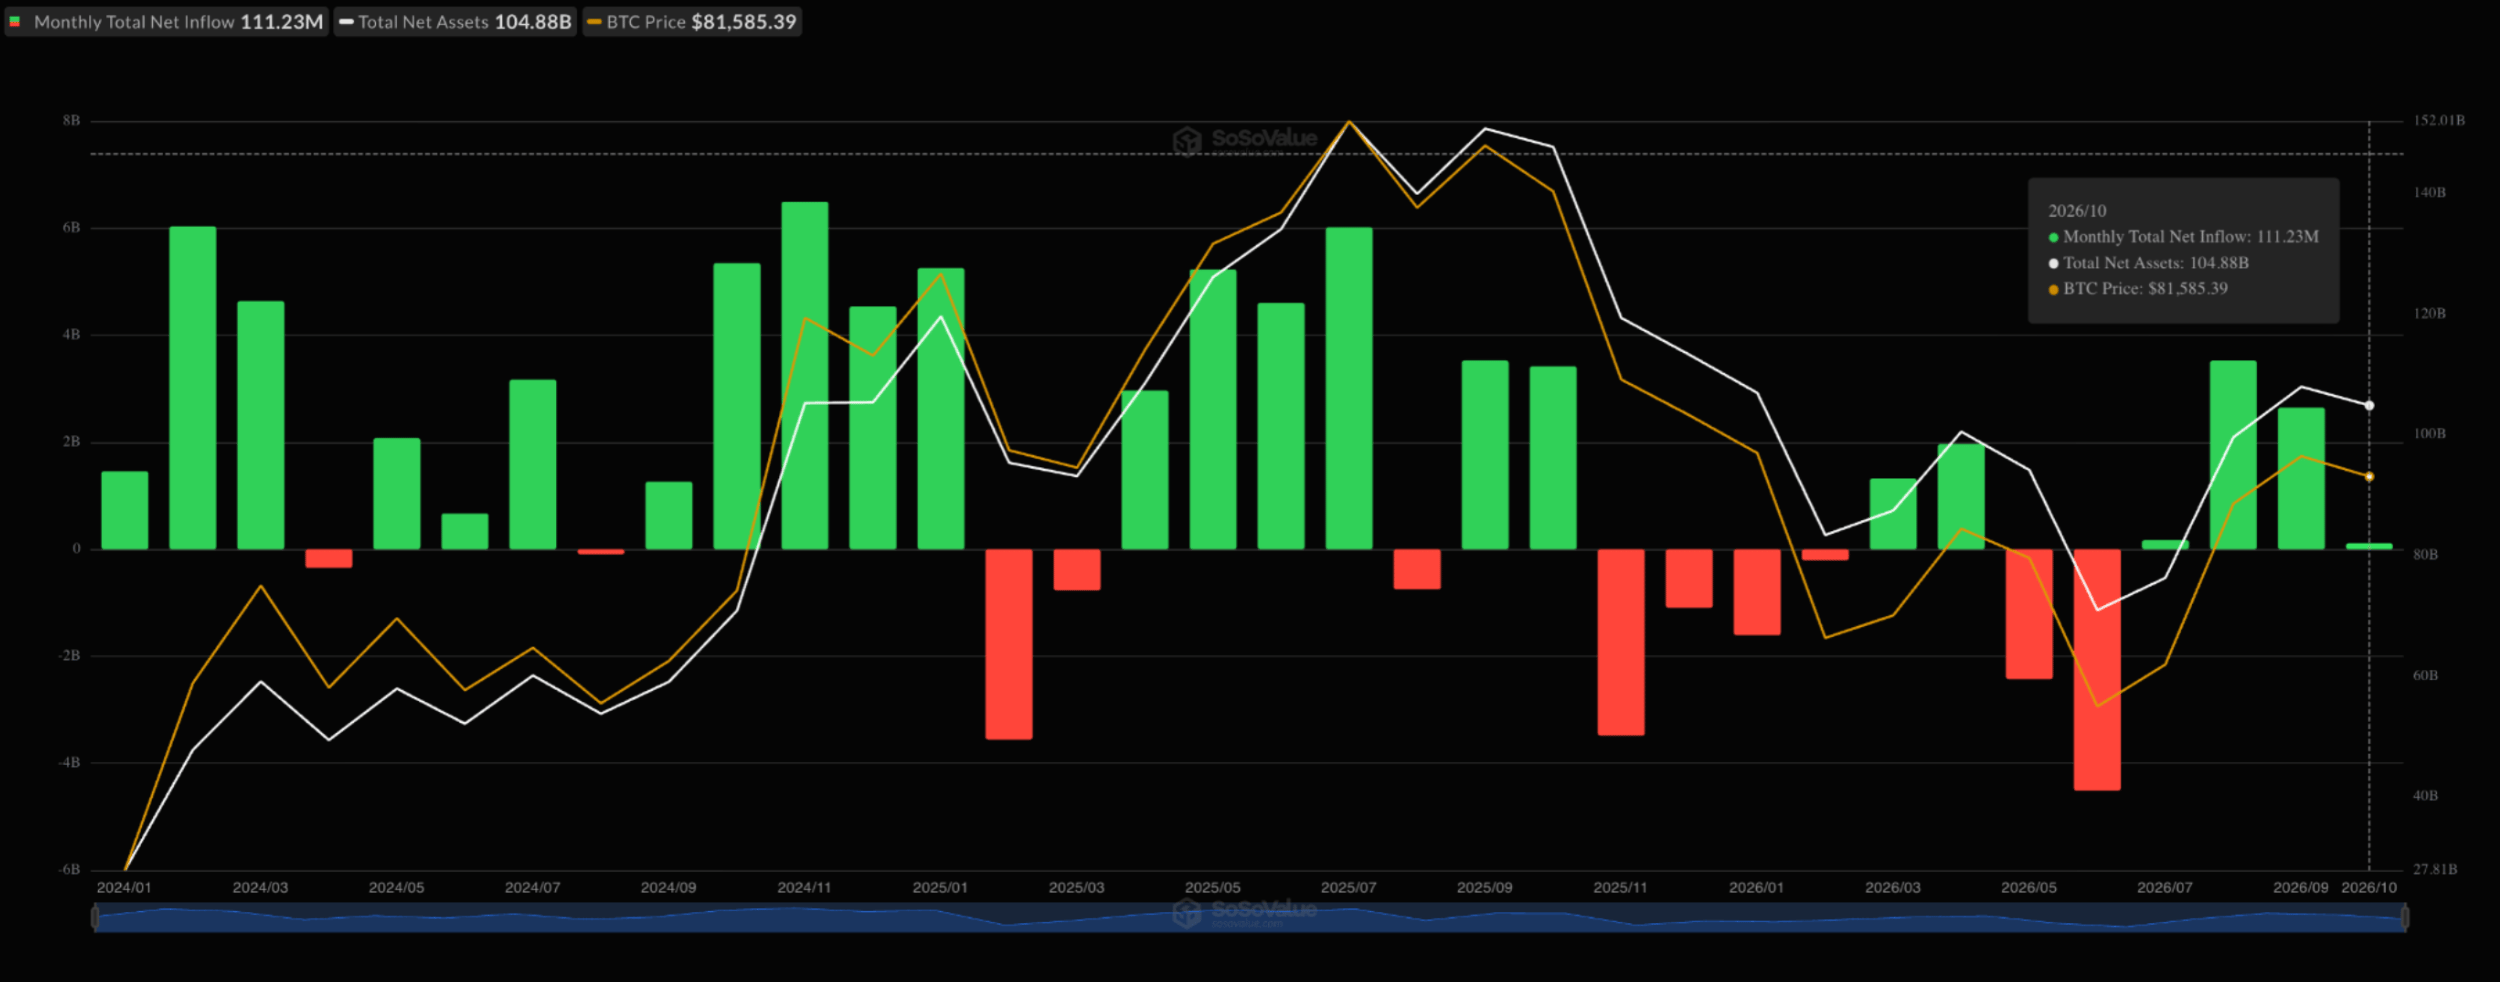
Spot Bitcoin Exchange-Traded Funds (ETFs) and corporate BTC treasuries have become significant channels for institutional demand, giving Bitcoin a different market structure in 2026 from that of the 2022 bear market. As FXStreet previously reported, Bitcoin’s four-year cycle points towards a bullish reversal ahead in 2026.
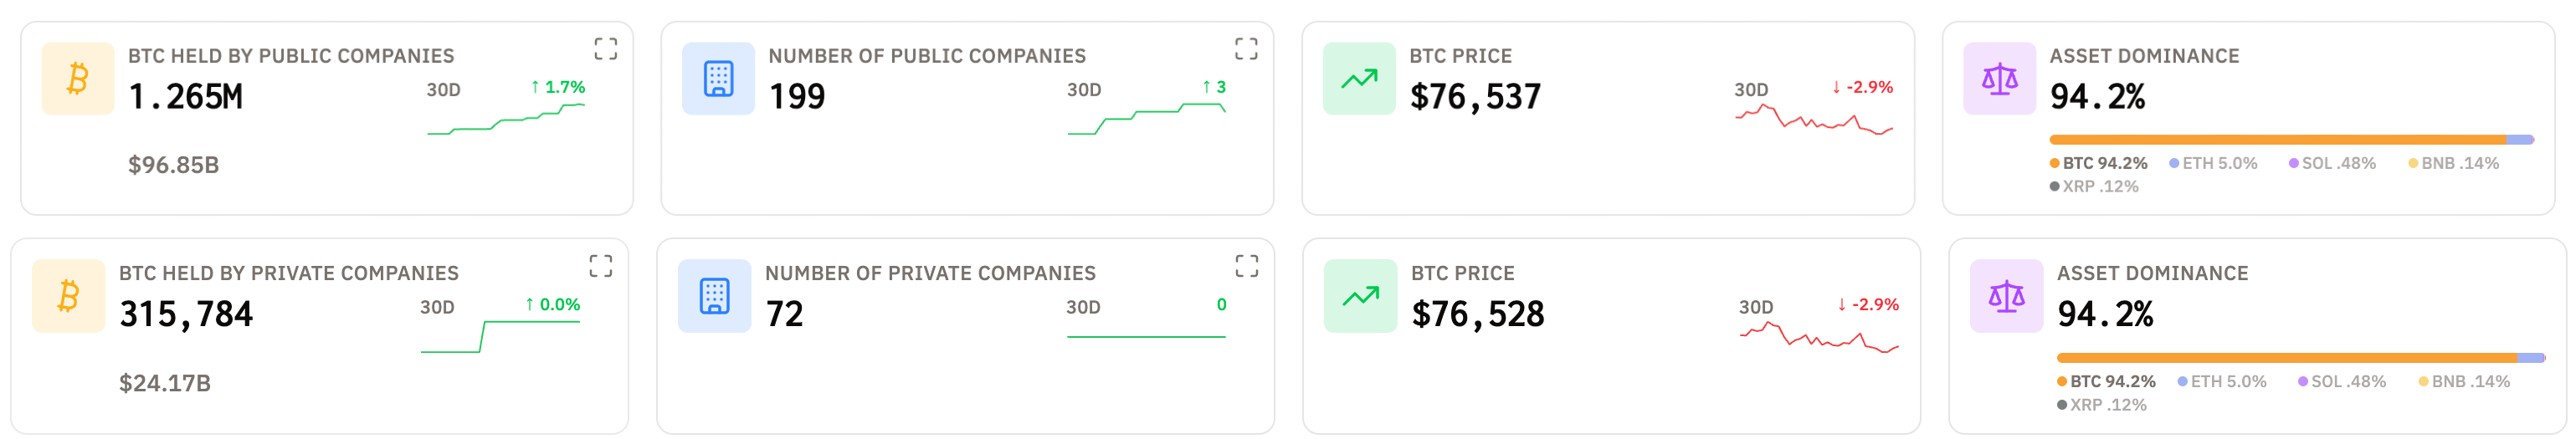
Total net flows into US spot Bitcoin ETFs stand at $104.9 billion as of October 28. Since their January 2024 inception, the funds have registered 22 months of inflows and 11 months of outflows. Private companies hold $103.7 billion in Bitcoin, while public companies hold $22.8 billion. These sizeable ETF and corporate holdings underpin demand, with some purchases funded by equity issuance, debt or preferred securities.
A sustained Bitcoin correction could nevertheless erode these holdings, as illustrated by Strategy’s recent sale of some BTC to build cash reserves. Should another series of rate increases constrain institutional liquidity, accumulation could slow, or these holdings could become a source of supply.
Bitcoin Resilience, ETFs and AI Risks: WisdomTree’s Director of Digital Assets Research Gives His Outlook
With broader market conditions still uncertain, I spoke exclusively to Dovile Silenskyte, Director of Digital Assets Research at WisdomTree, for FXStreet and asked for his outlook on Bitcoin.
- Late 2026 could mark the end of Bitcoin’s bear market, according to its four-year cycle. Yet Fed rates and geopolitical risks continue to put the market under downward pressure. Can corporate DATs, government-level holdings and Bitcoin spot exchange-traded funds (ETFs) counter those macroeconomic risks?
Demand now reaches Bitcoin through different routes, distinguishing this cycle from earlier ones. Corporate balance sheets, established investment portfolios and sovereign strategies provide channels that could improve its ability to withstand macroeconomic pressure.
Investors can use familiar market infrastructure to allocate capital through spot ETFs. Longer-term strategic demand can come from corporate treasuries, while sovereign holdings could lessen potential selling pressure if they are retained. With Bitcoin’s supply limited, persistent buying and holding through these routes could underpin prices, despite interest-rate uncertainty and geopolitical tensions dampening risk appetite.
Cyclical risks remain despite that structural support. Corporate purchases still depend on financing conditions, and ETF flows can turn negative. Expanding Bitcoin’s investor base creates more potential demand channels when sentiment recovers, but it does not establish a price floor.
A bottom in late 2026 should therefore be treated as a possible scenario rather than a reliable forecast. Institutional adoption [combined] with improving global liquidity offers a stronger foundation for the bullish case. Lower real yields and easier monetary conditions could allow Bitcoin to draw support from both structural demand and a more favourable macroeconomic backdrop.
- $500 billion in AI-related debt issuance is expected in 2026, fuelling concerns about growing strain on bond and credit markets. Could tighter financial conditions resulting from the AI investment boom draw capital away from speculative assets and put Bitcoin under pressure?
Competition for capital between AI investment and Bitcoin is possible in the short term. Their expansion is not necessarily mutually exclusive, however: investors can finance the AI buildout and raise their Bitcoin exposure at the same time.
Financing conditions present the most immediate risk. If investor demand cannot keep pace with debt supply, substantial borrowing for AI infrastructure could lift financing costs. Still, increased issuance does not inevitably tighten financial conditions, since the proceeds support investment and circulate through the economy. The key questions are whether markets can absorb that debt and whether project returns justify the borrowing.
Productivity gains represent the more substantial longer-term opportunity. By improving efficiency, AI could raise output and moderate inflationary pressure, creating a more favourable investment environment that also benefits Bitcoin. This is a plausible scenario, not an assured return from AI expenditure.
Different fundamentals also underpin Bitcoin’s investment case. Rather than providing exposure to corporate profits or an issuer’s debt-repayment capacity, it gives investors access to a scarce digital asset. Its attraction thus reaches beyond the technology spending cycle.
Bitcoin’s Institutional Demand Faces the Liquidity Test
Despite the broader market uncertainty, Bitcoin remains resilient above key support levels, offering a counterpoint to an entirely bearish assessment. Institutional demand distinguishes the next potential rate-hike cycle from earlier ones and could underpin a sustainable move higher.
That said, these funds may struggle to provide support through an extended period of rate increases. Markets anticipate another 25-basis-point rise before the end of 2026.
Whether Bitcoin’s institutionalisation can absorb the next liquidity shock without a repeat of previous cycles’ extreme drawdowns will therefore be the decisive test.
POPULAR ARTICLES
1Near $51.00: Silver price forecast as XAG/USD tumbles to new low since November2Easing oil pressure fails to halt Canadian Dollar gains31.1200 reclaimed: Euro extends post-ECB rebound from YTD low against weak USD4Hawkish BoE outlook and subdued US Dollar lift British Pound5Bitcoin rally prospects if the Federal Reserve maintains higher-for-longer rates66.7138: PBOC sets USD/CNY reference rate, compared with 6.7147 previously7New Zealand Dollar finds few buyers as USD weakness caps losses86% slide in XRP despite Ripple's projected $900M annualised revenue9Below $102.00: WTI holds steady as hopes for diplomacy counter Middle East supply risks


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved