

What is keeping the British Pound tied to fiscal risks as the BoE looks set to keep rates steady?
The British Pound (GBP) remains tightly bound to the UK’s evolving inflation outlook and impending fiscal policy choices. Although the Bank of England (BoE) maintained its benchmark policy rate at 3.75% in June, headline inflation remains above the official target, keeping investors highly sensitive to any upside price shocks.
While a recent stabilizing trend in global energy markets has balanced broader commodity risks, analysts warn that the timing of fresh spending initiatives will act as the primary driver for Sterling over the coming months.

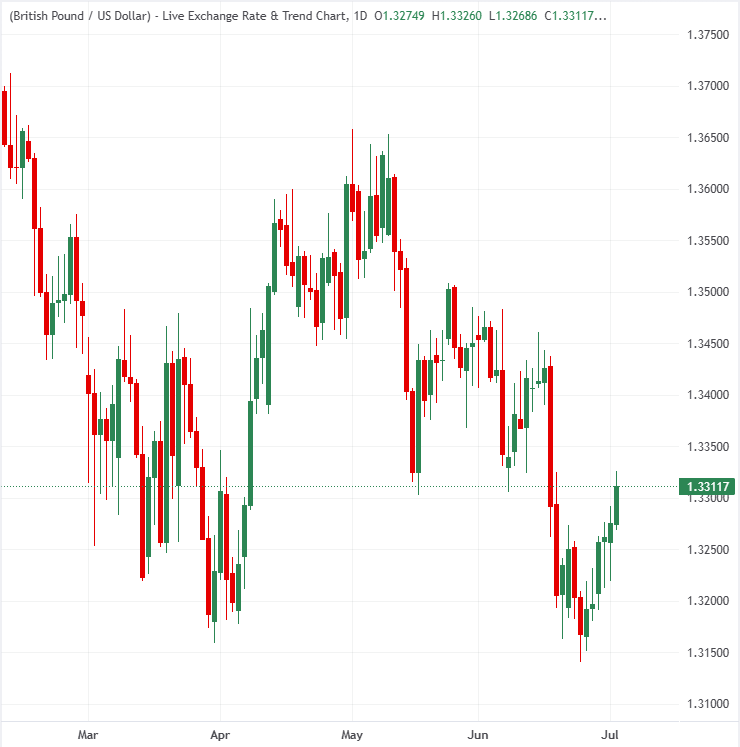
Timing of fiscal expansion likely to dictate timing of any further shock
Macro strategists at ING emphasize that the market's reaction to upcoming government spending depends entirely on how quickly those funds are injected into the economy.
In the current environment, an immediate fiscal push risks delaying the central bank’s return to its 2% price stability target. Consequently, front-loaded spending programs are expected to apply substantial upward pressure on UK interest rates, whereas long-term out-year commitments will likely receive greater leeway from bond investors.
Sterling markets remain sensitive to inflation risks, which means any near-term fiscal spending initiatives would have a significant upward impact on GBP rates. The impact of spending further out in the future should be more muted.
Stabilizing energy costs allow the Bank of England to pause
The research team at HSBC presents a more balanced evaluation of regional inflation threats. They point out that a fresh interim peace agreement between the US and Iran has reduced the chances of secondary energy price surges. While consumer confidence remains soft and domestic wage growth persists, a cap on global Oil prices should allow the BoE to stand pat for the remainder of 2026.
With energy prices stabilising following the US-Iran interim peace agreement, inflation risks are now more balanced. Accordingly, we have revised our rate forecast to reflect no further hikes in 2026.
Banks project Pound to trade range-bound
These banks collectively anticipate a range-bound near-term trend for the British Pound, tethered directly to the execution of domestic budgets.
ING notes that with terminal interest rates still priced near 4%, the fixed-income market is highly reactive to structural policy changes, meaning any immediate defense or social spending will abruptly lift borrowing costs. On the other side, HSBC suggests that a peak in inflation at 3.25% in Q4 will effectively block the necessity for further monetary tightening, concluding that rates will hold steady at 3.75% for the year.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor.)













