

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Euro looks vulnerable near yearly low as Fed-ECB policy takes centre stage
- Vulnerable ahead of the Fed’s policy announcement, the Euro hovers near its yearly low of 1.1113 against the US Dollar.
- Pressure on the Euro persists amid French fiscal risks and elevated oil prices.
- Interest rates are expected to remain unchanged at both the Fed and the ECB.
Under pressure from growing unease in French bond markets and higher oil prices, the Euro (EUR) remains near its yearly low of 1.1113 against the US Dollar (USD) in Wednesday’s European session. These concerns continue to weigh on the Euro, keeping the major currency pair on the defensive.
Can the Euro withstand wider French spreads as confidence revisits 2022 lows?
Domestic political tensions are becoming more evident in French markets, according to Scotiabank strategists, who note that “French bonds … underperforming, nudging the spread over 10Y bunds back up to 161bps.” Highlighting the sharp deterioration in sentiment, they add that “French Consumer Confidence plunged to 80 in October, equaling the low seen in 2022, reflecting recent pollical tensions and social unrest.”
Fears of further disruption to energy supplies have also gathered pace following a drone attack by Iran-backed Houthis on Saudi Arabia’s biggest oil facility, driving oil prices higher at a faster pace.
A military spokesperson for the Iran-aligned Houthis said on Tuesday that the group had struck Saudi Arabia’s biggest oil refinery with a missile, stepping up attacks on the world’s second-largest crude producer. According to Reuters, Saudi authorities did not immediately confirm the strike on the facility, which has a capacity of 550,000 barrels per day.
Attention for the Euro now turns to Thursday’s monetary policy announcement from the European Central Bank and Friday’s preliminary German Harmonized Index of Consumer Prices (HICP) figures for October. Both will be key triggers, with the ECB expected to leave interest rates unchanged.
For the US Dollar, the focus is on the Federal Reserve’s (Fed) monetary policy announcement, due at 18:00 GMT.
Will the Fed signal further tightening as Danske Bank forecasts December and March hikes?
For US markets, Danske Bank analysts identify “the main event of the week is this evening's FOMC rate decision and the following press conference,” adding that they “expect the Fed to keep policy rates unchanged, in line with consensus, while markets price in a 10% probability of a hike.”
Explaining why they “expect 2-3 dissenting votes in favour of a hike,” the bank’s analysts note that “most central FOMC members have signalled that they can wait until December before hiking again, although a few see more urgency,” supporting their expectation of some dissent.
Danske Bank maintains its assessment that it “still see[s] a need for further tightening”, while noting that “all eyes are on Fed, which are expected to leave rates unchanged.” The bank’s base case is for Chair Powell “to reiterate his firm commitment to bringing inflation back to target,” and it retains its forecast for “two more hikes, in December and March.”
EUR/USD Technical Analysis: Can Bearish Pressure Ease?
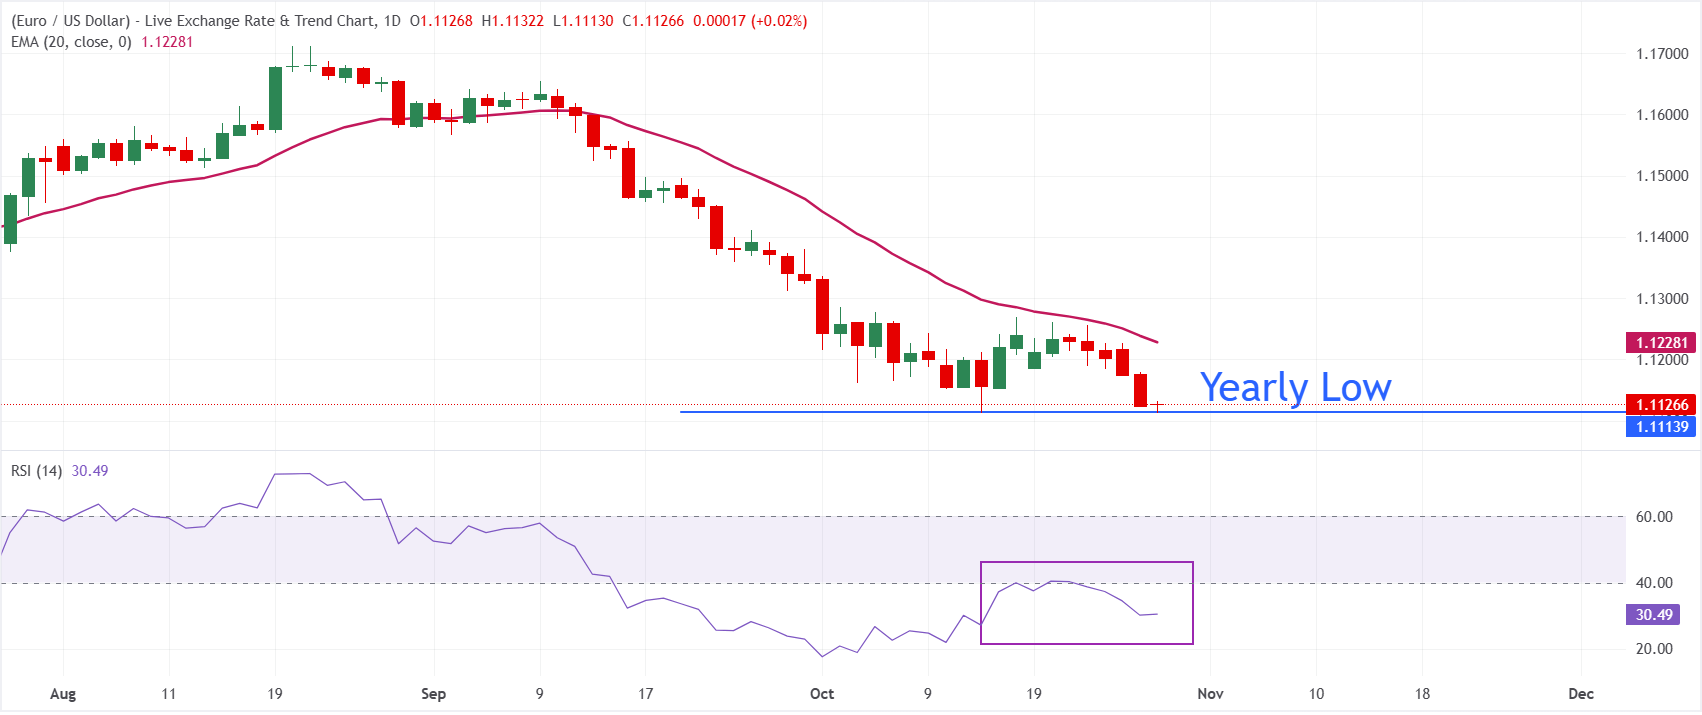
The daily chart retains a bearish bias for EUR/USD, which trades at 1.1126 below its 20-day exponential moving average (EMA) of 1.1228. This dynamic resistance continues to cap the pair and maintain downward pressure. A Relative Strength Index (RSI) reading near 30 also suggests that downside momentum remains in control. However, the approach towards oversold territory could temper near-term selling rather than bring about a reversal in the trend.
A daily close above the 20-day EMA, the first resistance around 1.1228, would be required to relieve the prevailing bearish pressure and indicate a more durable corrective rebound. Before that hurdle is cleared, any gains are likely to be treated as corrections within the broader downtrend. With no nearby structural support evident on the chart, renewed selling momentum could leave the pair exposed to fresh lows.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Data in Focus
Fed Decision on Interest Rates
At eight pre-scheduled meetings each year, the Federal Reserve (Fed) reviews monetary policy and decides on interest rates. Keeping inflation at 2% and maintaining full employment are its two mandates. To pursue these objectives, it primarily sets the rates at which it lends to banks and at which banks lend to one another. A rate increase tends to support the US Dollar (USD) by drawing in more foreign capital. Conversely, a rate cut tends to weaken the USD as capital moves to countries offering better returns. When rates stay unchanged, the focus shifts to the wording of the Federal Open Market Committee (FOMC) statement: whether its tone is hawkish, pointing to expectations of higher interest rates ahead, or dovish, indicating expectations of lower rates.
Continue reading.Upcoming release: Wed 28 October 2026 18:00
Release frequency: Non-periodic
Consensus estimate: 4%
Previous reading: 4%
Data source: Federal Reserve
POPULAR ARTICLES
1Iran: We maintain our policy of no flexibility on nuclear issue2Crypto Today: Bitcoin, Ethereum, XRP rebound as Fed decision approaches3Czech Koruna: Why political tensions are pushing up the risk premium – Commerzbank4Pi Network Price Forecast: Why Is PI Stalling as Core Team Expands Investment Fund to Axis Robotics?5New Zealand Dollar: Are risks of losses against the US Dollar mounting? – Societe Generale6Euro: Is slower lending putting key support against US Dollar at risk? - ING7UK budget in focus as British Pound pares losses but stays below 1.33008Will the BoC raise interest rates to 2.50% as expected?9Silver price today: FXStreet data shows a decline
LIVE QUOTES

ALL ABOUT OIL
5 Best Oil Trading Platforms 2026 (Brent and WTI)
Iran War and the Global Economy in 2026: Oil, Inflation, Trade and Markets
Should You Still Invest in Oil in 2026?
WTI vs Brent Crude
Gold to Oil Ratio: How does the Iran War affect Gold Prices?
Top 10 Most Traded Commodities in India & The Best Commodity to Trade
What is WTI Oil: Importance, Purpose, How To Trade
Trading Brent Crude Oil: A Comprehensive Guide
How to Trade Oil in India: Steps, Markets and Risks
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved