

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
US PPI in focus as British Pound’s losing run against US Dollar continues
- 1.3227 is in sight as the British Pound extends its decline against the US Dollar on Friday.
- Persistent US inflation and a hawkish Fed outlook continue to underpin the US Dollar, according to NBC.
- US PPI figures, alongside UK employment and CPI releases, are next on investors’ radar.
GBP/USD retreats to near 1.3227. Friday marks the fourth consecutive trading day of losses for the British Pound (GBP) against the US Dollar (USD). Expectations that the Federal Reserve (Fed) will accelerate its monetary tightening cycle continue to drive the US Dollar’s outperformance.
Thursday’s 19-month high of 103.24 remains within reach for the US Dollar Index (DXY) at the time of writing. The index tracks the Greenback against six major currencies.
Inflation and Fed tightening outlook sustain Dollar’s safe-haven appeal
Persistent price pressures and policy expectations remain key supports for the Dollar, according to strategists at National Bank of Canada (NBC), who say it “remains supported by persistent inflation and the prospect of further Fed tightening.” In their assessment, “following October’s pause, another firm Consumer Price Index (CPI) report reinforces our expectation for tighter policy before year-end,” while a “deterioration in global risk appetite could provide further support through safe-haven demand.”
Released on Tuesday, the October US CPI report put monthly headline inflation at 0.4% and core inflation at 0.3%. Both increases exceeded expectations.
Ahead of the US CPI release, Fed Governor Christopher Waller warned that “half-point Fed rate hike may be needed in December, if October core CPI inflation comes in around 0.3% or higher.”
Waller’s hawkish message lifts expectations for Fed rate hikes
A 9/10 FXS Speechtracker score placed Fed Governor Waller well above his historical average of 7.3/10, highlighting an unusually strong preference for tighter policy. He explicitly left open a half-point Fed rate hike in December if core CPI reaches 0.3% or higher, while backing a quarter-point increase even if inflation data improve. That position indicates a clear inclination towards further tightening, with inflation considered “too high” and recent figures described as “bad.” Broad-based price gains, sustained producer and energy price pressures, and the need to raise real interest rates strengthen the view that policy is not yet sufficiently restrictive. Sharp equity price swings carry limited weight in that assessment.
An increase of 3.17 points took the FXS Fed Sentiment Index to 145.50, leaving it firmly in hawkish territory and aligned with the high FXS Speechtracker score. The shift points to a materially tighter perceived Fed stance. As markets assign a greater probability to December rate hikes, this is likely to support the Dollar and maintain pressure on rate-sensitive assets.
October US Producer Price Index (PPI) figures are due at 13:30 GMT later in the day and will be a focus for investors.
For the British currency, attention is turning to next week’s United Kingdom (UK) releases: labour market figures covering the three months ending September and Consumer Price Index (CPI) data for October.
GBP/USD Technical Outlook
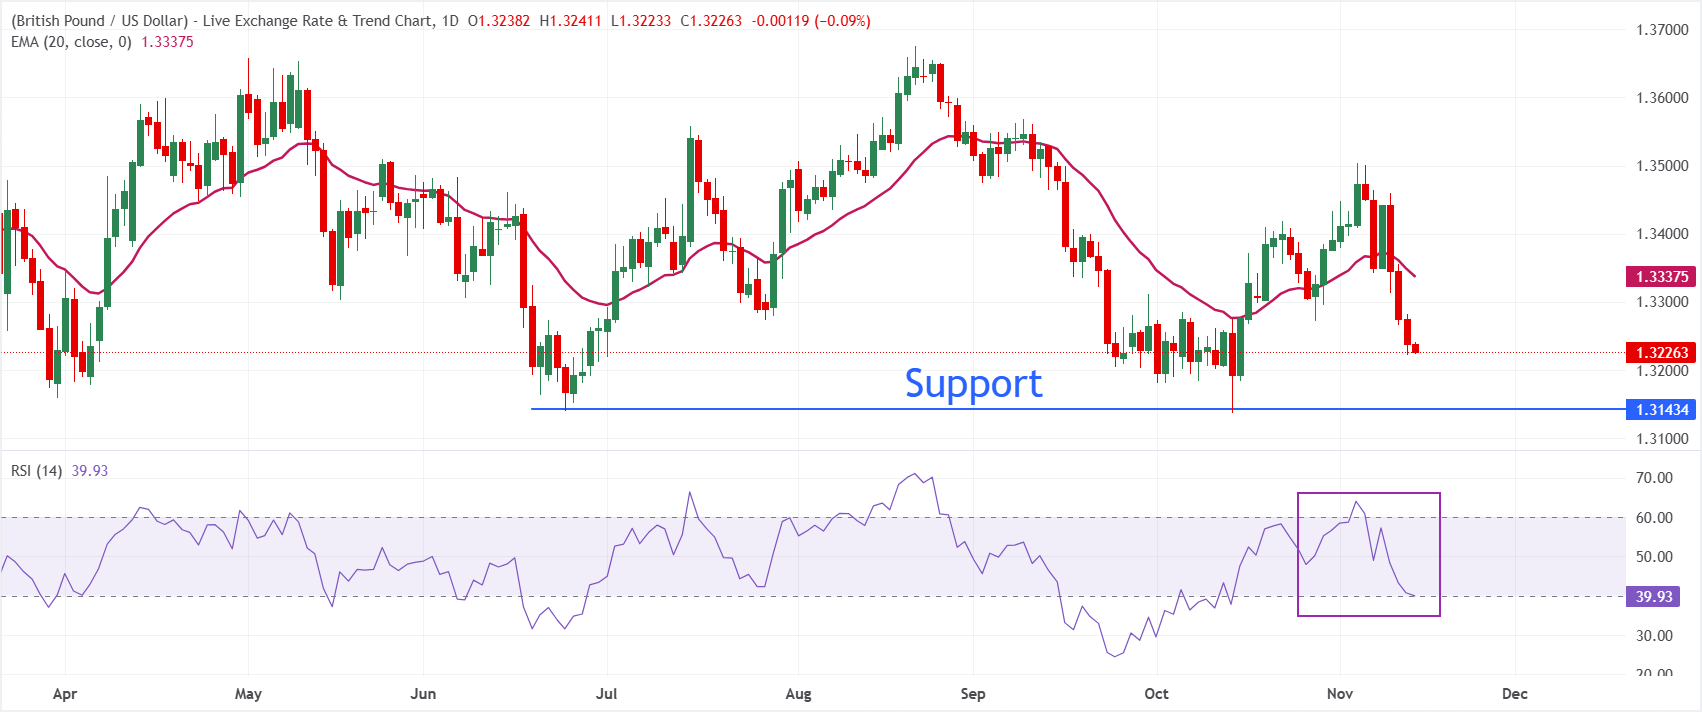
At 1.3226 on the daily chart, GBP/USD maintains a bearish short-term outlook. Spot trades beneath the 20-period exponential moving average (EMA) of 1.3337, its immediate overhead resistance. A Relative Strength Index (RSI) reading of 39.9, below the neutral 50 threshold, suggests selling pressure remains dominant, although the pair is not at oversold extremes.
The first upside hurdle is the 20-day EMA at 1.3337. A daily close above it would be required to temper the bearish outlook and create scope for a more durable recovery. Without that break, further losses remain a risk. Traders are likely to sell rebounds for as long as momentum stays below the midline.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Data Release
Monthly Producer Price Index (MoM)
Published by the Bureau of Labor statistics, Department of Labor, the Producer Price Index tracks average price changes in US primary markets for commodities produced at all stages of processing. Movements in the PPI are closely monitored as a gauge of commodity inflation. A high reading is generally regarded as positive (or bullish) for the USD; a low reading is viewed as negative (or bearish).
Continue reading.Next publication: Fri 13 Nov 2026 13:30
Release frequency: Monthly
Consensus forecast: 0.4%
Previous reading: 1.3%
Data source: US Bureau of Labor Statistics
POPULAR ARTICLES
1Solana Price Forecast: SOL comes under mounting bearish pressure as wider market sells off2US PPI in focus as British Pound’s losing run against US Dollar continues31.1050: EUR/USD Price Forecast Highlights Modest Gains Above This Level, With Upside Capped Below 100-day SMA4US Dollar outperformance drives further Indian Rupee correction5Indonesian Rupiah lifted by easing political uncertainty despite MSCI outflow risks623.6% Fibo. and 200-hour SMA: WTI Price Forecast favours bears below both7Cardano Price Forecast: Weak on-chain and derivatives signals suggest further ADA downside8Currency market: Japan’s Takaichi reports close contact with US financial authorities9176.50 Cleared: EUR/JPY Strengthens, but Price Forecast Remains Bearish Below 100-day SMA


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved