

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Yen holds steady under 160.00 as Japan inflation data nears
- USD/JPY is unchanged under 159.50 after three sessions of declines.
- Intervention worries near 160.00 and BoJ hike bets offset a stronger Dollar.
- Japan's national CPI for October is due Thursday, ahead of the BoJ in December.
The Dollar rose against most major currencies but not the Yen, which is backed by intervention warnings near 160.00 and an expected Bank of Japan (BoJ) hike. USD/JPY is unchanged on the session, just under 159.50, after three sessions of small declines from a high just above 160.00. That high was its highest since early September.
Japan and the US intervened together to buy Yen in late July, and Japan's finance ministry warned on November 12 that the currency had fallen too quickly. USD/JPY touched 160.00 that day and the next, and no close since has been above it. Demand for safer assets during the selloff in artificial intelligence (AI) stocks also lifted the Yen, analysts said.
BoJ Governor Ueda told parliament the bank should keep raising rates, and a poll of economists published Wednesday found 86% expect a hike to 1.50% in December. The Fed's 3.75%-4.00% rate is at least two and a half points above the BoJ's 1.25%, and its October minutes showed nearly all officials expecting to raise it further. USD/JPY has stayed within about a Yen of 160.00 for five sessions.
On the calendar
Japan's national Consumer Price Index (CPI) for October is due at 23:30 GMT on Thursday. The measure excluding fresh food is forecast at 2.3% after 2.1% in September, and the measure excluding food and energy was 2.4% last time. The figures feed the BoJ's December decision, where a hike to 1.50% is the majority forecast.
In the US, weekly jobless claims are due at 13:30 GMT on Thursday, forecast at 197K. Philadelphia Fed President Paulson speaks at 23:30 GMT, the same minute as Japan's release, and Fed Governor Cook speaks at 17:15 GMT on Friday. They bear on the size of the Fed's December 9 move, the US side of the rate gap.
On the charts
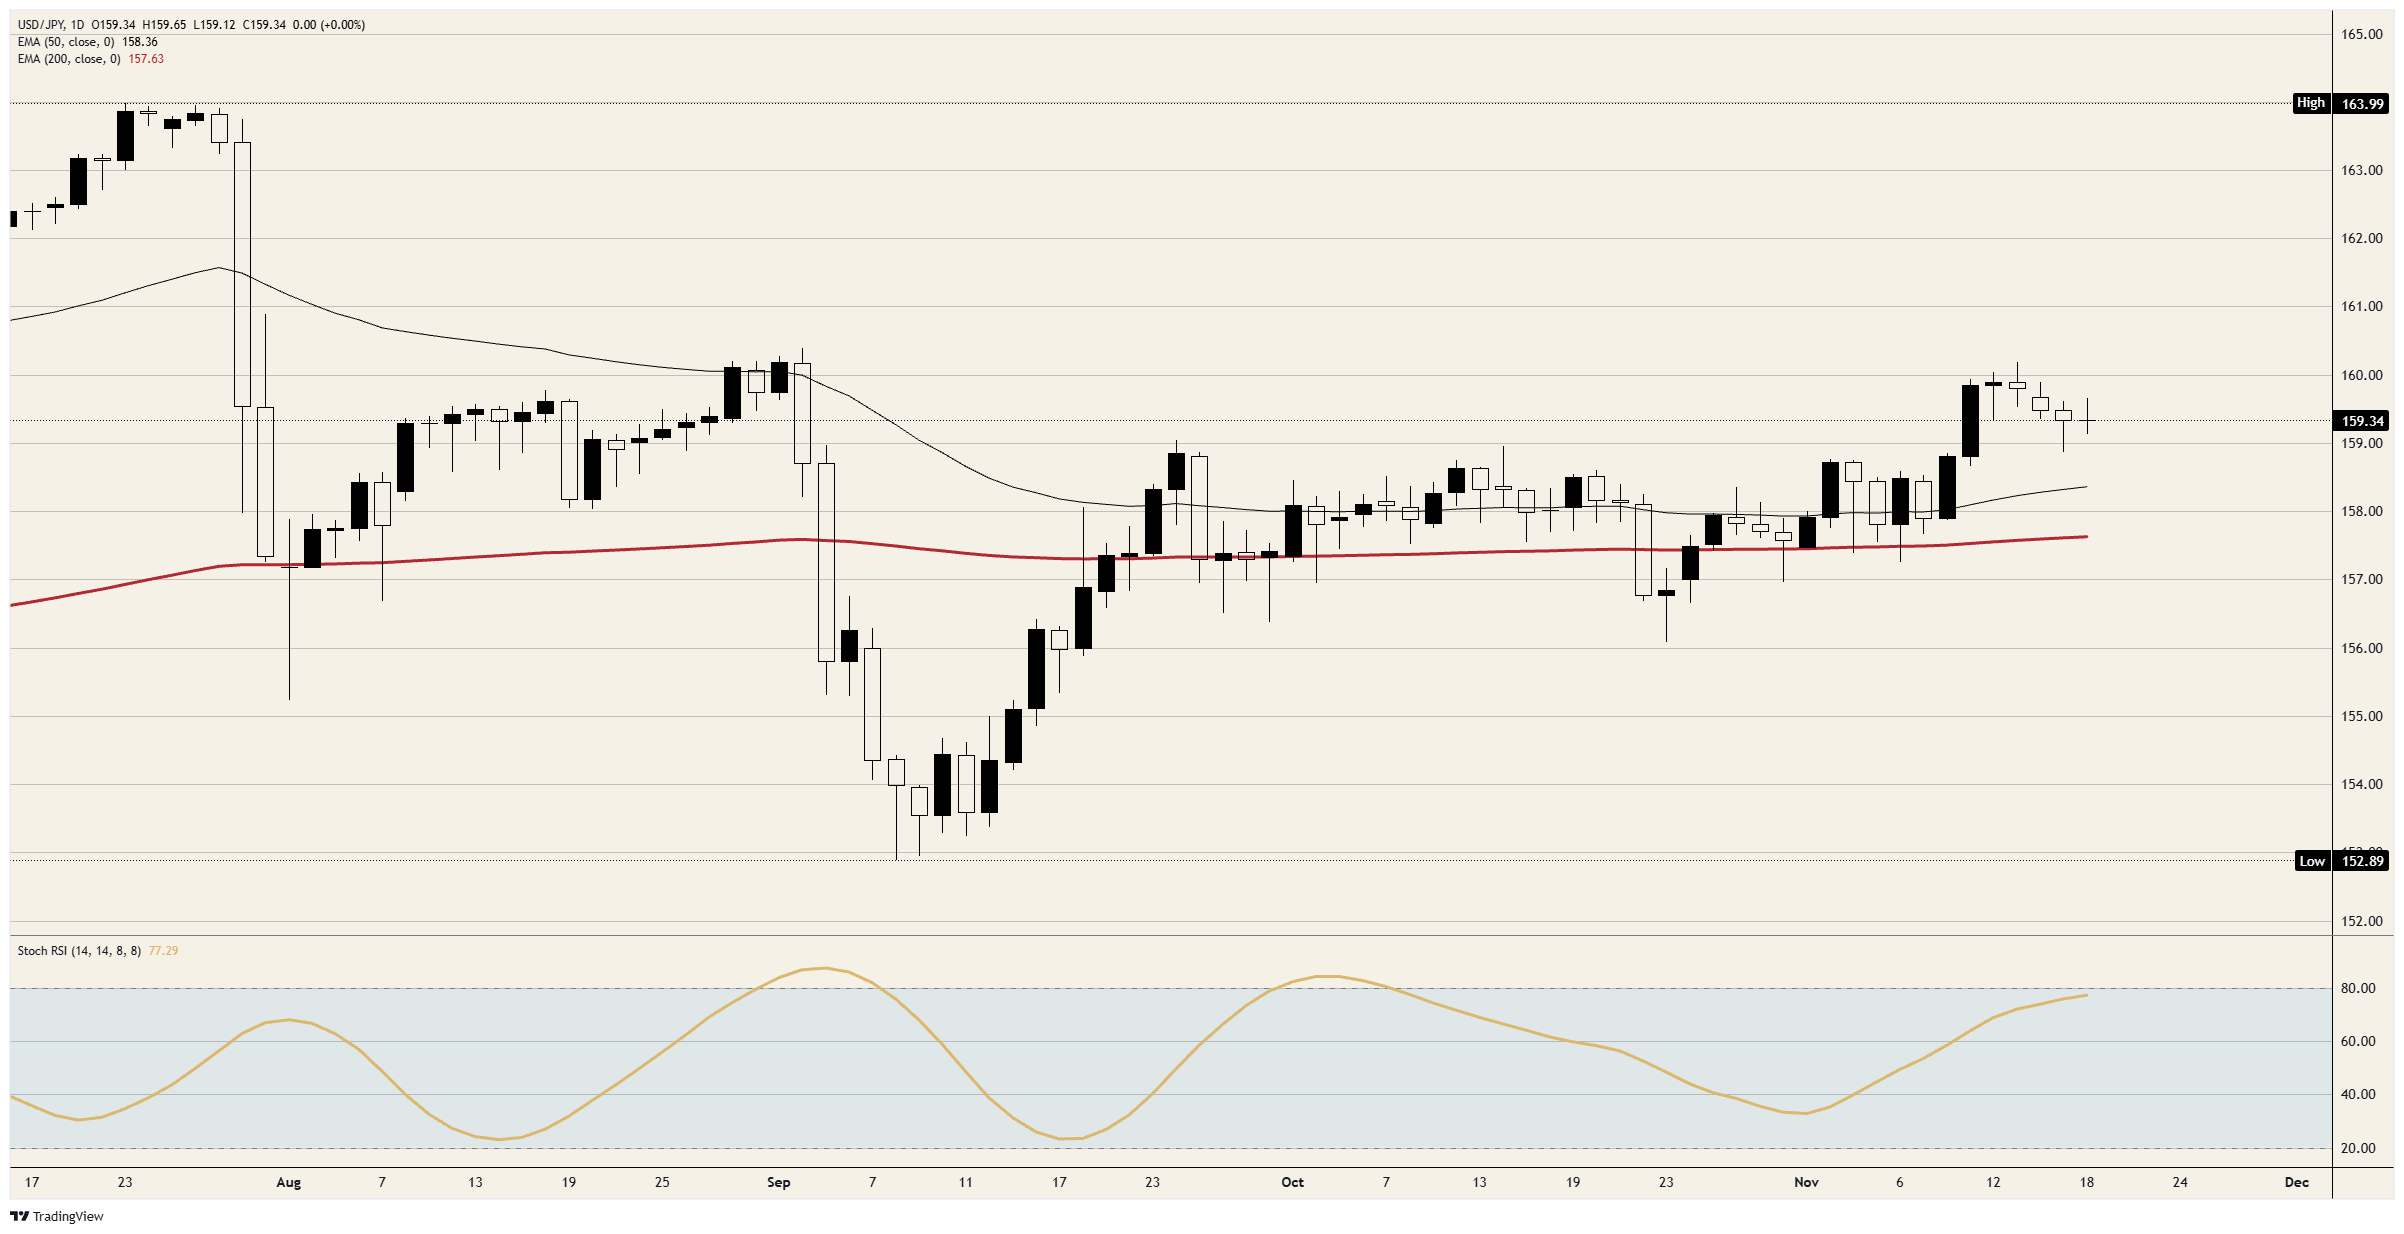
USD/JPY is above both of its main averages, with the 50-day Exponential Moving Average (EMA) just under 158.50 and the 200-day EMA near 157.50. It has recovered almost three-fifths of the drop from the July high just under 164.00 to the September low just under 153.00. Daily momentum is just short of overbought.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Top Articles
1Gold falls to 14‑month low below $3,750 on hawkish Fed rhetoric2Yen holds steady under 160.00 as Japan inflation data nears3Fed’s Kashkari: Markets believe central bank will have to hike more than officials now expect4Jobs data is next for an Australian Dollar at a four-month low5Pound returns to its October low before UK retail sales6ECB President Lagarde speaks next with the Euro under 1.10007Dow Jones Industrial Average drops as UnitedHealth and Nvidia fall8Bitcoin bearish signals deepen as demand contracts by 400K BTC9Ethereum Price Forecast: ETH fails to recover $1,800 after futures and spot distribution


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved