

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
US Dollar pressure from US midterm elections lifts Indian Rupee further
- Weakness in the US Dollar helps the Indian Rupee extend its rally.
- A Senate majority goes to Democrats, who also lead the House vote count.
- A Democratic victory does not imply structural US Dollar weakness, according to ING.
Gains in the Indian Rupee (INR) against the US Dollar (USD) continue on Wednesday as early United States (US) midterm election trends indicate a Democratic victory in both the House and the Senate.
Broad US Dollar weakness has pushed USD/INR 0.1% lower to around 94.60 in opening trade. At the time of writing, the US Dollar Index (DXY), which measures the Greenback against six major currencies, is down 0.4% at around 101.48. Despite recouping a substantial portion of its intraday losses after falling towards 101.25, the DXY remains sharply lower.
Where does the US midterm election count stand?
With counting still under way, the BBC reports that Democrats have secured 50 seats for a Senate majority. Results have been counted for 294 of the House's 435 seats, with Democrats ahead on 184 seats. A party requires 218 seats to secure an outright majority.
A Democratic win in both the House of Representatives and the Senate is expected to affect the US Dollar significantly.
In an earlier warning, ING said that “fears of tougher regulation could weigh on Artificial Intelligence (AI) stocks (we’ve recently seen how that can hit the greenback), while markets could price in greater risks of decision-making gridlock around issues such as government funding and the debt ceiling.”
Nevertheless, ING dismissed concerns about a structural change in the Dollar's direction, noting that the greenback “continues to respond predominantly to the Fed story, which shouldn’t face an immediate and direct impact from the midterm result”.
Which US economic releases will markets watch?
Expectations for Federal Reserve (Fed) interest rates are likely to be shaped significantly by October's Nonfarm Payrolls (NFP) report, due on Friday. The report is among the key US economic releases investors will monitor closely this week.
Before the official US employment report, markets will turn to October's US ADP Employment Change figures, scheduled for release later in the day at 13:15 GMT. Private-sector job additions are expected to come in at 69K, below September's 90K.
USD/INR Technical Analysis: Can the pair overcome EMA resistance?
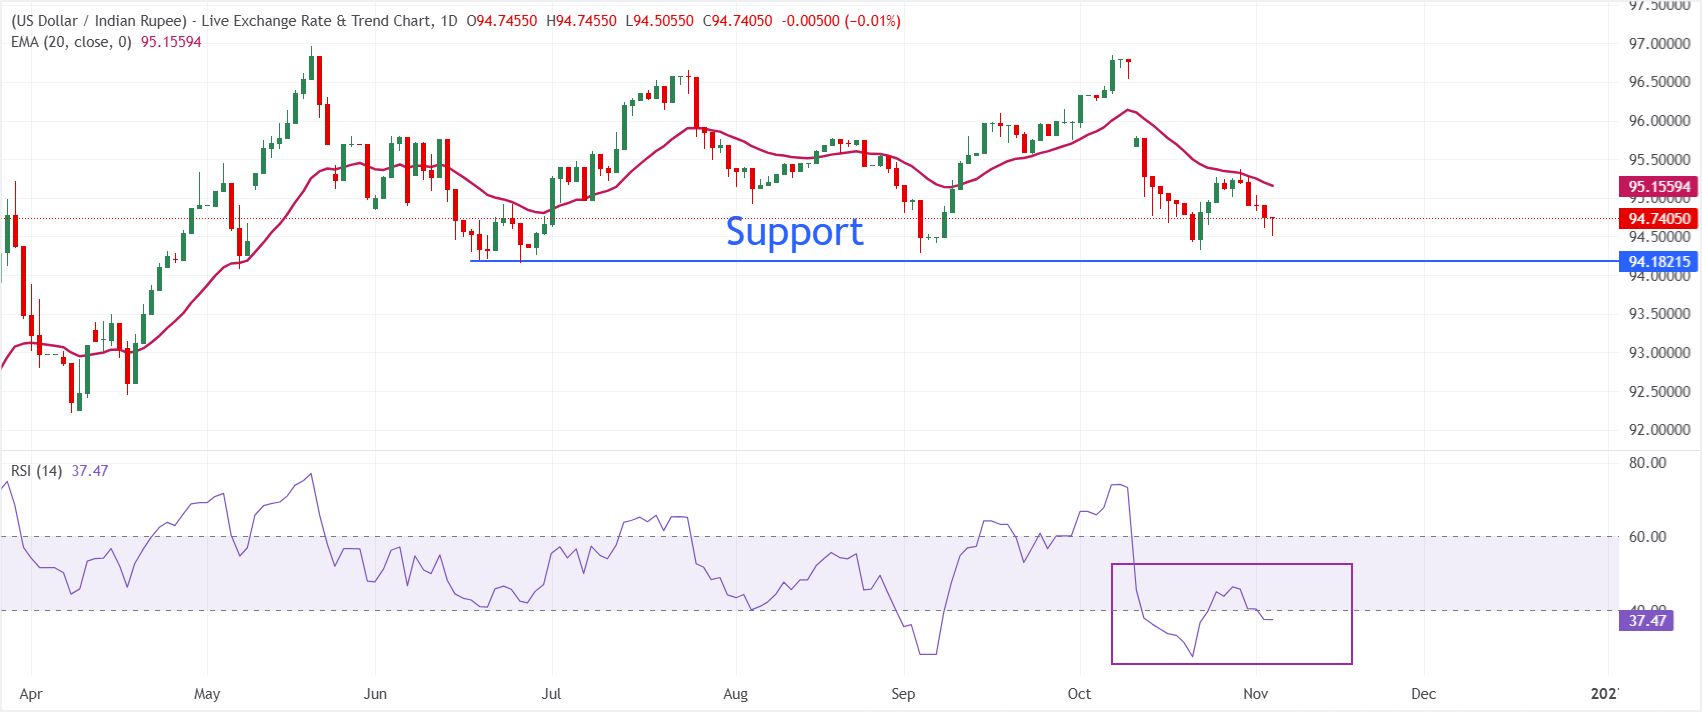
A bearish near-term outlook persists on the daily chart, where USD/INR trades at 94.7405, below its 20-day exponential moving average (EMA) of 95.1559. Following a pullback from recent highs, this dynamic resistance continues to limit the pair's advance. Meanwhile, a Relative Strength Index (RSI) reading of around 37 points to persistent downside pressure, although it has not yet reached oversold territory.
To reduce the current bearish bias and open the way for a recovery, the pair would need a daily close above immediate resistance at the 20-day EMA, near 95.16. The available dataset does not identify clear structural support levels. Traders may therefore consider recent swing lows and psychological levels below the current price as possible demand zones. The overall set-up nevertheless favours sellers while the price remains below the 20-day EMA.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee: Frequently asked questions
External developments have a particularly strong influence on the Indian Rupee (INR). Major drivers include Crude Oil prices, given India's heavy dependence on imported Oil; the US Dollar's value, as most trade is denominated in USD; and foreign investment levels. The Rupee is also strongly influenced by the interest rates set by the Reserve Bank of India (RBI) and its direct intervention in FX markets to stabilise the exchange rate.
To support trade through exchange-rate stability, the Reserve Bank of India (RBI) intervenes actively in the forex market. It also adjusts interest rates in an effort to keep inflation at its 4% target. A rise in interest rates generally supports the Rupee through the ‘carry trade’: investors borrow in lower-interest-rate countries and invest the proceeds in countries offering relatively higher rates, earning the difference.
Inflation, interest rates, GDP growth, the trade balance and foreign investment inflows all help determine the Rupee's value. Faster economic growth can attract additional overseas investment and increase demand for the currency. A narrowing trade deficit will eventually strengthen the Rupee as well. Higher interest rates are another source of support, particularly higher real rates, which are interest rates adjusted for inflation. Greater appetite for risk can also attract more Foreign Direct and Indirect Investment (FDI and FII), benefiting the Rupee.
The Rupee generally faces pressure from higher inflation, especially when it exceeds levels in India's peer economies, because this reflects a loss of value caused by oversupply. By making exports more expensive, inflation also results in more Rupees being sold to pay for foreign imports, weighing on the currency. However, rising inflation typically prompts the Reserve Bank of India (RBI) to increase interest rates. The resulting increase in demand from international investors can support the Rupee. Lower inflation has the reverse effect.
POPULAR ARTICLES
1Equities: How are Democratic gains shaping global market reactions? – Deutsche Bank2NZD/USD: Key support stands at 0.55603US Dollar: How is the Blue wave reshaping growth and risk? – Commerzbank4Euro: Does the upside bias favour a move towards 1.1250 against US Dollar? – UOB5Solana Price Forecast: Is SOL facing greater downside risk after slipping below $92?6US Dollar pressure from US midterm elections lifts Indian Rupee further7Swiss Franc gathers pace amid US Dollar weakness after US midterm elections8EUR/USD Price Forecast: Gains above 1.1200 face a ceiling below the 100-day SMA9With Democrats targeting victory in both Houses, Australian Dollar recovers


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved