

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
UK retail sales beat leaves pound steady at three-month low
- GBP/USD recovers from a three-month low following declines in seven of the past eight sessions.
- A half-point rate hike remains under discussion among Fed officials despite lower US inflation expectations.
- Monday brings UK and US PMIs and remarks from BoE Chief Economist Pill, ahead of Wednesday's US core PCE release.
Selling pressure on the Pound has eased, but stronger UK retail sales and softer US inflation expectations have offered little more than a breather. After slipping just below 1.3100 to its weakest level in more than three months, GBP/USD is trading marginally above that mark again. Following losses in seven of the previous eight sessions, the recovery has yet to clear the midpoint of Thursday's trading range.
Interest-rate expectations on both sides have shifted against the Pound. On Wednesday, Fed Governor Waller advocated a half-point increase at the 8-9 December meeting, while Chicago Fed President Goolsbee has left that option open. Markets have fully priced in a quarter-point rise, which would lift the Fed's rate to 4.00%-4.25%, compared with the UK's 4% Bank Rate, eight days before the Bank of England (BoE) meets. Meanwhile, traders assign a probability of nearly 80% to a BoE hike, compared with 90% before Wednesday's UK inflation figures.
Against expectations of no change, UK retail sales increased 0.7% in October. According to the Office for National Statistics, purchases of tinned food and long-life milk following the government's Be Ready emergency campaign accounted for part of the rise. That reflects stockpiling rather than the kind of demand that would support a BoE rate increase. Separately, the University of Michigan's one-year inflation expectations declined from 4.3% to 3.7%, reducing the case for a half-point increase by the Fed.
Which releases and speeches could shape rate expectations?
Monday's UK calendar includes November Purchasing Managers Index (PMI) readings at 09:30 GMT, followed by BoE Chief Economist Pill's speech at 13:00 GMT. Speaking to the Financial Times on 14 November, Pill said rates would have to rise again in 2027 in addition to December. Both the PMI figures and his remarks therefore have a bearing on the 17 December decision.
Remarks from Fed Governor Cook are scheduled for 17:15 GMT on Friday, with New York Fed President Williams due to speak at 21:00 GMT on Monday. Attention then turns to October's core Personal Consumption Expenditures Price Index (PCE) inflation release at 13:30 GMT on Wednesday, 25 November. The forecast is for a year-on-year reading of 3.2%, up from 3.1%. The figures will inform the choice between a quarter-point and a half-point increase on 9 December.
What do the charts indicate for GBP/USD?
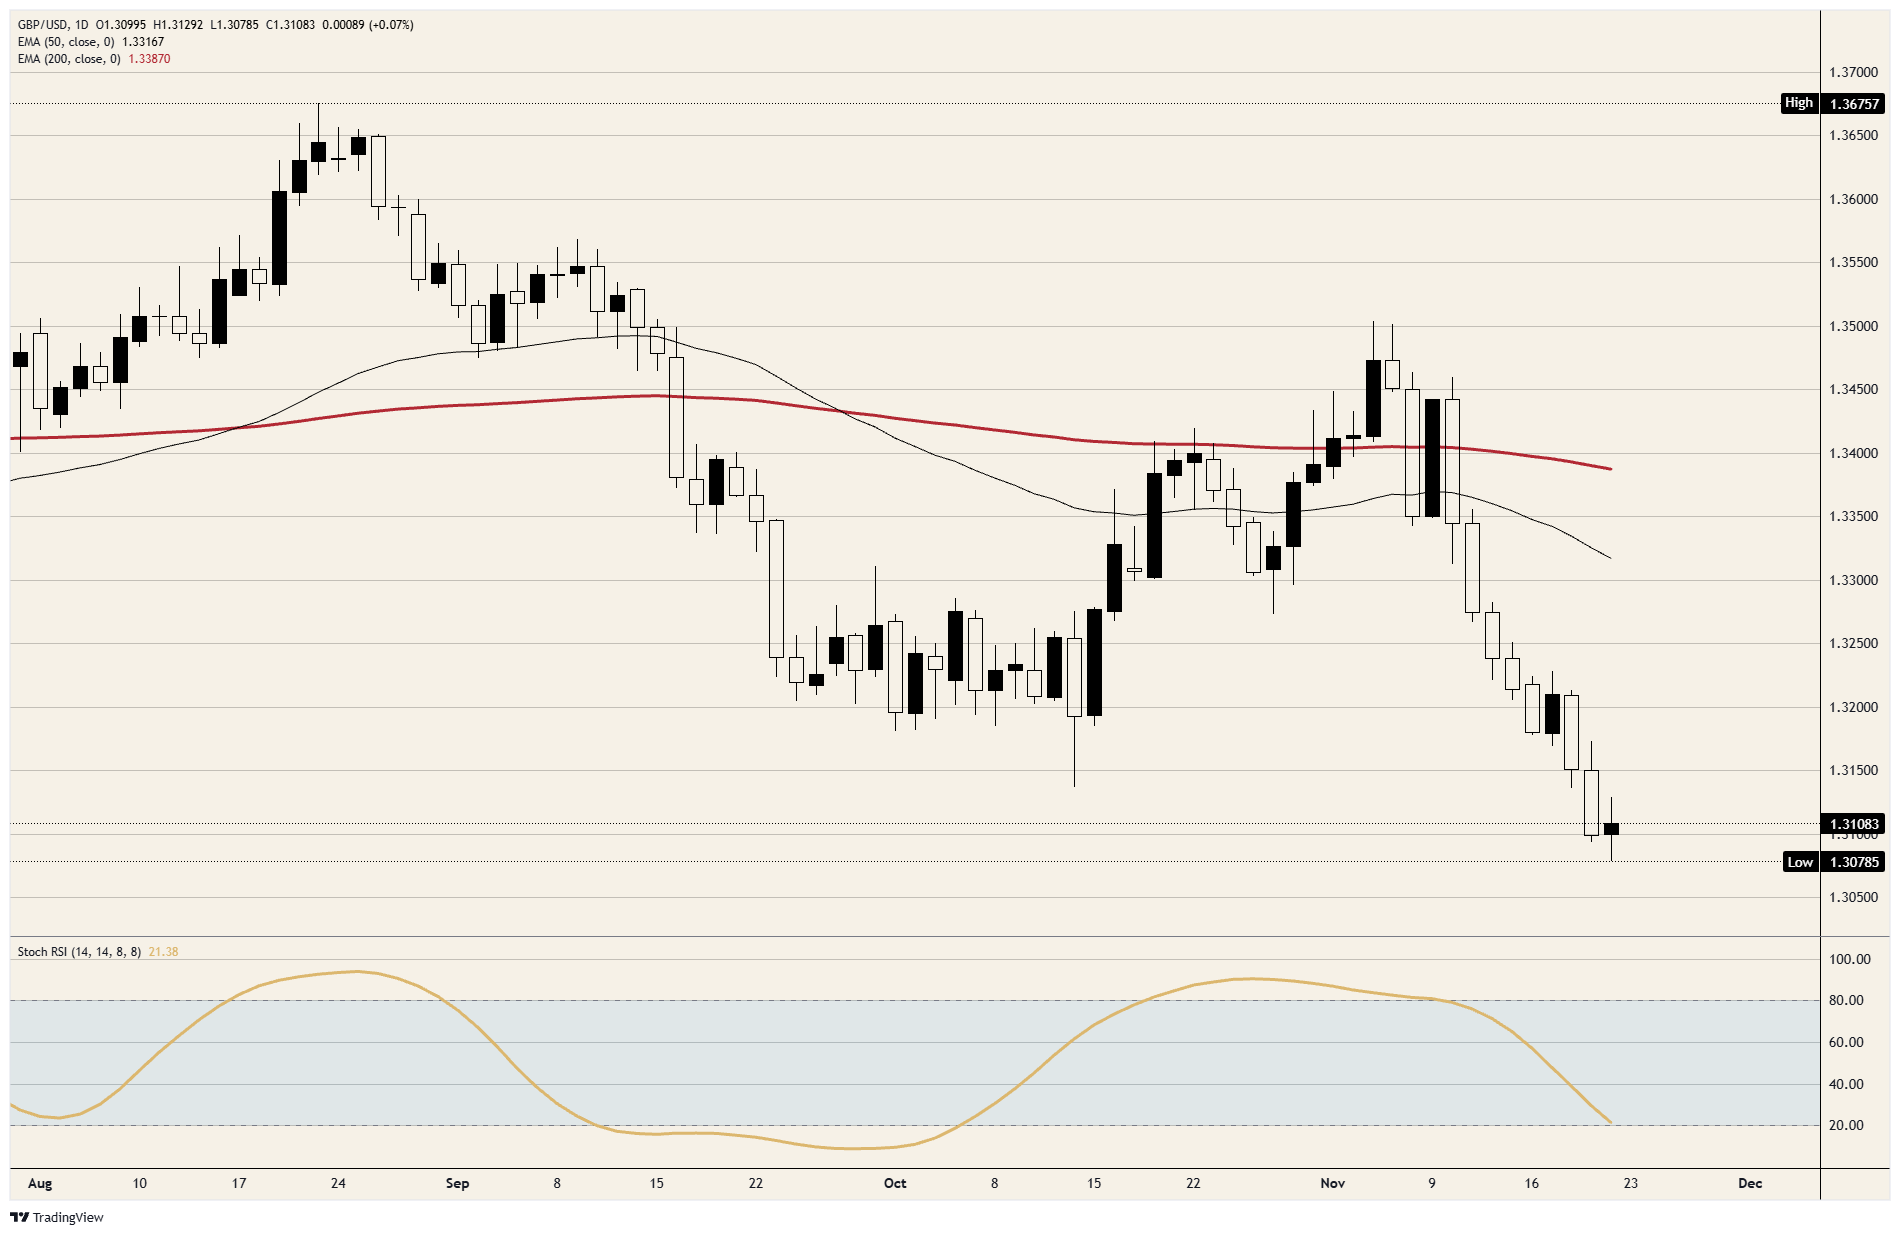
GBP/USD has now surrendered its entire recovery from October's low near 1.3150 to the 4 November high near 1.3500. That advance had retraced roughly two-thirds of the decline from August's peak just below 1.3700. Sitting just above 1.3300, the 50-day Exponential Moving Average (EMA) remains below the 200-day EMA, which is just under 1.3400. Daily momentum, overbought at the beginning of November, has since weakened to the threshold of oversold territory.
GBP/USD: daily price chart
Pound Sterling: frequently asked questions
Dating back to 886 AD, the Pound Sterling (GBP) is the world's oldest currency and serves as the United Kingdom's official currency. According to 2022 data, it ranks fourth globally by foreign exchange (FX) trading activity, representing 12% of all transactions and an average daily volume of $630 billion. Among its principal currency pairs, GBP/USD, also called ‘Cable’, accounts for 11% of FX trading. GBP/JPY, referred to by traders as the ‘Dragon’, represents 3%, while EUR/GBP accounts for 2%. Responsibility for issuing the Pound Sterling rests with the Bank of England (BoE).
Monetary policy set by the Bank of England is the most influential factor in determining the Pound Sterling's value. Policy decisions centre on whether the BoE has met its principal objective of “price stability” – keeping inflation steady at around 2%. Adjusting interest rates is its main means of achieving that objective. To curb excessively high inflation, the BoE raises interest rates, increasing borrowing costs for households and businesses. Higher rates usually support GBP by making the UK a more appealing destination for international investors' funds. Conversely, inflation that falls too low signals slowing economic growth. The BoE will then consider cutting interest rates to make credit cheaper, encouraging businesses to borrow more and invest in projects that generate growth.
By providing a measure of economic health, data releases can move the Pound Sterling. GDP, Manufacturing and Services PMIs, and employment figures are among the indicators that can determine GBP's direction. Sterling benefits from a robust economy, which draws in more overseas investment and may also prompt the BoE to raise interest rates, directly strengthening GBP. Weak economic readings, by contrast, are likely to weigh on the Pound Sterling.
The Trade Balance is another important release for the Pound Sterling, showing the difference between a country's export earnings and its import spending over a specified period. Strong overseas demand for a country's exports creates additional demand for its currency as foreign buyers seek to purchase those goods. A positive net Trade Balance therefore supports the currency, whereas a negative balance has the opposite effect.
POPULAR ARTICLES
1Canadian retail sales give the Loonie a pause at a 19-month low2UK retail sales beat leaves pound steady at three-month low3Hong Kong: Cautious re-engagement is spurred by policy support – BNY4Euro remains on course for third weekly decline despite modest gains as US Dollar softens5Breaking: Mounting selling pressure drives Bitcoin below $60,0006Bitcoin vs Gold Forecast: Why are BTC and XAU extending losses amid hawkish Fed expectations?7Gold: Bullish case holds despite a setback – TD Securities8Canada: RBC Expects Modest Q4 Growth Despite Weak Q39Silver Price Forecast: Will XAG/USD test the 200-week SMA as selling pressure persists?

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us









Contacts
Phone: +61 2 8036 8388
Fax: +61 2 8036 8388
Email: support@tmgm.com



The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved